

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
InGaAs Image Sensors Market to Reach USD 268.39M by 2032 at 7.1% CAGR — PW Consulting

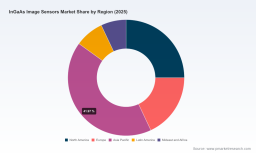
InGaAs Image Sensors Market — Strategic Outlook for 2026 Decision Makers
As organizations plan capital allocations, product roadmaps, and supply-chain redesigns for 2026, InGaAs (Indium Gallium Arsenide) image sensors represent a discrete but strategically important technology vector. Our new PW Consulting market study synthesizes historical performance (2020–2025), forward-looking projections (2026–2032), competitive intelligence, and operational levers into an actionable playbook. This introduction sets the strategic context and explains how the full report can materially alter risk-return assessments and go-to-market choices in the coming 12–18 months.
InGaAs Image Sensors Market
Market Trajectory: Macroeconomics that Matter
Demand for InGaAs image sensors has moved from niche specialization toward broader industrialization over the past half-decade. The total market expanded steadily through 2025 and is projected to grow at a compound annual growth rate (CAGR) of approximately 7.1% across our 2026–2032 forecast window. To ground strategy conversations, note the market has roughly progressed from its early-2020 baseline through a materially larger footprint in 2025, and our modeling anticipates continued maturation and scale by 2032 — driven by a mix of product refresh cycles, new application wins, and incremental adoption across inspection, spectroscopy, and defense-related imaging segments.
InGaAs Image Sensors Market
Two high-level takeaways are critical for 2026 decisions: first, this is a growth market — not hyper-scale like mainstream CMOS, but predictable and financable; second, growth is uneven across use cases and geographies, which means targeted investments and partnerships will yield outsized returns compared with broad-based exposure.
InGaAs Image Sensors Market
Why This Study Is Strategically Valuable for 2026
- Risk-weighted capital allocation: The report translates aggregate growth into probabilistic scenarios that help CFOs and strategy teams vet capex for specialized fabs, photodiode hybridization lines, or strategic inventory buffers for critical raw materials.
- Product roadmap calibration: Engineers and product leaders receive prioritized feature matrices and trade-off analyses (spectral range vs. cooling vs. pixel architecture) that speed time-to-market while preserving margin.
- Supply-chain resilience planning: We map geopolitical exposures, supplier concentration, and critical-material fault lines so procurement teams can craft hedging, dual-sourcing, or vertical-integration strategies befitting 2026 realities.
- M&A and partnership scouting: The study identifies capability gaps that are acquisition- or alliance-friendly — from hybrid-readout ROIC specialists to turnkey camera integrators — and quantifies the strategic rationale for each move.
- Regulatory and tariff playbook: With trade-policy noise and selective tariff exposures an active variable, legal and commercial leads can use our scenarios to determine contract structures, re-shoring thresholds, or refund-claiming strategies.
Core Findings (Teaser)
- The InGaAs sensor market is consolidating slowly: concentration among the largest global vendors remains modest, leaving ample opportunity for focused challengers. Our concentration metrics and company-level margins in the full report show a market where thoughtful specialization can still outrun scale alone.
- Thermal management is a technical and commercial hinge: room-temperature operation versus TE-cooled solutions defines different value chains, margin profiles, and addressable applications. The competitive trade-offs are explored with case studies and ROI models in the study.
- Materials and foundry captivity matter more than product roadmaps in many scenarios: epitaxial quality, hybridization yield, and clean-room vertical integration explain a large part of variance in time-to-profit for new designs.
- Near-term regulation and tariff dynamics are non-trivial: recent policy actions have shifted contractual risk and created opportunities for manufacturers willing to adapt logistics and regional footprints.
Operational Imperatives for 2026
- Selective vertical integration: Where margin compression is imminent, integrate only the process nodes or lines that materially improve yield or reduce lead time. Full-scale backward integration is rarely justified without a multi-year volume commitment.
- Modular product architectures: Design sensor families that share ROICs, firmware stacks, and mechanical interfaces to shorten qualification cycles for new applications such as food inspection, semiconductor metrology, or SWIR-enabled automation.
- Inventory and supplier network rebalancing: Lock in long-lead raw materials for core SKUs, while experimenting with alternate suppliers for secondary lines. Scenario stress-testing in the report shows the optimal buffer levels to balance working capital with service levels.
- Commercial segmentation & pricing: Adopt value-based pricing for premium, cooled, or custom hybridized devices, and volume-tier pricing for commoditized linear arrays used in embedded inspection.
Competitive Landscape — Who Shapes the Market (Executive View)
The InGaAs ecosystem features established optical specialists, diversified aerospace OEMs, and focused SWIR camera houses. The market combines high technical barriers (epitaxy, hybridization, ROIC design) with domain-specific go-to-market channels (defense primes, industrial OEMs, scientific distributors). Key players illustrate different strategic postures:
- Hamamatsu Photonics K.K. (Japan): A classical optics and sensor house with a broad VIS–SWIR product line, including linear and area devices geared to spectrometry, microscopy, and machine vision. Recent product activity demonstrates an emphasis on high-speed linear arrays for foreign object detection and specialized modules that simplify systems integration.
- Teledyne Technologies Inc. (USA): Combines detector chemistry expertise with cooled and room-temperature detector offerings, focusing on spectroscopy, biomedical instrumentation, and aerospace imaging. Their breadth across detector cutoffs and cooling options gives them flexibility in cross-selling to high-value instrument OEMs.
- Sensors Unlimited (RTX Collins Aerospace / Raytheon) (USA): A defense- and surveillance-focused player with camera-level offerings spanning visible to extended SWIR. Their business model centers on supplying mission-critical systems where supplier reliability and certification are decisive buying criteria.
- Exosens / Xenics (Belgium): European camera and detector designer specializing in hybrid ROIC–InGaAs solutions for line-scan and area-scan markets. They play a strong role in bespoke and small-series industrial applications.
- New Imaging Technologies (NIT / LYNRED) (France): Focused on SWIR sensors and cameras from line-scan to Full HD; recent product releases emphasize high-speed inspection oriented at industrial customers, signaling an aggressive push into high-volume automated quality-control markets.
- Sony Semiconductor Solutions Corporation (Japan): A major semiconductor OEM applying advanced bonding and pixel techniques to deliver visible+SWIR high-resolution sensors for material inspection and semiconductor processes, representing the bridge between mainstream imaging scale and SWIR specialization.
Each competitor embodies a repeatable route-to-value — whether through product breadth, systems integration, defense certification, or industrial automation partnerships. The full report maps these routes against our scenario models and contains vendor scorecards assessing technology moat, scale economics, and partnership fit.
Recent Developments — Signals You Can Act On
- Several vendors have released new high-speed line and linear array products aimed at industrial inspection, signaling that automation-driven SWIR use cases are accelerating adoption cycles.
- Web-announced product updates in 2025–2026 demonstrate vendors’ attempts to reduce system integration friction via CAD models and expanded camera offerings — a clear signal that channel and OEM enablement are priorities.
- Regulatory and tariff notices have already influenced commercial contracts and refund-claim strategies; firms that preemptively restructure logistics or contractual language have reduced effective cost volatility in our scenarios.
Key Risks & Sensitivities
- Raw-material concentration: Indium and gallium sourcing remains geopolitically concentrated, which creates commodity risk that disproportionately affects InGaAs producers versus silicon CMOS players.
- Fabrication complexity and yields: Epitaxial growth and hybridization yield curves are non-linear; small improvements in process control can unlock outsized margin gains while missteps can delay product launches.
- Policy and export controls: Tariff shifts or export control updates can change total landed costs and customer eligibility overnight; commercial teams must model such inflection points into contract terms.
- Market fragmentation: While the market is growing, concentration metrics indicate significant room for new entrants and niche specialists — which raises competitive intensity in high-margin subspaces.
What the Full Report Contains (Actionable Deliverables)
- Scenario-based financial models converting the market CAGR and macro drivers into P&L and ROIC outcomes for different strategic choices.
- Vendor scorecards with technology assessments, roadmaps, channel maps, and partnership recommendations tailored to corporate priorities.
- Supply-chain playbooks, including dual-sourcing options, inventory-sizing heuristics, and recommended contractual clauses to mitigate tariff and raw-material shocks.
- IP and fabrication gap analysis identifying which capabilities are acquisition-worthy versus build-in-house candidates, with suggested valuation multipliers.
- Commercial segmentation frameworks and go-to-market templates for OEM, system integrator, and direct channel strategies.
- Implementation timelines and checklists to operationalize 12–18 month programs (R&D sprints, qualification plans, manufacturing scale-up).
How to Use This Study in 2026 Planning Cycles
- Combine the report’s scenario outputs with internal product backlog priorities to re-sequence development investments toward sensor configurations with the best risk-adjusted margin potential.
- Use the supply-chain playbooks to test procurement contracts and to set trigger points for establishing secondary suppliers or localized production.
- Apply the M&A and partnership frameworks to prioritize targets that fill capability gaps within 6–18 months rather than long-horizon platform bets.
- Present distilled vendor scorecards to procurement and engineering to accelerate vendor rationalization and qualification choices.
Next Steps
This introduction is designed to surface the strategic contours of the InGaAs image sensors opportunity and to clarify how the full PW Consulting study equips teams to make confident 2026 decisions. For procurement managers, engineering leads, corporate development teams, and executive committees contemplating exposure to SWIR imaging, the full report contains the granular, actionable datasets and supplier- and SKU-level analyses you will need — including precise regional and application-level splits, supplier share detail, and transaction-grade scenario templates.
Contact PW Consulting to access the complete study, the underlying financial models, and a tailored briefing that maps the findings directly onto your organization’s objectives for 2026.
For detailed analysis of this topic, please visit the official page: InGaAs Image Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com