

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Sucker Rod Market to Reach USD 3.07 Billion by 2032 at 5.5% CAGR

Preparing for 2026: Strategic Insight into the Global Sucker Rod Market
Executive snapshot
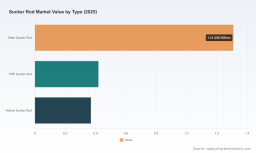
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a tightly focused introduction to our latest Sucker Rod Market study — an essential strategic companion for corporate leaders, investors and procurement teams planning for 2026. The segment has moved from recovery to selective growth: the market expanded from roughly 1.55 Billion USD in 2020 to about 2.10 Billion USD in 2025 and — under our central forecast trajectory — is expected to grow at a compound annual growth rate (CAGR) of approximately 5.5% through the 2026–2032 horizon, reaching a little over 3.0 Billion USD by 2032. These headline dynamics set the stage for a year in which decisions on sourcing, product mix, aftermarket services and capital allocation will materially affect competitive position.
Sucker Rod Market
Why this matters for decisions taken in 2026
-
Timing and scale of investments: The market’s mid-single-digit CAGR signals steady expansion but not runaway demand; that changes the calculus for greenfield capacity versus technology-led differentiation. Firms considering new production lines, strategic alliances or targeted M&A in 2026 need a finely calibrated view of near-term demand elasticity and capex breakeven points.
Sucker Rod Market -
Input-cost sensitivity: Volatility in steel and galvanized processing inputs remains a continuous source of margin pressure. Procurement strategies that rely solely on spot purchasing are exposure-heavy; integrated hedging, longer-term supplier contracts and design-for-materials substitution (e.g., composite/hollow alternatives in selected applications) should be re-evaluated in procurement playbooks.
Sucker Rod Market -
Regulatory and trade overlays: The industry operates inside several active technical and trade regimes. API 11B remains the governing specification with ongoing product-documentation updates by leading mills. Import controls and licensing regimes in key markets add compliance and timing risk that must be baked into supply chain lead-times and cost models for 2026.
-
Service and aftermarket economics: Given the market’s structure and the moderate concentration of larger suppliers, aftermarket services — remanufacturing, high-performance couplings, monitoring-enabled systems — are a high-leverage battleground for margin capture and customer lock-in.
What our report delivers — practical, decision-ready content
-
Robust market sizing and scenario projections: A transparent methodology covering historical 2020–2025 trajectories and three demand scenarios for 2026–2032, with sensitivity testing for oil-price shocks and input-cost swings.
-
Supply-chain map and lead-time stress tests: Line-item flow charts from raw material (steel, FRP feedstocks, specialty alloys) through conversion, finishing and aftermarket remanufacture; bottleneck scoring and contingency routing for 2026 procurement planning.
-
Commercial playbooks: Tender templates, TCO (total cost of ownership) calculators for rod selection (steel vs. composite vs. specialty hollow designs), and a procurement risk matrix aligned to regional trade and regulatory constraints.
-
Competitive benchmark and vendor scorecards: Qualitative and quantitative benchmarking of leading players across product breadth, geographic reach, API/ISO compliance, R&D footprint and aftermarket capability — delivered with a downloadable scorecard for supplier selection workshops.
-
Technology and innovation deep-dive: Evaluations of material-substitution trajectories, induction case-hardening and coupling alloys, and emergent monitoring integrations; engineering trade-offs are expressed in operational metrics (run-life, fatigue resistance, ease-of-repair).
-
Regulatory and compliance playbook: A distilled view of the active standards, border measures and environmental performance milestones likely to matter to buyers and OEMs during 2026 procurement cycles.
-
Actionable M&A and JV guidance: Target-screening criteria, value-creation levers for bolt-on acquisitions, and integration pitfalls observed across recent cross-border transactions in the oilfield equipment space.
Competitive landscape — who moves the market and how
The market exhibits moderate concentration (our CR3 and CR5 metrics indicate that the top-tier suppliers account for a meaningful share but do not dominate wholly). That structure creates a dual opportunity: large players can exploit scale and channel reach, while focused specialists can win on technology, speed-to-field and aftermarket services.
-
US Rod Manufacturing — the only domestically owned, fully integrated sucker rod manufacturer in the U.S. Their strength is a domestic, API-grade steel supply base and short lead-times for North American operators. Strategic implication: U.S.-focused operators seeking reduce-supply-risk solutions should prioritize local, API-compliant partners for critical wells.
-
Weatherford International — a technology-forward incumbent offering premium high-strength rods and fiberglass solutions, with recent product showcases indicating a push into extreme-condition applications and energy-efficiency claims for offshore use. Strategic implication: Weatherford’s product cadence and field testing activity make them a viable partner for operators prioritizing well-life extension or production optimization in demanding environments.
-
Tenaris — a global mill with API-compliant offerings and broad manufacturing reach. Tenaris combines materials expertise and scale, making it a logical anchor supplier for multiregional portfolios. Strategic implication: For asset owners with broad geographic exposure, partnering with global mills remains a risk-mitigation strategy for consistency and documented material provenance.
-
Chinese manufacturers and national suppliers — multiple China-headquartered producers offer cost-competitive production and extensive catalogues of sucker rod types. Their role in global trade is significant, but import licensing, border measures and variable lead-times make them most attractive for price-sensitive or non-time-critical procurement. Strategic implication: Use China-sourced supply selectively and always paired with compliance validation and contingency logistics.
-
Specialists and aftermarket champions — remanufacturers and materials specialists (including firms producing advanced alloy couplings) are shifting the value equation by extending run-life and enabling lower lifecycle cost. Strategic implication: Operators should model the economics of remanufacture and high-performance couplings alongside new-rod purchase pricing when deciding 2026 maintenance budgets.
Recent industry moves worth noting
-
Product launches and showcases from leading service companies are signalling increased focus on fiber-reinforced and ultra-high-strength rod chemistry for hostile wells — an engineering and procurement front to watch in 2026 tenders.
-
Collaborations to integrate sensors and condition-monitoring into sucker rod assemblies have moved from concept to near-commercial pilot stages. Expect OEMs and service vendors to press for trials in 2026 as part of long-term field reliability programs.
-
Regulatory activity remains active around import compliance and environmental performance. While the principal technical standard is stable, national authorities continue to apply licensing and enforcement measures that affect sourcing decisions and lead-times.
Principal risks and mitigants for 2026 planning
-
Input-cost shocks: Mitigate by blended sourcing strategies, longer-tenor contracts with indexed pricing, and accelerated evaluation of materials substitution where technically viable.
-
Compliance and trade interruption: Maintain validated alternate suppliers and pre-approved cross-border documentation to limit production downtime from regulatory actions.
-
Technology adoption lag: Pilot digital-monitoring systems on a controlled fleet of wells before wider rollout to ensure maintenance teams and analytics pipelines are mature when scaling in 2027–2028.
A pragmatic decision framework for 2026
-
Operators: Prioritize a mixed-sourcing strategy that pairs local API-compliant suppliers for critical assets with cost-competitive offshore sources for less-time-sensitive needs. Model TCO for remanufacture vs. new purchases.
-
OEMs and manufacturers: Accelerate product differentiation through materials and coupling innovations, and pilot sensor integration to create higher-margin service bundles.
-
Investors and private equity: Target bolt-on opportunities that add aftermarket services or remanufacturing capability; look for targets with validated quality systems and tight supplier relationships.
-
Procurement teams: Update RFP templates to require traceability to specification and supply-path redundancy; include service-level metrics for lead-time, recertification and failure-rate penalties.
Conclusion — why PW Consulting’s study is timely
The sucker rod market is at an inflection where steady top-line growth coexists with tightening margin dynamics and evolving technical demands. In this context, the right 2026 decisions—on sourcing strategy, product investment and aftermarket development—deliver disproportionate competitive advantage. Our full report supplies the granular datasets, regional and application segmentation maps, vendor scorecards and interactive scenario tools that governance boards and procurement committees need to convert these strategic priorities into executable plans.
For executives preparing capital plans, procurement bids, or M&A theses in 2026: the macro trajectory (2020–2025 recovery into a mid-single-digit growth forecast), the concentration profile, and the operational risk factors outlined above create a narrow window to act decisively. Access the full PW Consulting Sucker Rod Market study for the complete segment-level intelligence, downloadable vendor assessments and the proprietary TCO models that underpin our recommendations.
For detailed analysis of this topic, please visit the official page: Sucker Rod Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com