

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Wheat Seeds Market to Grow at 3.75% CAGR, Hits USD 6.94B by 2032

Wheat Seeds Market — Strategic Insights for 2026 Decision‑Makers
Executive snapshot
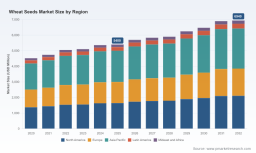
As organizations plan their 2026 strategies, understanding the wheat seeds market’s macro trajectory is essential. PW Consulting’s latest analysis uses 2025 as the base year and examines the historical period 2020–2025 and a forecast window spanning 2026–2032. At an aggregate level the market shows steady expansion from the early 2020s into the mid‑decade, with the 2025 market size measured at approximately USD 5.4 billion and a forecasted lift to roughly USD 6.94 billion by 2032 — reflecting a compound annual growth rate (CAGR) of about 3.75% over the 2026–2032 period. These headline numbers frame a market that is neither hyper‑explosive nor static: instead it rewards disciplined strategic moves and smart allocation of R&D, channel, and capital resources.
Wheat Seeds Market
Why this matters for 2026 decisions
-
Portfolio prioritization: With mid‑single‑digit CAGR ahead, decisions about which seed platforms, traits, and geographies to prioritize must be made with an eye toward multi‑year return profiles rather than short‑term share grabs.
Wheat Seeds Market -
Capital allocation: Investors and corporate strategy teams need to weigh incremental organic investments against bolt‑on M&A when growth is steady but segmentation and margin dynamics vary across seed types and markets.
Wheat Seeds Market -
Regulatory and commercialization timing: The introduction or wider adoption of novel genetics (including hybrid and GM varieties) and changes in insurance and seed‑production provisions materially alter risk‑adjusted returns for parent seed producers and seed companies alike.
Key market dynamics shaping 2026
-
Technology adoption heterogeneity: Hybrid wheat and advanced genetics are moving from R&D into commercial scale in select markets. Notable regulatory and commercialization milestones (such as the registration and launches by major players and the commercial availability of HB4 in certain jurisdictions) are accelerating producer interest, but adoption remains uneven by region and cropping system.
-
Regulatory regime shifts: In early 2026 the USDA updated Hybrid Wheat Seed Crop Provisions to improve insurance clarity for parent seed production — a development that reduces a specific production risk for seed companies and can alter investment calculus around parent‑seed multiplication and proprietary hybrid programs.
-
Consolidation vs. fragmentation: The global seeds and ag‑chemicals complex continues to concentrate at the top: independent analyses document that the largest multinational firms command a substantial share of the overall seed market. That said, measured concentration metrics for the wheat seed segment indicate a market with meaningful space for regional specialists and agile challengers; the top three firms account for a modest portion of the market, and the top five remain at a level that supports active competition and niche playbooks.
-
Commercial launches as signals: Syngenta’s early‑2026 registration and roll‑out of hybrid wheat varieties in parts of Europe, and recent hybrid wheat revenue contributions reported by major chemical‑seed integrated players, illustrate how commercialization timing and targeted geography roll‑outs can quickly re‑shape competitive dynamics within a crop segment.
-
Geopolitical and supply chain risk: Seed production, treatment supply, and logistics constraints are persistent sources of execution risk. Seed companies that control or secure upstream multiplication and certification pathways are better positioned to maintain planting‑season availability and premium pricing.
Competitive landscape — who matters and why
The wheat seeds competitive map blends multi‑national integrators, regionally dominant breeders, and nimble speciality firms. Below are concise strategic readings of core companies covered in our full study; each profile integrates observable recent activity, capability strengths, and strategic levers relevant to 2026 planning.
-
Bayer AG (Leverkusen, Germany; https://www.bayer.com) — A large agro‑technology integrator with deep R&D resources and global channel reach. Strategic emphasis is likely on leveraging trait portfolios and integrated crop protection offers to defend and grow wheat seed positioning where economics support premium genetics.
-
Corteva Agriscience (Indianapolis, USA; https://www.corteva.com) — A global seed and trait player with scale in breeding platforms. Corteva’s strategic playbook typically focuses on combining germplasm advancement with distributor partnerships and digital offerings to improve on‑farm ROI for adopters.
-
Syngenta Group (Basel, Switzerland; https://www.syngenta.com) — Recent registration of a hybrid wheat platform in Europe signals a deliberate push into commercial wheat hybrids. Expect focused regional roll‑outs, grower demo programs, and close attention to seed production economics as Syngenta scales supply.
-
BASF SE (Ludwigshafen, Germany; https://www.basf.com) — An integrated solutions provider where hybrid wheat has begun to contribute to agricultural solutions revenue in key European markets. BASF’s advantage is cross‑selling to existing crop protection customers and optimizing seed treatment packages.
-
Groupe Limagrain (Bourg‑Laval, France; https://www.limagrain.com) — A major cooperative‑rooted breeder with strong varietal pipelines and deep regional distribution in Europe. Their strategic strength lies in local adaptation and farmer trust.
-
KWS SAAT SE & Co. KGaA (Einbeck, Germany; https://www.kws.com) — Strong pedigree in cereals breeding and a clear focus on both conventional and hybrid approaches where agronomics justify adoption. Capabilities in seed multiplication and trait introgression are core assets.
-
RAGT Semences (Montauban, France; https://www.ragt.com) — A regional leader in Europe with emphasis on varietal performance and farmer engagement programs.
-
Florimond Desprez (Bourges, France; https://www.florimonddesprez.com) — Specialized breeder with targeted varietal pipelines and strong relationships in key wheat‑growing territories.
-
AgReliant Genetics (Delaware, USA; https://www.agreliable.com) — A North American hybrid and conventional seed player focused on commercialization speed and distributor partnerships.
-
Land O’Lakes Inc. (Arden Hills, Minnesota, USA; https://www.landoakes.com) — Combines seed, agronomy services and cooperative channels; strategic assets include farmer network access and on‑farm advisory reach.
-
ProHarvest Seeds (USA; https://www.proharvestseeds.com) — A U.S.‑focused seed company emphasizing regional adaptation and grower relationships.
-
AgriMAXX Wheat (USA; https://agrimaxxwheat.com) — Niche specialist concentrating on hybrid wheat development and commercialization paths in the U.S.
-
Bioceres Crop Solutions (Buenos Aires, Argentina; https://www.biocerescrops.com) — Notable for bringing HB4 GM wheat to commercial sale in Argentina and continuing distribution; an example of how biotech innovation can shift local market dynamics and trigger cross‑border strategic questions.
Report contents — what PW Consulting provides (practical and operational)
Our full report is designed as a decision‑ready toolkit for executives, investors, and product teams. Highlights include:
-
Aggregate market sizing and trend analysis (base year 2025; historical 2020–2025; forecast 2026–2032) with scenario‑driven projections tied to adoption curves and regulatory outcomes.
-
Competitive playbooks: positioning maps, capability audits, likely strategic moves for major players, and disruption pathways for challengers.
-
Commercialization and channel execution: go‑to‑market frameworks, seed production and certification checklists, and distributor economics to accelerate adoption while preserving margins.
-
Regulatory tracker and impact assessment: a forward‑looking register of policies, insurance provisions, and approvals that materially affect commercialization timelines and investment risk.
-
Supply chain resilience diagnostics: supplier dependency matrices, inventory and logistics stress tests, and mitigation playbooks for critical inputs and multiplication capacity.
-
M&A and partnership screening toolkit: investment criteria, valuation sensitivities, and sample diligence questionnaires focused on seed genetics, germplasm quality, and multiplication pipelines.
-
Actionable KPI dashboards and a set of customizable decision models (pricing simulations, ROI calculators, and adoption‑rate scenarios) that executives can apply to 2026 budget planning.
Strategic implications & recommended 2026 actions
-
For multinational breeders: accelerate narrow‑win hybrid launch programs in regions where insurance and supply economics support parent seed scale, while protecting margin through integrated treatment and service bundles.
-
For regional specialists: double down on localized adaptation, farmer field trials, and distributor loyalty programs — differentiation will drive premium placement even as multinationals expand.
-
For investors: prioritize assets that control upstream multiplication and certification pathways or that offer clear escalation potential through licensing and scale efficiencies.
-
For distributors and cooperatives: negotiate flexible supply agreements, promote bundled agronomy services, and use demonstration acres to accelerate new‑variety adoption where agronomic lift is proven.
-
For policy and risk teams: factor in the changed insurance landscape for hybrid parent seed production when modeling production risk, and monitor biotech approvals that could open or close commercial corridors.
Methodology, limitations and the teaser
PW Consulting’s conclusions draw on proprietary surveys, grower and distributor interviews, company financials, regulatory filings, and a synthesis of public‑domain intelligence through early 2026. We provide robust aggregate market sizing and scenario models to inform strategic choices. In this preview we intentionally refrain from publishing the granular segmentation breakdowns (regional and application splits, varietal revenue shares, and certain unit‑price matrices) — these detailed tables and interactive annexes are part of the full report available on our website. This “teaser” approach demonstrates analytical rigor while preserving the granular intelligence that operational teams require to act with confidence.
Final perspective
The wheat seeds market in 2026 sits at a deliberate inflection: steady topline expansion at the aggregate level masks pockets of rapid change driven by hybrid launches, regulatory adjustments, and targeted commercialization plays by major players. Market concentration metrics indicate that while the largest firms exert influence, there remains meaningful room for regional champions and specialty innovators. For executives making 2026 resource decisions, the path to outsized returns runs through precise execution on seed production economics, timely regulatory navigation, and channel‑led adoption strategies. PW Consulting’s full Wheat Seeds Market report equips decision‑makers with the practical tools, scenario models, and competitive diagnostics needed to convert that strategic opportunity into deliverable outcomes.
To access the complete dataset, segmentation tables, and the actionable annexes referenced above, please consult the full PW Consulting Wheat Seeds Market report on our website — the granular intelligence you need to operationalize your 2026 plans is available there.
For detailed analysis of this topic, please visit the official page: Wheat Seeds Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com