

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Turbo Expander Market to Hit USD 530M by 2032 at 5.5% CAGR

Turbo Expander Market — Strategic Briefing for 2026 Decision-Makers
As companies set capital and operational priorities for 2026, turbo expanders are moving from niche engineering choices to strategic levers for energy efficiency, carbon management, and value recovery across gas value chains. This briefing summarizes the strategic implications of PW Consulting’s latest Turbo Expander Market study and explains how senior executives, investors, and engineers should use the research to sharpen 2026 decisions. The piece is intentionally high-level — it demonstrates the report’s analytic depth while preserving proprietary segment-level figures and models that are available in full through the report portal.
Turbo Expander Market
Market snapshot: scale, trajectory, and concentration
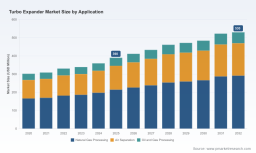
The global turbo expander market reached a meaningful commercial scale by our 2025 base year, with total market revenues near USD 390 million. Our forecast model — reflecting technology adoption patterns, LNG chain investments, decarbonization mandates, and efficiency-driven retrofits — projects a compound annual growth rate of roughly 5.5% over the 2026–2032 horizon, driving the market toward the mid‑hundreds of millions of dollars by 2032. Market dynamics are neither fully fragmented nor monopolistic: the top three suppliers account for less than half of market revenues (CR3 ≈ 45%), while the top five capture roughly two thirds (CR5 ≈ 69%). This structure creates both supplier choice and the need for careful vendor risk management when negotiating long-life equipment contracts.
Turbo Expander Market
Why turbo expanders become a strategic priority in 2026
-
Energy efficiency and emissions compliance are converging. Multiple regulatory drivers — from India’s energy efficiency programs to EU decarbonization targets and international industrial efficiency commitments — are increasing the value of energy-recovery technologies. Turbo expanders are often the highest-return option where pressure energy and cryogenic performance can be harvested; their deployment can materially improve site‑level energy intensity and reduce emissions footprints.
Turbo Expander Market -
LNG and cryogenic process growth sustains core demand. Continued expansion in liquefied natural gas infrastructure, allied petrochemical feedstock flows, and industrial gas production underpins steady adoption of turbo expanders in liquefaction, ORC (organic Rankine cycle) energy recovery, and cold-box optimization. Industry forecasts point to moderate upstream growth in gas flows that support new liquefaction and gas-processing CAPEX.
-
Commercial models shift from pure CAPEX buying to hybrid OPEX outcomes. As developers and midstream operators face tighter budgets and decarbonization targets, procurement strategies increasingly favour performance-based contracts, energy-share agreements, and retrofit-as-a-service models for turboexpanders. These contracting trends change vendor selection criteria and project finance structures.
-
Material and supply-chain volatility increases technical risk. Turboexpanders rely on specialty alloys and precision manufacturing. Global steel and high-performance alloy markets remain exposed to commodity cycles and capacity concentration, creating procurement lead‑time risk and a premium on supply-chain resilience.
Competitive landscape — who to watch and what to benchmark
The competitive set mixes diversified industrial incumbents, specialized turbomachinery houses, and agile start-ups. Leading OEMs — from multinational industrial groups to niche cryogenic specialists — compete on reliability, service footprint, and the ability to sell lifecycle energy-performance guarantees.
-
Atlas Copco (Stockholm) has broadened capabilities through recent acquisitions to bundle compression and energy-efficiency offerings; it is positioning turboexpanders within integrated gas-processing solutions.
-
Cryostar (Hésingue) continues to scale installations in high-growth markets and recently marked a major milestone with its 1000th turbo-expander/compressor installation in China (Nov 2025), cementing field experience and aftermarket revenue potential.
-
Large energy players and turbomachinery specialists — Baker Hughes, Siemens Energy, and MAN Energy Solutions — emphasize turnkey LNG and industrial gas solutions where expanders are components of broader skids and plant contracts.
-
Mid-sized and niche firms — including Chart Industries’ L.A. Turbine, Elliott Group, Nikkiso ACD, and Turboden — compete on application optimization (cryogenic, geothermal, hydrocarbon recovery) and targeted aftermarket services.
-
Innovative entrants and scale-ups such as Sapphire Technologies have drawn strategic funding (notably a Series C round in 2025 involving industry investors) and highlight how venture-backed models are introducing new in-line and radial solutions focused on compactness and cost-efficiency.
Recent product and commercial moves — Atlas Copco’s acquisitions to expand offerings (Jan 2025), Sapphire’s funding (Sep 2025), Cryostar’s installation milestone (Nov 2025), and several field commissions and commercial partnerships in North America — illustrate two dynamics: incumbents consolidating capabilities and new entrants accelerating specific niche innovations. For procurement teams, this means evaluating both the depth of an OEM’s installed base and the flexibility of their commercial terms.
What the PW Consulting report provides — operational, decision-grade deliverables
The full Turbo Expander Market study is designed for executives who need to convert market intelligence into executable actions across procurement, engineering, corporate strategy, and investment committees. Key deliverables include:
-
Proprietary demand model: scenario-based forecasts across the 2026–2032 horizon that align LNG, industrial gas, and power-recovery adoption with macro and regulatory pathways.
-
Vendor matrix and due‑diligence checklist: comparative assessments of OEMs by capability, installed base, warranty structures, aftermarket coverage, and financial-strength indicators.
-
Procurement playbook: contracting templates and negotiation levers tailored to CAPEX purchase, performance-contract, and retrofit-as-a-service approaches, including sample pricing sensitivities and risk allocation profiles.
-
ROI and lifecycle cost frameworks: engineering-backed TCO models that quantify energy recovery, CO2 abatement value, maintenance schedules, and payback windows under different gas-price and policy scenarios.
-
Technology roadmap and upgrade paths: practical guidance on selecting radial vs axial architectures, materials considerations, and retrofit options that maximize energy capture while controlling maintenance intensity.
-
Regulatory and policy impact analysis: how energy-efficiency regulations and carbon frameworks affect project economics and investment prioritization in target markets.
To preserve commercial value for clients, the report previews high-level segmentation and concentration trends but reserves segment-by-region and application-level figures (and the detailed company-share tables) for subscribers and licensees. This structure supports rapid executive alignment while ensuring access to the granular analytics needed for bid teams and technical due diligence.
How to use the research to make better 2026 decisions
-
Align capital approvals with regulatory timelines. Use the report’s scenario outputs to prioritize projects whose installation windows coincide with tightening efficiency mandates or favourable incentives, thereby improving IRR and de-risking approval cycles.
-
Prioritize retrofit opportunities with short paybacks. Our lifecycle models identify plant configurations where retrofitting turbo expanders yields immediate operational savings and reduces carbon intensity within a 3–5 year horizon under conservative fuel-price assumptions.
-
Structure procurement to balance lead-time risk and service coverage. Given supply-chain exposure to alloy markets and long manufacturing lead times, locking in spares and service agreements with performance SLAs can be as important as initial equipment price.
-
Evaluate partners by installed-base evidence rather than only specification claims. Field-proven reliability, commissioning records, and service footprint materially affect lifecycle costs and availability in high-utilization plants.
-
Consider blended commercial models for ownership, particularly for midstream and municipal operators: energy share agreements or third-party financed retrofits can preserve capital while capturing efficiency upside.
Risk factors and downside scenarios to monitor
-
Commodity and alloy-price shocks that extend delivery lead times and drive contingency costs.
-
Slower-than-expected LNG capacity additions or a shift to alternative fuels in key markets that depress near-term demand for new expanders.
-
Technological substitution: marginal gains from alternative energy-recovery technologies or proprietary in-house solutions developed by large integrators.
-
Consolidation among suppliers that changes bargaining dynamics and aftermarket pricing.
Conclusion — the 2026 strategic imperative
For 2026, turbo expanders represent a convergent opportunity: a mature technology with renewed commercial importance because of efficiency regulations, LNG and cryogenic expansion, and evolving commercial models that monetize energy recovery. The market’s steady growth trajectory (≈5.5% CAGR) and the mid‑tier concentration among suppliers create an environment where disciplined procurement, supplier due diligence, and scenario-based investment planning can produce significant operational and climate benefits.
PW Consulting’s Turbo Expander Market study distils these dynamics into decision-grade tools: scenario forecasts, ROI frameworks, vendor matrices, and procurement playbooks crafted for capital allocators and technical teams. The executive summary and high-level findings in this briefing are intended to orient 2026 strategy; the full report contains the segment-level analytics, supplier shares, and downloadable models that operational teams use to run bids, structure contracts, and finalize CAPEX approvals.
To access the complete dataset, granular segmentation, and proprietary models that underpin the recommendations summarized here, visit our report page. The detailed numbers and downloadable tools are available to subscribers and corporate licensees to support procurement events, investment memos, and engineering specifications for 2026 execution.
For detailed analysis of this topic, please visit the official page: Turbo Expander Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com