

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Sport Bottle Market to Reach USD 4,890M by 2032 with 3.4% CAGR

Sport Bottle Market — Strategic Outlook for 2026 Decision-Making
As PW Consulting’s lead industry analyst, I present an executive introduction to our new Sport Bottle Market study. Built on a rigorous base year of 2025 with historical observation across 2020–2025 and forward-looking scenarios through 2032, this research turns market statistics into concrete choices for management teams planning budgets, product roadmaps, and M&A activity in 2026. At the headline level, the global sport bottle market has expanded steadily since 2020 and, under our central case, is projected to grow at a compound annual growth rate (CAGR) of 3.4% across the 2026–2032 forecast window. The report quantifies the market trajectory from the pandemic-era recovery years into a near-term environment defined by premiumization, regulatory pressure on plastics, and intensified OEM competition — all of which matter directly to 2026 capital allocation and commercial strategy.
Sport Bottle Market
Why this study matters for 2026 strategic choices
-
Timing: 2026 is a hinge year. Many producers have committed to recycled-content targets or face new EPR (extended producer responsibility) rules that shift cost and sourcing structures. Our study aligns market demand projections with policy timelines so teams know when headroom will tighten and where margin pressure will appear.
Sport Bottle Market -
Resource allocation: With growth steady but uneven across materials and channels, the right 2026 R&D and CapEx bets—insulation technologies, low-carbon stainless steel supply, certified recycled polymers—make the difference between market-entry cost and lasting advantage. The report maps these investment levers to demand scenarios.
Sport Bottle Market -
Competitive posture: The market remains fragmented at the top. Our concentration analysis shows that leading players do not yet control the majority of global revenue (CR3 and CR5 metrics indicate a market amenable to niche specialists, strong private-label players, and smart consolidators). That opens tactical opportunities for bolt-on acquisitions, co-manufacturing, and white-label strategies in 2026.
-
Channel and go-to-market: The shift toward D2C and brand-led storytelling for premium bottles alters margin pools. Retail, subscription, and B2B promotional channels each require distinct SKUs and logistics; our playbooks translate demand curves into go-to-market sequencings for 2026 launches.
Market trajectory and what the numbers imply
Quantitatively, the market’s recovery from 2020 into 2025 shows resilience driven by renewed outdoor activity, fitness adoption, and premium thermal solutions. Our base-year benchmarking (2025) anchors scenario planning: under the central projection, the market continues to grow gradually through 2032 with some volatility tied to raw-material cycles and regulatory implementation. This pace of expansion favors companies that can optimize unit economics and defend premium price points rather than those banking purely on volume. For 2026 specifically, expect moderate top-line opportunities across channels but acute margin sensitivity where recycled content mandates or import tariffs change input costs.
Key demand drivers and near-term inflection points
-
Premiumization and performance: Insulated stainless steel and high-performance closures are driving price realization, especially in active-lifestyle segments. Brands that can credibly deliver heat/cold retention and durable finishes capture the top-end consumer.
-
Sustainability and regulation: New rules in major jurisdictions (notably U.S. state-level recycled-content mandates and evolving EU directives) are forcing reformulations of plastic product lines and supply-chain audits. Companies that pre-emptively secure certified recycled feedstock and redesign for recyclability will avoid 2026 compliance shocks.
-
Customization and brand partnerships: Event-driven demand (sports events, marathons, corporate wellness programs) creates windows for limited-run, co-branded units. OEM/ODM agility is a competitive advantage for 2026 promotional cycles.
-
Channel fragmentation: Retail vs. e-commerce vs. institutional procurement each require unique SKU strategies and inventory models. Firms that differentiate packaging and pricing models by channel will protect margins as unit growth moderates.
Competitive landscape — who to watch in 2026
The sector includes a mixture of global consumer brands, outdoor-specialist manufacturers, and high-volume OEMs. Established global brand players leverage design and premium positioning, while numerous Asia-based manufacturers compete on customization and cost efficiency. Several dynamics are relevant for 2026 planning:
-
Brand leaders with premium insulation systems continue to invest in product differentiation and direct channels; their challenge is balancing scale with authenticity in the outdoors and fitness communities.
-
OEM/ODM suppliers in Asia are consolidating capabilities around custom finishes, rapid tooling, and private-label fulfillment; they are logical partners for brands looking to accelerate time-to-market without heavy CapEx.
-
Smaller B Corp and sustainability-first brands are expanding into sport lids and hybrid materials, appealing strongly to conscious consumers; they can be attractive M&A targets for incumbents seeking green credentials.
Our company dossier includes strategic profiles and capability assessments for core industry participants, highlighting technology focus, go-to-market strength, and partnership openness. Examples include aluminum-bottle specialists that target event and consumer branding, outdoor-hydration incumbents focusing on insulated systems, and large private-label manufacturers driving promotional channels. Recent product updates from multiple manufacturers (early 2026 lid redesigns and expanded insulated catalogs) underline that the innovation cadence remains high and should inform product roadmap prioritization in 2026.
Regulatory and supply-side risks
From a regulatory perspective, 2026 is when several policy levers hit manufacturing operations. Jurisdictions are implementing recycled-content mandates and EPR frameworks for single-use and packaged goods, and consultations on directive adjustments are active. Materially, this changes input sourcing strategies: firms must certify recycled resin supply, invest in compatible molding technologies, or face compliance costs. On the supply side, stainless steel and specialty polymers continue to exhibit cyclical pricing; firms with hedging strategies, diversified supplier bases, or backward-integration options will gain an advantage in 2026 budgeting.
What the report delivers — practical, transaction-ready intelligence
-
Market-sizing and scenario model: Detailed historical (2020–2025) and forecast (2026–2032) revenue trajectories with sensitivity cases tied to policy and raw-material shocks.
-
Competitive benchmarking: Capability heatmaps for leading brands and suppliers, including product portfolios, channel coverage, and IP or design strengths—structured to support vendor selection and M&A screening.
-
Regulatory impact matrix: Jurisdiction-by-jurisdiction compliance roadmaps and timing, aligned to product-design responses and cost-estimation templates for 2026 planning cycles.
-
Go-to-market playbooks: SKU rationalization frameworks, retail vs. D2C margin simulations, and promotional calendar strategies calibrated for event-driven sales windows.
-
Supply-chain and cost modeling: Inputs to support procurement, sourcing, and nearshoring decisions, plus capital allocation guidance for tooling and certification investments.
-
Actionable M&A and partnership targets: A screened list of acquisition candidates and contract-manufacturing partners aligned to growth and sustainability objectives, ranked by strategic fit and integration complexity.
Recommended 2026 playbook — five priorities for executives
-
Prioritize recycled-content sourcing now: Secure certified recycled polymer or negotiate long-term offtakes for recycled materials before mandates expand. This reduces 2026 compliance exposure and stabilizes input pricing.
-
Segment SKUs by channel: Rationalize SKUs across retail, D2C, and B2B to optimize inventory turns. Reserve premium insulated SKUs for direct channels where brand messaging captures margin.
-
Invest in modular lids and thermal innovation: Small improvements in lid ergonomics and thermal performance drive disproportionately higher willingness to pay. Prioritize low-cost, high-perceived-value upgrades in 2026 product launches.
-
Explore bolt-on acquisitions for sustainability credentials: Target smaller B Corp manufacturers with credible recycled-material processes to accelerate compliance and brand positioning without starting from zero.
-
Build flexible manufacturing partnerships: Use a mix of regional OEMs and in-house production to manage tariff and logistics risks; prioritize partners with rapid tooling and private-label capabilities for event-led demand.
How to use this research in 2026
Executives should treat the report as an operational bridge between high-level market forecasts and execution. Use our scenario outputs to stress-test revenue targets and to size potential acquisition paybacks. Apply the regulatory roadmaps to your product requalification timelines, and implement the go-to-market playbooks during 2026 planning cycles to capture seasonal and event opportunities. For corporate development teams, our screened target set and competitive assessments are ready for immediate outreach and diligence prioritization.
What we intentionally withhold here — and why
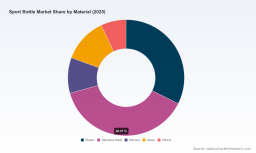
Consistent with the “trailer” principle, this introduction demonstrates the report’s strategic depth while withholding granular segmentation tables and proprietary split data that are critical to execution. The full study contains detailed regional and application breakdowns, per-material revenue shares, and SKU-level margin models that corporate teams use directly in financial planning and deal valuation. Those datasets and interactive models are available in the complete report and online dashboard for subscribers.
For teams preparing budgets and decisions in 2026, the high-level conclusion is clear: steady market expansion combined with intensifying sustainability requirements and product premiumization means that the next 12 months are about execution—locking material supply, launching high-margin SKUs, and selectively consolidating capabilities. PW Consulting’s full Sport Bottle Market study provides the granular inputs and decision-support tools you need to act with conviction.
For detailed analysis of this topic, please visit the official page: Sport Bottle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com