

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Ski Apparel Market at USD 2,549.4M in 2025, poised for 5.51% CAGR

Ski Apparel Market: Strategic Outlook for 2026 — An Executive Trailer from PW Consulting
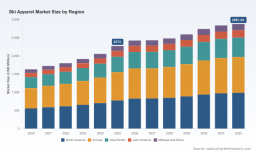
As organizations finalize 2026 budgets and strategic roadmaps, we present a concise, decision-grade orientation to the global ski apparel market based on PW Consulting’s 2025 base-year study. The market is in a healthy expansion phase: our analysis uses 2025 as the reference point (market size USD 2,549.4 Million) and projects growth at a compounded annual rate of 5.51% through the 2026–2032 forecast window, reaching an estimated USD 3,709.8 Million by 2032. These macro dynamics create both near-term operational pressures and multi-year strategic opportunities. This preview highlights the signal-level implications senior executives should consider now — the full report contains the granular segmentation, scenarios, and proprietary models that operational teams will need to execute.
Ski Apparel Market
Why this study matters for 2026 decision cycles
- Resource prioritization: With mid-single-digit CAGR and accelerating premiumization, the capital allocation question shifts from “if” to “where” — product innovation, channel expansion, or margin protection.
- Procurement and cost pass-through: Tariff volatility and concentrated raw-material supply require explicit sourcing contingency plans in 2026 procurement rounds.
- Portfolio strategy: Decisions about expanding technical, insulated, or sustainability-led lines should be anchored in demand elasticity and margin maps provided in the full study.
- M&A and partnership timing: The market concentration metrics indicate space for targeted consolidation and capability buys — the timing and targets for bolt-on acquisitions are a 2026 priority.
- Commercial model shifts: Direct-to-consumer, experiential retail, and circular-economy services (rental/resale) will be pivotal levers to defend and grow share.
Key market dynamics shaping 2026 strategy
- Measured expansion with premium tailwinds — The market’s trajectory reflects steady consumer participation, premiumization of technical apparel, and higher ASPs in performance categories. Companies should expect headline growth but divergent performance across product and channel choices.
- Tariff and trade-policy volatility — Recent policy moves have introduced measurable import cost pressures. Industry reporting indicates tariffs that have already driven 5–20% retail price increases on some ski gear categories. Specific tariff schedules targeting apparel and related HS codes are in force across major trading blocs, and a U.S. Supreme Court opinion issued in February 2026 has introduced new legal considerations around tariffs, refunds, and future rate exposure. These changes mandate active trade-compliance and pricing-scenario planning for 2026.
- Supply-chain stratification — Lead suppliers for technical membranes, insulation, and performance fabrics remain geographically concentrated. Expect procurement windows to be shorter and premium freight or near-shoring investments to become competitive differentiators.
- Sustainability as a commercial axis — Recycled textiles, traceability, and end-of-life programs are no longer reputation-only initiatives; they materially affect retail placement and margin capture, particularly in premium and outdoor-specialist channels.
- Channel and experience innovation — Consumers increasingly evaluate ski apparel within broader outdoor lifestyles. Retail strategies blending experiential resortside retail, online configurators, and rental/resale ecosystems will outperform legacy wholesale-dependent models.
- Market structure — Competitive concentration signals meaningful market power among top players. This influences pricing dynamics, distribution access, and the attractiveness of scale-seeking transactions.
Competitive landscape — strategic takeaways on marquee players
- Helly Hansen (Norway): Positioned as a premium technical brand with strong resort and freeride credentials. Strategic advantage: deep product systems and distribution in alpine channels. For competitors: neutralize through differentiated technical claims, strategic retail partnerships, or targeted value propositions to non-resort consumers.
- Arc’teryx (Canada): A high-performance, design-led leader with a reputation for advanced fabrics and minimalist aesthetics. Strategic implication: Arc’teryx sets a high bar on product performance and pricing — rivals must choose between matching R&D intensity or focusing on accessibility and breadth.
- Black Diamond Equipment (USA): Specialist alpine technical apparel aimed at technical mountain users. Their strength is technical authenticity and channel credibility among adventure consumers. Market players seeking to enter the technical alpine niche should consider product certification and athlete partnerships to accelerate credibility.
- Columbia Sportswear Company (USA): Broad-reach outdoor player that competes on value and distribution scale. Columbia’s strength is breadth across categories and channels; premium-focused competitors should guard against erosion at scale via targeted premiumization and loyalty strategies.
- Patagonia Inc. (USA): Sustainability-first product strategies and strong brand equity. Competitive guidance: sustainability credentials now translate into commercial advantage in specific consumer segments — investing in traceability and recycled content can both unlock retail placement and justify premium pricing.
What the full PW Consulting report delivers (practical preview)
- Macro sizing and validated forecasts (2020–2032) with sensitivity ranges tied to participation rates, ASPs, and geopolitical scenarios.
- Competitive benchmarking and strategic positioning maps for leading and emerging brands, including capability heatmaps and retail-distribution diagnostics.
- Tariff and trade-impact modeling with scenario-based P&L effects at different sourcing mixes — designed for procurement and CFO playbooks.
- Product portfolio decision matrices balancing margin, investment intensity, and time-to-market for core categories and adjacencies.
- Go-to-market playbooks for DTC scaling, wholesale optimization, and experiential/resort retail concepts — including pilot KPIs and resource templates.
- Sustainability ROI models assessing cost, pricing, and channel benefits of recycled content, take-back programs, and certification routes.
- M&A screening methodology and an anonymized shortlist logic for bolt-on targets that deliver distribution, technology, or supply control.
- Operational checklists: sourcing contingency planning, inventory hedging templates, and trade-compliance playbooks tailored to apparel HS codes.
Priority actions PW Consulting recommends for 2026
- Lock in multi-supplier agreements for critical fabrics and insulation with escrowed pricing windows. Capacity purchases and staggered delivery schedules reduce exposure to tariff-driven price spikes.
- Run a three-scenario tariff simulation for FY26 P&L (base, elevated, and contested) and embed triggers for price increases, promotional cadence, or temporary margin protection measures.
- Prioritize capital for high-return areas: product platforms with modularity (layered systems), advanced fabrics that allow premiumization, and digital services that extend lifetime value (repair, resale, rental).
- Accelerate DTC investments in consumer data capture and personalization, paired with selective experiential retail pilots at resorts to defend premium segments.
- Establish a sustainability sprint for FY26: quantify incremental cost vs. price premium and secure supplier commitments for recycled inputs to avoid late-cycle margin shocks.
- Define an M&A scorecard tied to distribution reach, proprietary tech, and supply control; prioritize small, accretive deals that close gaps without overstretching integration capacity.
How to use this research in your 2026 boardroom discussion
- Use the report’s tariff and scenario modules to stress-test FY26 budgets and to set automated pricing escalation triggers.
- Convert the product decision matrices into quarterly roadmaps with milestone-based go/no-go gates tied to customer feedback loops.
- Adopt the procurement playbook to structure volume commitments and to document fallbacks if key suppliers or routes become constrained.
- Set two quantitative board KPIs for 2026: a margin-protection indicator (tariff-adjusted gross margin) and a revenue-mix indicator (percent of sales from premium technical/sustainable lines and DTC channels).
- Use the M&A screening methodology to populate a watchlist for immediate diligence — having pre-cleared targets shortens decision cycles in volatile markets.
PW Consulting’s full Ski Apparel Market report contains the segment-level granularity, regional demand matrices, and proprietary supply-chain models that translate this strategic preview into operational plans. If you are crafting FY26 strategy, procurement commitments, or an M&A agenda, the full study provides the data and templates to move from intent to execution. Contact PW Consulting for a tailored briefing and access to the complete dataset and scenario tools.
Ski Apparel Market
For detailed analysis of this topic, please visit the official page: Ski Apparel Market
Ski Apparel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com