

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Reprocessed Medical Device Market to Grow at 16.98% CAGR (2026–2032)

Reprocessed Medical Device Market 2026: Strategic Primer for Executive Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused introduction to our new market study on the Reprocessed Medical Device market. This primer explains why the market will be a boardroom priority in 2026, highlights the strategic levers that matter for commercial and M&A plays, and summarizes the practical, decision-ready deliverables contained in the full report. Consider this a well-stocked trailer: it demonstrates the analytical depth and actionable orientation of our work while reserving the full segment-level intelligence for the detailed subscription report.
Reprocessed Medical Device Market
Executive snapshot: scale, rhythm and strategic urgency
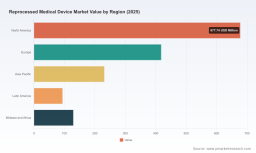
The reprocessed medical device market has moved from niche to mainstream. Our base-year (2025) assessment pegs the market at approximately USD 1.55 billion, reflecting steady growth from 2020. From 2026 through 2032 we project a compound annual growth rate (CAGR) of 16.98%, producing a multi-year expansion that more than doubles market size by the early 2030s under the central scenario. For leaders planning 3–5 year roadmaps, that pace creates windows for rapid share capture, consolidation plays, and differentiated service models focused on sustainability and total cost of care.
Reprocessed Medical Device Market
Why 2026 is a watershed year
- Regulatory inflection points: Several jurisdictions have clarified or liberalized rules around commercial reprocessing and hospital-as-manufacturer responsibilities. This reduces legal ambiguity for scaled operators, while increasing compliance burdens for newcomers. Regulatory clarity is morphing into a competitive moat.
- Payer and procurement alignment: Reimbursement parity—when applied—removes an historic obstacle to adoption. With policy updates and growing sustainability commitments among hospital systems, procurement teams are now evaluating reprocessed alternatives through a total-cost-and-risk lens rather than price-per-unit alone.
- Value redefinition: Buyers increasingly value lifecycle environmental impact and supply-chain resilience. Reprocessing solutions that couple validated clinical performance with logistics and service guarantees are being evaluated as enterprise-grade procurement categories, not ancillary services.
Core market dynamics and what to watch
- Acceleration driven by clinical validation and clearances: The market’s credibility hinges on device-specific validations and regulatory clearances. Operators that invest in repeatable, auditable validation protocols reduce adoption friction with hospital sterile-processing and clinical governance teams.
- Fragmented competitive structure, strategic implications: Market concentration remains relatively low; the top few players collectively account for under a third of market revenue. This fragmentation signals active greenfield opportunity for entrants, but also presents a near-term M&A playbook: targeted tuck-ins and platform buys can rapidly increase scale without the protracted cycle of developing clearances in-house.
- Commercial reprocessing vs. in-house models: Hospitals face a build-versus-buy choice. Commercial reprocessors can offer faster breadth of device coverage and outsourced liability management, while in-house programs trade off higher up-front investment for margin capture. Both tracks require disciplined quality systems to meet 510(k)/manufacturer obligations where applicable.
- Cost-to-serve and operating model leverage: While per-instrument reprocessing labor and consumable costs are modest, unit economics improve significantly at scale and with efficient packaging and logistics (e.g., closed-loop programs). Service fees, pay-for-performance warranties, and donor-incentive programs are emerging levers to optimize margins and expand addressable supply.
Competitive landscape: positioning and strategic moves
The competitive field blends specialized reprocessors, sustainability arms of medtech incumbents, and regional players. Our report contains deep profiles and strategy assessments for the major participants; below is a high-level synthesis of the strategic archetypes you will find:
Reprocessed Medical Device Market
- Specialist innovators (e.g., Innovative Health): These players focus on device-specific engineering for high-value niches such as electrophysiology and cardiology. Their competitive advantage is rapid clearance acquisition and deep clinical validation. Recent regulatory wins have created durable product portfolios that are difficult for generalists to replicate on short timelines.
- Operationally led reprocessors (e.g., SureTek Medical): Companies that build differentiated logistics (closed-loop systems, paid-donor programs) capture value through supply-chain integration—particularly attractive to ambulatory surgery centers and specialty clinics.
- Incumbent medtech sustainability divisions (e.g., Stryker, Medtronic, Cardinal Health, STERIS): These organizations leverage existing customer relationships, distribution infrastructure, and broad product portfolios to scale reprocessed offerings. Their challenge is reconciling legacy sales incentives with a circular-economy business model.
- Regional specialists (e.g., NEScientific, ReNu Medical, Vanguard AG): Focused on local regulatory environments and hospital networks, regional players can move quickly on partnerships and institutional contracts where global players are constrained by process complexity.
Strategic developments we monitor include high-impact regulatory clearances, cross-sector partnerships to integrate reprocessing into sterile processing workflows, and national policy moves that legalize or institutionalize reprocessing—each of which materially reshapes adoption curves and competitive advantage.
Risks, barriers and mitigation strategies
- Regulatory and compliance risk: Reprocessing is device-specific; inadequate validation or documentation can expose operators to enforcement and liability. Mitigation requires robust quality systems, a clear regulatory playbook, and targeted technical investments early in product development.
- Clinical acceptance and perception: Uptake is influenced by clinician trust. Clinical evidence and end-user experience programs are essential to overcome initial resistance—particularly for devices used in high-acuity settings.
- Supply-chain volatility: Reprocessed solutions are sensitive to donor-supply flows. Closed-loop partnerships and procurement incentives help stabilize feedstock and lock in long-term contracts.
- Commercial reimbursement uncertainty: While reimbursement parity exists in some channels, coding and billing practices vary. A proactive payer-engagement and billing-infrastructure plan is required to avoid margin leakage.
What the PW Consulting report delivers (practical, decision-ready modules)
Our full market study is built for executives who need actionable intelligence to set 2026 strategies. Key deliverables include:
- Market-sizing and demand models: historical (2020–2025) and scenario-based forecasts (2026–2032) with sensitivity to regulatory, reimbursement, and supply constraints.
- Competitive benchmarking: feature-by-feature comparison of business models, clearance portfolios, service offerings, and go-to-market coverage for primary players.
- Regulatory and reimbursement matrix: jurisdictional summaries, clearance pathways, compliance checklists, and payer engagement strategies tailored for commercial teams.
- Operational playbooks: standard operating procedures for validation, cleaning, functional testing, and sterile processing integration—designed to accelerate time-to-market for new device clearances.
- Commercial pilots and contract templates: sample closed-loop agreements, donor-incentive mechanics, KPIs for sterile processing managers, and pricing templates to protect margin while supporting adoption.
- M&A and partnership screeners: target scoring, integration risk assessments, and near-term bolt-on opportunities that can increase share quickly in a fragmented market.
- Executive dashboards and TCO calculators: tools that quantify total cost of ownership, environmental impact metrics, and reimbursement upside to support procurement conversations.
Actionable recommendations for 2026 planning cycles
- Prioritize regulatory-first investments: For firms seeking scale, invest early in device-specific validation and quality documentation. Regulatory clearances create durable differentiation and shorten sales cycles.
- Design programs around closed-loop supply: Closed-loop logistics and donor-incentive programs stabilize feedstock and create sticky relationships with buying institutions.
- Bundle clinical and operational guarantees: Beyond unit price, buyers value service-level agreements, clinical metrics, and risk-sharing arrangements. Structure offers as integrated risk-transfer propositions.
- Pursue selective consolidation: Given a fragmented market profile, disciplined M&A targeting capability gaps (clearance engineering, logistics, or geographic reach) can be accretive faster than organic development.
- Invest in payer and procurement engagement: Build capabilities in coding, billing, and procurement evidence generation to capture incremental reimbursement and accelerate adoption within hospital systems.
Final note — the intelligence you’ll need to act
The macro trajectory and strategic forces are clear: rapid growth, regulatory standardization, and shifting buyer priorities create a compelling commercial opportunity in 2026 and beyond. Our full report contains the granular, segment-level analytics, company scorecards, and implementation tools that translate this opportunity into executable plans. Use this primer to align internal stakeholders and to prioritize the modules you’ll request from our advisory team.
To unlock the detailed segmentation, regional and application-level forecasts, company-level revenue estimates, and the complete set of decision tools referenced here, visit the PW Consulting Reprocessed Medical Device Market page and request the full report. Our team stands ready to convert the intelligence into a tailored go-to-market roadmap or M&A diligence package aligned to your strategic objectives.
For detailed analysis of this topic, please visit the official page: Reprocessed Medical Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com