

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Artificial Blood Vessel Market: USD 2.38B in 2025, 5.38% CAGR to 2032 | PW Consulting

Artificial Blood Vessel Market: Strategic Imperatives for 2026 Decision-Makers
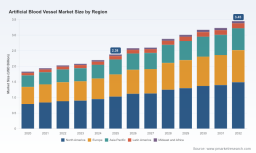
As PW Consulting's lead industry analyst, I present a strategic primer on our latest Artificial Blood Vessel Market study — designed to turn market complexity into decisive action in 2026. The sector is no longer a niche adjunct to vascular surgery; it is a distinct, investible market with sustained expansion. Our research (base year 2025; historical window 2020–2025; forecast 2026–2032) quantifies that trajectory and translates it into concrete strategic choices. The market expanded from USD 1.83 Billion in 2020 to USD 2.38 Billion in 2025 and is projected to continue growing at a compound annual growth rate (CAGR) of 5.38% through the 2026–2032 forecast horizon, reaching USD 3.45 Billion by 2032. These headline numbers matter — but the nuanced commercial levers behind them matter more.
Artificial Blood Vessel Market
Why this study matters for 2026 planning
-
Actionable foresight: 2026 is the year companies must move from product-centric roadmaps to value-capture strategies. The market is mature enough to reward capability differentiation (e.g., engineered acellular conduits, cryopreserved allografts, collagen-derived grafts, polymer prostheses) yet fluid enough that regulatory and reimbursement changes can rapidly reallocate value.
Artificial Blood Vessel Market -
Capital allocation calibration: With mid-single-digit CAGR, growth is predictable but not explosive. That profile demands disciplined CAPEX and targeted R&D investments rather than broad, undisciplined expansion.
Artificial Blood Vessel Market -
Commercial architecture: Distribution, hospital contracting, and reimbursement engagement will dominate execution success. Winning in 2026 requires an integrated playbook spanning clinical adoption, payer negotiation, and OR workflow integration.
Market dynamics that will define winners
-
Regulatory inflection points: The pathway to broad adoption is now paved by recent regulatory decisions that validate acellular tissue engineered vessels (ATEVs) as a clinical option for trauma and specific revascularization use-cases. Such approvals materially reduce clinical uncertainty and accelerate procurement conversations with hospital systems and defense purchasers.
-
Reimbursement evolution: New technology assessments and add-on payments are shifting the commercial calculus. Products that can be distinctly coded and justified on clinical and economic grounds will secure preferential hospital uptake. Expect payers and health systems to demand robust health economic evidence packages that demonstrate not only clinical efficacy but per-patient cost offsets in OR time, complication avoidance, and readmission reduction.
-
Clinical substitution vs. augmentation: Artificial conduits are increasingly positioned not only as substitutes for failed autologous approaches but as primary options in trauma and high-risk patient segments. The strategic implication: manufacturers should design messaging and trials around distinct clinical algorithms where their products outperform or materially simplify care pathways.
-
Supply-and-manufacturing constraints: Advanced biologic and engineered grafts impose different supply chain and quality-control demands than commodity polymer prostheses. Scalability and control of biologics manufacturing will be strategic assets for firms with premium products.
Competitive landscape: positioning and strategic moves
The market displays moderate concentration: the top three players account for roughly a third of market value, and the top five for under half. This structure creates room for focused challengers to displace incumbents if they can combine clinical differentiation with efficient commercialization.
-
Humacyte Global, Inc. — Humacyte has introduced an acellular tissue engineered vessel designed for extremity arterial injury when autologous vein is not feasible. Recent regulatory milestones and international filing plans indicate a clear commercialization timetable. For strategy teams, Humacyte exemplifies how a regulated biologic can move from innovation to system-level adoption when clinical indications are tightly defined and supported by defense and trauma designations.
-
Artivion, Inc. — With a portfolio focused on cryopreserved allografts for diverse vascular repairs, Artivion illustrates the value of legacy tissue-based solutions that address complex anatomic needs. Their strength is in established clinical acceptance for specific reconstructive procedures and in relationships with vascular surgery centers.
-
LeMaitre Vascular, Inc. — A specialty player with collagen-based graft solutions, LeMaitre is leveraging targeted commercialization and investor engagement to sustain growth. Firms like LeMaitre demonstrate the payoff from sharp clinical focus and sustained engagement with interventional and surgical communities.
-
B. Braun Melsungen AG — A large medtech incumbent with polyester vascular prostheses, B. Braun competes on scale, global distribution, and durable product families for aortic and peripheral reconstructive procedures. Incumbent advantages include breadth of product portfolio and deep hospital penetration.
-
Terumo Medical Corporation — Terumo’s emphasis on bioengineered grafts and surgical innovation positions it to capture opportunities where procedural workflow and device compatibility drive purchasing decisions. Their strategic playbook emphasizes integration with vascular surgery technologies.
Recent developments to watch (implications for 2026 tactics)
-
Regulatory approvals for engineered conduits have accelerated clinical acceptance — this compresses time-to-revenue for first movers and raises the bar for new entrants.
-
Targeted marketing authorization filings in new geographies reflect an increasingly globalized commercialization approach; companies should prioritize regulatory sequencing that aligns with reimbursement and procurement cycles in target markets.
-
Investor- and capital-market activity (e.g., investor conferences and financing events) is ramping up among mid-market specialists — an indicator that M&A and partnering windows are open for well-positioned targets.
What our report delivers — pragmatic, executable intelligence
PW Consulting’s full study is structured to convert market intelligence into executable playbooks. The report includes:
-
Granular TAM and SAM modeling across the 2020–2032 window, with scenario-based forecasts (baseline, conservative, and accelerated) that enable stress-testing of strategic assumptions.
-
An end-to-end commercialization framework: go-to-market archetypes, hospital procurement decision trees, OR adoption checklists, and clinician engagement plans.
-
Reimbursement and pricing playbook: evidence requirements for new technology assessments, negotiation levers for securing add-on payments, and payer messaging templates tailored to national and system-level purchasers.
-
Regulatory pathway mapping: comparative timelines and risk profiles for biologic, allograft, and polymer product classes across major jurisdictions.
-
Manufacturing and supply-chain advisories: scale-up templates for biologics, cost-to-serve analyses for cryopreserved products, and risk mitigation measures for raw-material volatility.
-
Competitor dossiers and M&A watchlist: strategic profiles of incumbent and challenger companies, plus criteria-based target screening for bolt-on acquisitions or strategic partnerships.
-
Commercial sensitivity testing: price elasticity, hospital reimbursement break-even models, and ROI calculators for hospital administrators and buying groups.
Note: the report contains the full segmentation datasets and proprietary unit economics models that underlie our forecasts. Those detailed tables and segment-level valuations are intentionally reserved to preserve the strategic novelty of this analysis — access to the source report provides the complete, downloadable intelligence required to execute.
Recommended 2026 playbook for industry participants
-
For innovators (ATEVs, engineered biologics): prioritize regulatory sequencing that aligns with high-value indications (e.g., trauma and emergency revascularization) and secure targeted reimbursement pathways before scaling production. Invest in real-world evidence (RWE) generation to shorten hospital adoption cycles.
-
For incumbent prosthetics and tissue firms: defend core hospital relationships by bundling products with clinical support services (e.g., OR training, graft-selection algorithms) and explore hybrid offerings that combine polymer durability with biologic surface treatments.
-
For investors and acquirers: target assets that reduce time-to-evidence (clinical registries, payer pilots) and technologies that de-risk manufacturing scale-up. Look for assets with clear clinical differentiation and defensible payer pathways.
-
For health systems and IDNs: adopt value-based procurement pilots that measure total cost of care, not only acquisition price, and partner with manufacturers on outcomes contracts for high-cost, high-impact indications.
Risks and contingency considerations
-
Reimbursement disappointment: if payers demand more robust long-term outcomes than anticipated, adoption could slow and force pricing concessions.
-
Manufacturing bottlenecks: biologics and cryopreserved products carry scale-up risk; companies without flexible capacity may face missed demand windows.
-
Clinical adoption lag: even with regulatory clearance, changing entrenched surgical practice requires persistent clinical advocacy and evidence generation.
Closing perspective: from market data to strategic advantage
By 2026, the Artificial Blood Vessel Market will reward disciplined strategy more than aggressive expansion. With a projected mid-single-digit CAGR and a steadily rising market value through 2032, leadership will come to those who synthesize regulatory timing, payer engagement, and operational readiness into a coherent execution plan. PW Consulting’s study provides the empirical backbone and the practical playbooks needed to transform that opportunity into shareholder value.
To access the full segmentation tables, proprietary TAM models, and the operational templates referenced in this primer, please consult the complete report on our website — the detailed intelligence there is tailored for boardrooms, investor decks, and commercialization teams ready to act in 2026.
For detailed analysis of this topic, please visit the official page: Artificial Blood Vessel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com