

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Isononyl Alcohol Market at USD 1,500M (2025), 5.55% CAGR Outlook

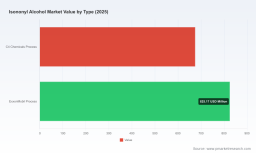
Isononyl Alcohol Market — 2026 Strategic Outlook and Why This Study Matters for Corporate Decision-Making
Introduction: a focused intelligence product for 2026 choices
As PW Consulting’s chief industry analyst, I present a succinct but forward-looking orientation to our latest Isononyl Alcohol (INA) market study. This briefing is designed as a high-value “trailer”: it demonstrates the analytical depth and operational utility of the full report so senior executives, commercial leaders and investment committees understand why the underlying intelligence is mission-critical for decisions in 2026 — while intentionally withholding the detailed segment tables and proprietary model outputs that drive those decisions. If you manage supply chains, capital allocation, product portfolios or regulatory risk linked to plasticizers, surfactants, lubricants or specialty esters, the research behind this note should be read before you finalize budgetary or strategic moves this year.
Isononyl Alcohol Market
Market snapshot and trajectory
Using 2025 as the base year, the global Isononyl Alcohol market is a mature, growing specialty-chemical sector. After an incremental expansion through 2020–2025, the market reached a notable milestone in 2025, and our forecast model projects a compound annual growth rate (CAGR) of approximately 5.55% across the 2026–2032 horizon. Under the baseline scenario this implies meaningful aggregate expansion by the end of the forecast window.
Isononyl Alcohol Market
Two structural dynamics underpin this trajectory. First, end-market demand continues to be driven by established applications (plasticizers, surfactants, lubricants and specialty esters) where product quality, regulatory compliance and cost competitiveness determine supplier selection. Second, supply-side developments — including large-scale licensed plants, sustainability certifications and process technology differentiation — are re-shaping regional balances of power and price elasticity. Market concentration is material: the top three and top five supplier groups account for a majority share of global supply, a fact that has direct consequences for bargaining power, margin capture and the pace of innovation.
Isononyl Alcohol Market
Why this study is strategically valuable in 2026
- Actionable forecasting tied to commercial choices: The report converts a single CAGR and headline growth into commercially relevant scenarios that show how volumes and prices can move for different end-use portfolios. This is not a vanity projection — it is a series of decision-ready scenarios that map to contract renegotiation windows, capex timetables and product development roadmaps.
- Supply shock and capacity mapping: A coming wave of capacity additions and technology-licensed plants will change bargaining dynamics for buyers and margin profiles for sellers. The study flags timing mismatches between new-build startups and demand ramps so procurement and planning teams can avoid being caught with short or excess positions.
- Regulation and sustainability as business levers: ISCC-type certifications and ongoing chemical registrations are raising the bar for market access. We translate regulatory status into commercial consequences — for example, how sustainability-compliant feedstocks or certified supply streams can attract a premium in certain buyer segments, and what certification timelines mean for contract clauses and supplier selection.
- Concentration-aware commercial strategies: Given that a small group of suppliers captures a majority of supply, the report furnishes negotiation playbooks and offtake structuring options tailored to counterparty profiles (integrated multi-product incumbents vs. focused oxo intermediates specialists).
What’s in the full report — practical deliverables for decision makers
- Proprietary demand model (downloadable spreadsheet) anchored to 2025 base volumes and offering scenario toggles (demand elasticity, substitution, regional consumption pathways).
- Forward-looking supply schedule and capacity tracker, with timing of commissioned projects, licensing relationships and estimated startup risk bands.
- Price-out and cost-curve analysis that compares process routes (technology differentiation), feedstock sensitivities and unit economics across representative plant scales.
- Supplier scorecards and commercial risk matrix covering operational reliability, sustainability credentials, counterparty concentration risk and contractual leverage.
- M&A and JV target shortlist with strategic rationale, value levers and integration risk summaries for buyers seeking consolidation or capability acquisition.
- Regulatory tracker (REACH, national registrations and sustainability certification timelines) with recommended compliance and contract clause language.
- Commercial playbooks for buyers and sellers — negotiation checklists, hedging options, offtake structuring templates and sample term-sheets.
- Scenario-strategy annexes tailored to three plausible futures (accelerated demand, technology-driven price deflation, and a regulatory stringency shock), each with tactical 90/180/365-day roadmaps.
Competitive landscape — who shapes the market and how
The industry’s competitive architecture blends a handful of integrated, technology-capable producers with specialized oxo alcohol manufacturers and regional build-out players. The top-tier participants combine process know-how, integrated feedstock access and customer relationships in plasticizers and specialty esters; smaller players focus on niche grades, service responsiveness and regional proximity.
- Integrated global majors — Large chemical groups with licensed oxo technology and multi-site footprints retain dominant roles in supplying commodity and higher-purity grades. Their value lies in feedstock integration, scale manufacturing and established relationships with major plasticizer producers and formulators.
- Oxo specialists — Firms with a concentrated oxo intermediates portfolio offer technical service and flexible grade specifications. They are often the first choice for specialty applications where chemistry control and consistent impurity profiles matter.
- Regional scale entrants — New world-scale projects built under technology license agreements introduce step-changes in local supply economics and can compress global margins if timing aligns with demand plateaus.
Recent corporate developments illustrate these dynamics. A new licenced world-scale plant scheduled to start up in 2026 will materially increase regional availability and alter global shipment patterns; sustainability credentials (ISCC-type certification) were secured by a leading producer in 2025, positioning that supplier for premium-seeking customers; and product introductions from specialty players have refreshed the technical competitive set. Together, these moves mean that supply-side strategies — timing of capacity, certification status and technology ownership — will matter as much as traditional commercial terms when negotiating supply and pricing in 2026.
Implications by function — concise guidance for 2026 decisions
- Procurement: Lock-in interim protection: prioritize staggered offtakes, include startup-delivery risk clauses for new plants, and insist on certification evidence where sustainability premiums are at stake.
- Supply Chain & Operations: Re-run your inventory-cost tradeoffs using scenario outputs in the report; validate alternate-sourcing pathways and map logistic touchpoints for any new regional suppliers.
- R&D & Product Management: Use the technical annex to re-evaluate esterification routes and impurity tolerances; targeting alternative plasticizer formulations may reduce exposure to commodity price swings.
- Corporate Development & Investors: Treat concentration metrics and the upcoming capacity wave as triggers for opportunistic M&A or strategic JVs to secure feedstock or premium grades.
- Regulatory & Compliance: Align product registrations and sustainability claims with anticipated buyer demands — being ahead on certification is now a source of commercial advantage, not just compliance.
A practical 365‑day playbook
- 0–90 days: Secure access to the full model and supplier scorecards; run procurement simulations for contract renewal rounds; audit key suppliers on certification and startup plans.
- 90–180 days: Finalize hedge or indexation mechanisms informed by cost-curve sensitivity; negotiate strategic offtake options with producers whose startup timelines create upside or downside risk.
- 180–365 days: Decide on capex or partnership moves if forward price signals and volume visibility align; execute targeted certification pathways to capture sustainability premiums.
Concluding note — why you should read the full report
The headline numbers and strategic directions above indicate that 2026 will be a pivotal year for Isononyl Alcohol stakeholders. The full PW Consulting report converts these directional insights into executable tactics: granular supply timelines, supplier-level risk assessments, downloadable models and negotiation tools that operational teams can use the day after purchase. This briefing intentionally omits the segment-level tables, regional splits and the proprietary interactive worksheet that drive contract-level decisions. To obtain those detailed inputs — the same data we use to simulate contract outcomes, stress-test capex and prioritize M&A targets — access the complete study and the companion model on our report page.
For detailed analysis of this topic, please visit the official page: Isononyl Alcohol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com