

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: CNT Market to reach USD 1,750M in 2025 with 14.88% CAGR

Carbon Nanotubes 2026 Briefing: Strategic Imperatives for Executives
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I am pleased to introduce our newest Carbon Nanotube (CNT) Market study — a focused, execution-oriented resource designed to inform high-stakes decisions in 2026. The CNT market is no longer an experimental niche: it has reached commercial scale and is now reshaping value chains across batteries, electronics, composites, and advanced materials. Our report synthesizes macro growth, supplier dynamics, technology trajectories, regulatory headwinds, and practical playbooks so that executives can move beyond hypotheses to prioritized, risk-adjusted action.
Carbon Nanotube (CNT) Market
Why this study matters in 2026
-
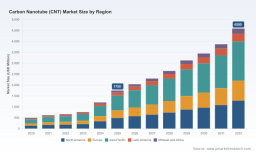
Rapid, sustained expansion. The global CNT market has shifted from early adoption to broad industrialization — rising from a modest base in 2020 to USD 1,750 Million in 2025 (base year). Our model projects this market to continue accelerating through the forecast window (2026–2032), with a compound annual growth rate of 14.88% and a projected market value of approximately USD 4,590 Million by 2032. That pace creates both scale opportunities and strategic supply risks that require active management.
Carbon Nanotube (CNT) Market -
Mid-level concentration with room to consolidate. The market exhibits meaningful clustering among a handful of players. Aggregate shares indicate a concentrated but not monopolistic supplier landscape — a structure that favors strategic partnerships, differentiated product positioning, and targeted M&A for firms seeking to move up the value chain.
Carbon Nanotube (CNT) Market -
Transition from materials R&D to application-led procurement. Key customers in EV batteries, semiconductors, and high-performance composites are moving from lab qualifications to standardized procurement processes. This shift compresses commercialization timelines and increases the value of supply-chain certainty, regulatory compliance, and validated performance data.
What the PW CNT study delivers (practical, transaction-ready content)
-
Proprietary market model (2020–2032): scenario-driven forecasts, elasticity assumptions, and sensitivity testing tailored to alternative adoption curves across primary application groups. The model lets you test demand shocks, pricing shifts, and capacity ramp schedules to quantify margin and volume impact.
-
Supplier scorecards and diligence templates: comparative technology, capacity, quality, geographic resilience, ESG scores, and go-to-contract negotiation playbooks — enabling rapid supplier selection or partnership prioritization.
-
Technology maturity matrix: product-by-product assessment (single-walled vs multi-walled vs functionalized dispersions), route-to-market prerequisites, scale-up risk factors, and qualification timelines for regulated applications (medical, semiconductor, battery).
-
Regulatory and permitting checklist: actionable compliance pathways for U.S. federal and state frameworks, including risk-data obligations, reporting thresholds, and community engagement templates to shorten approval cycles and limit operational hold-ups.
-
Commercial playbooks: price-defense strategies, bundling and value-based pricing for conductive additives, licensing and OEM supply agreements, and channel maps for entering adjacent end-markets.
-
M&A and JV opportunity screening: target criteria, valuation ranges under multiple integration scenarios, and post-deal integration roadmaps focused on accelerating application qualification and protecting IP.
-
Supply chain stress tests and contingency plans: tier-2 supplier mapping, raw material choke-point analysis, and inventory strategies to preserve manufacturing continuity during capacity swings.
Competitive landscape — what matters to 2026 strategy
The supplier universe is a mix of large, integrated chemical producers, specialized nanotube manufacturers, and nimble technology players focused on differentiated chemistries or process IP. Key themes we observe and analyze in depth:
-
Scale players are shifting the economics. Established chemical and materials companies are expanding capacity and pushing larger-volume, standardized grades targeted at batteries and conductive polymers. These moves improve availability for large OEMs but also compress margins for undifferentiated commodity grades.
-
Specialists retain premium niches. Producers with proprietary synthesis routes or high-purity, semiconducting single-walled CNTs remain indispensable for electronics, printed semiconductors, and select medical applications — markets where qualification hurdles are high and switching costs favor incumbents.
-
Vertical integration is accelerating in battery markets. Several manufacturers and battery-material suppliers are integrating CNTs into cathode/anode formulations and moving toward offering pre-dispersed or pre-formulated additives for cell makers. This trend shortens the path to adoption but raises questions about intermediated margins and captive sourcing strategies.
-
Dispersion and formulation capability is a strategic differentiator. The ability to deliver stable, low-dust, high-dispersibility CNT dispersions at scale — not just powders — is increasingly the gate to major contracts in EV batteries and conductive plastics.
Recent market inflection points (implications for decision-makers)
-
Capacity expansions among multiple suppliers have materially improved availability for volume applications. Executives need to reassess contracting timelines and pricing indexes: near-term shortages are easing in some product corridors, but demand growth tied to electric vehicles and grid storage will reintroduce localized tightness unless additional capacity is aligned with demand commitments.
-
Emerging adoption in EV cathode and anode formulations: industry validation has moved CNTs from experimental additive to standardized conductive enhancer in some battery architectures — studies report measurable reductions in internal resistance (up to 20% in validated cases). This creates a distinct value capture opportunity for suppliers that can offer certified, application-ready grades.
-
Regulatory focus is gathering pace. U.S. federal and state-level attention to nanomaterial risk and reporting increases the cost and lead time for new manufacturing or import. Firms that proactively invest in exposure data, worker-safety programs, and transparent community engagement will face lower barrier-to-entry risk and faster permitting.
Strategic actions for 2026 — a prioritized playbook
-
Secure tiered supply commitments now. Negotiate multi-year offtakes with staged volume ramps tied to qualification milestones. Use supplier scorecards and performance SLAs to protect against capacity reallocation to larger OEMs.
-
Differentiate via formulation and integration capabilities. Invest in in-house dispersion expertise, or secure exclusive co-development rights with suppliers who can deliver pre-formulated dispersions suited to your process window.
-
Fast-track regulatory readiness. Embed a regulatory readiness stream into commercialization roadmaps: prioritized hazard and exposure testing, TSCA and state reporting compliance, and targeted community engagement to reduce permitting risk and reputational exposure.
-
Adopt a layered M&A strategy. Pursue tuck-ins for formulation IP and bolt-on capacity where it shortens qualification timelines. For larger players, evaluate joint ventures with regional manufacturers to hedge trade and localization risks.
-
Model multiple demand scenarios into capital allocation. Use the report’s scenario toolkit to stress-test capex and working-capital plans against upside adoption in EVs and electronics or downside substitution risks due to competing conductive additives or regulatory constraints.
Risk matrix — what to monitor monthly
-
Regulatory shifts and reporting requirements (federal and state).
-
Rapid capacity additions that change price and availability dynamics.
-
Technological substitutions (emergent conductive additives or cheaper carbon-based solutions).
-
Supply-chain bottlenecks for precursor feedstocks and dispersion chemicals.
-
Qualification failure risk in certified end-markets (automotive, medical, semiconductors).
How to use this report in board- and investor-level discussions
Bring the report to your next strategic review to:
-
Quantify upside and downside cases for capital allocation to CNT-enabled product lines.
-
Prioritize M&A targets that accelerate qualification or secure supply for 2027–2028 production ramps.
-
Design procurement KPIs that align supplier incentives with your commercialization timeline.
-
Create an ESG-compliance roadmap tied to operational KPIs and community/stakeholder disclosures.
Final takeaways
CNTs are transitioning from specialized materials to strategic inputs for multiple scaling industries. The market is growing rapidly (14.88% CAGR over the forecast window), with clear commercial opportunities in batteries, electronics, and high-performance composites. This creates an imperative for companies to move from exploratory projects to mature procurement, regulatory readiness, and integrated product strategies in 2026.
Our PW Consulting CNT study is intentionally built as a decision engine — not just an academic paper. It combines a scenario-capable market model, supplier diligence tools, regulatory playbooks, and M&A screening to convert market growth into sustainable business outcomes. The executive summary and strategic checklist above are a preview of the actionable, transaction-focused content inside; the full study contains the granular segmentation, supplier-by-supplier benchmarking, and model access you will need to operationalize these strategies.
For teams preparing capital plans, supplier negotiations, or R&D roadmaps this year, the horizon is clear: act now to secure differentiated supply, accelerate qualification, and embed regulatory readiness into commercialization plans. Our report shows you how — with the level of granularity executives need to commit capital and the practical templates to execute.
For detailed analysis of this topic, please visit the official page: Carbon Nanotube (CNT) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com