

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Organic PVC Stabilizers Market hits USD 1,251M in 2025, 2.2% CAGR

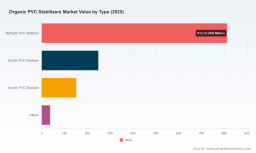
Organic PVC Stabilizers Market: Strategic Imperatives for 2026
Executive snapshot
By 2025 the global organic PVC stabilizers market had consolidated into a mature, specialized value chain characterized by steady demand and regulatory-driven disruption. Our base-year analysis shows an industry that generated roughly USD 1.25 billion in revenue in 2025 and is expected to expand at a modest compound annual growth rate (CAGR) of about 2.2% across the 2026–2032 forecast window, reaching approximately USD 1.46 billion by 2032. For executives planning capital allocation, M&A, or product roadmaps in 2026, this profile signals a market where margin preservation, regulatory alignment and selective innovation will deliver disproportionate returns.
Organic PVC Stabilizers Market
Why this report matters for 2026 decision-making
- Clarity amid regulation: The transition away from legacy additives (lead and other restricted systems) toward organic, and increasingly bio-based, stabilizer platforms is no longer hypothetical — it is an operational necessity in many jurisdictions. Firms without a considered regulatory-to-product roadmap risk losing access to premium applications.
- Margin management in a premium segment: Organic stabilizer systems command a 25–40% price premium versus traditional lead-based alternatives while providing extended service life. That premium provides runway for investment, but it also attracts competitive entrants and cost pressures.
- Supply-side volatility: Key raw material categories have experienced sharp cost moves in recent cycles — calcium-based and zinc-derived inputs saw material cost escalations since early 2023 — requiring proactive procurement and product re-engineering strategies to protect margins.
- Concentrated supplier structure: The market structure is moderately concentrated, with the top three players accounting for roughly half of industry output and the top five approaching two-thirds — a dynamic that shapes pricing power, partnership opportunities and consolidation targets.
Market dynamics shaping strategy in 2026
Three structural forces will drive executive choices this year:
Organic PVC Stabilizers Market
- Regulatory acceleration and product re-specification. Regulatory frameworks such as REACH and national standards are accelerating substitution away from lead and other legacy stabilizers. Concurrently, Asia’s evolving GB standards and similar controls are reshaping specification lists for pipe, profile and food-contact applications. The practical implication: product roadmaps must prioritize certifiable, lead-free chemistries and demonstrate lifecycle benefits.
- Raw materials and margin squeeze. Recent industry data show double-digit increases in key raw-material inputs, with calcium-based compounds and zinc derivatives among the hardest-hit. Given the price premium customers tolerate for organic systems, suppliers who can redesign formulations to reduce exposure to the most volatile inputs — or who can secure advantaged feedstock contracts — will sustain better margins.
- Bio-based innovation as a strategic lever. Bio-derived ligands (from vegetable oils, castor oil and agricultural residues) are moving from lab to commercial trials to replace petroleum-based thiols. Early movers that can validate performance, supply scalability and regulatory acceptance will capture share in higher-margin, sustainability-oriented segments.
Segmentation and demand signals (strategic view)
While demand spans core PVC applications — construction profiles, packaging films, medical-grade instruments and other industrial uses — the practical takeaway for leaders is not a granular percentage split but a functional one: application-critical segments (where product failure implies regulatory or safety risk) will continue to pay a premium for proven, certified stabilizer systems. Commodity-oriented channels are more price-sensitive and will prioritize cost-reduction or blended solutions. Our full study contains the complete historical-to-forecast segmentation that operational teams will need to prioritize SKUs and go-to-market investments.
Organic PVC Stabilizers Market
Competitive landscape — strategic positioning of key players
The competitive map combines global specialty formulators and regional producers with different value propositions. Key firms exemplify three distinct strategic archetypes:
- Technology-specialists with premium positioning. Players focused on high-efficiency organotin stabilizers and engineered heat-stabilization systems target high-value rigid PVC applications (pipe, fittings, exterior use). Their differentiation rests on formulation know-how, quality certifications and channel relationships with OEMs and compounders.
- Volume-oriented manufacturers with cost leadership ambitions. Several Asia-based producers leverage scale and proximity to regional polymers and additive feedstocks to compete on price across broad PVC applications. They focus on operational efficiency and regional distribution to defend share.
- Sustainability-led entrants and hybrid providers. European and specialty global suppliers position sustainable or bio-based stabilizer systems as a way to enter regulated, high-margin applications or to secure preferred-supplier status with multinational compounders and brand owners.
Representative companies illustrate these archetypes: firms offering organotin variants and heat-stable systems, regional manufacturers serving mass-market pipe and sheet producers, and value-added suppliers integrating bio-based ligands and lead-free systems. The competitive reality is that collaboration — for example, between formulators and bio-feedstock suppliers — is becoming a critical route to market differentiation.
Practical contents of the full PW Consulting report
Our full study is designed for operational and strategic users who need executable intelligence, not theory. Highlights include:
- Validated historical demand (2020–2025) and a detailed 2026–2032 forecast model with scenario pathways for different regulatory and raw-material trajectories.
- Competitive benchmarking across product portfolios, technology platforms and regional go-to-market models, including a granular view of market concentration and candidate targets for M&A or partnership.
- Formulation-level sensitivity analysis showing how input-price shocks (e.g., calcium and zinc derivatives) ripple through gross margins under alternative pass-through strategies.
- Regulatory readiness playbooks, mapping accelerated certification pathways and compliance checklists for key export markets.
- Commercial playbooks with prioritized application segments, channel strategies, and pricing levers for 2026 implementation.
To preserve commercial value for subscribers, the report deliberately withholds certain fine-grain segmentation tables and client-level benchmarking from free summaries — these are available through the report portal.
Actionable strategic recommendations for 2026
Based on scenario testing and proprietary supply-chain modeling, we recommend five near-term moves that should be prioritized this year:
- Lock in diversified feedstock contracts — establish multi-sourcing agreements and hedging mechanisms for calcium- and zinc-based inputs. Procurement flexibility will be a decisive margin lever through 2026.
- Accelerate bio-based pilots with clear go/no-go metrics — invest in pilot-scale formulations using bio-derived ligands, but define performance, cost and regulatory acceptance criteria upfront to avoid sunk-cost drift.
- Reposition premium SKUs for regulated applications — migrate R&D and certification spend toward applications where customers accept a premium for verified lead-free, long-life stabilizers (e.g., medical, food-contact, critical infrastructure).
- Evaluate bolt-on acquisitions and distribution partnerships — target regional formulators or feedstock specialists that can accelerate market access or reduce unit costs; use the market concentration profile to identify vulnerable mid-sized incumbents.
- Implement transparent value-pricing — communicate total-cost-of-ownership benefits to end-users (longer service life, fewer rejects, compliance risk reduction) to justify and sustain the sector’s price premium.
How to use PW Consulting’s intelligence in 90 days
- Week 1–2: Run the report’s procurement sensitivity matrix against your current supplier contracts to quantify exposure to recent raw-material shocks.
- Week 3–6: Pilot a bio-ligand trial with a single compounder customer using the report’s supplier shortlist and certification checklist.
- Week 6–12: Use our competitive mapping to screen two M&A or partnership targets and run financial due diligence scenarios aligned to the forecast model.
Closing: what leaders must decide in 2026
2026 will be less about explosive volume growth and more about strategic choices: who secures regulatory-compliant formulations, who protects margins in the face of feedstock volatility, and who captures the sustainability premium through verifiable, scalable bio-based solutions. With a predictable low-single-digit CAGR at the market level and concentrated supplier dynamics, the winners will be those who combine disciplined procurement, selective innovation and market-specific go-to-market plays.
PW Consulting’s full Organic PVC Stabilizers Market report provides the detailed segmentation, scenario models and competitive dossiers necessary to operationalize these choices. For executives whose 2026 plans depend on precise timing and prioritized investments, the full report is the decision-useable intelligence you cannot defer.
For detailed analysis of this topic, please visit the official page: Organic PVC Stabilizers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com