

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: DNA Sequencing Market to Hit USD 44.63B by 2032 at 14.9% CAGR

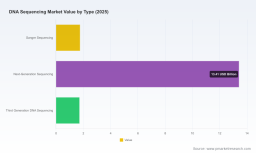
DNA Sequencing Market 2026: Strategic Preview for C-Suites and Investment Teams
As organizations plan capital allocations and go-to-market moves for 2026, DNA sequencing is no longer a niche enabling technology — it is central to differentiated clinical programs, public-health infrastructure, and population-scale research. PW Consulting’s latest DNA Sequencing Market study (base year 2025) synthesizes seven years of historical performance, a robust 2026–2032 forecast, and scenario-ready strategic frameworks to guide decisions in a market that is expanding rapidly and consolidating simultaneously.
DNA Sequencing Market
Why this study matters for 2026 decision-making
-
Clear financial trajectory: After growing from a modest multibillion-dollar base in 2020, the DNA sequencing market reached a notable inflection by 2025 and is projected to more than double by the end of the 2026–2032 forecast horizon under a high-teens compound annual growth profile (CAGR: 14.9%). This acceleration reflects simultaneous demand expansion across clinical diagnostics, research, public health, and industrial applications.
DNA Sequencing Market -
Consolidation + disruption: Market concentration metrics indicate a competitive environment where a small group of large vendors capture a meaningful share of revenue, even as new entrants and platform innovations challenge incumbency. That dynamic creates differentiated opportunities for partnership, vertical integration, or strategic disintermediation.
DNA Sequencing Market -
Regulatory and standards inflection points: Recent and near-term regulatory moves are lowering barriers for clinical adoption of advanced sequencing while raising technical and quality barlines — a combination that amplifies first-mover advantages for compliant, validated solutions.
Market trajectory: what the numbers tell strategic planners
PW Consulting’s analysis integrates historical performance (2020–2025) and demand modelling to produce a forward view through 2032. The market’s historic climb into 2025 reflects intensifying investment in next-generation sequencing (NGS), growing use of sequencing in oncology and infectious disease surveillance, and the steady maturation of long-read and high-throughput platforms. From the 2026 vantage, we forecast sustained, structural growth — driven by broader clinical adoption, population genomics programs, and automation-led cost reductions — that translates into a multibillion-dollar expansion by 2032 under the stated 14.9% CAGR.
Two implications are immediate for 2026 planning: capital allocation should prioritize modular, upgradable platforms that protect against rapid obsolescence; and commercial strategies must be prepared to monetize both instrument sales and recurring consumables, plus higher-value services such as bioinformatics and regulatory-compliant assays.
Competitive landscape: incumbents, challengers, and strategic bets
The market’s competitive topology is defined by legacy platform leaders, specialized innovators in long-read and single-cell technologies, and new entrants focused on throughput and cost-per-genome economics. Key players profiled in our study include (but are not limited to):
-
Illumina, Inc. — Leader in high-throughput and clinical-grade NGS platforms and an expanding portfolio aimed at whole-genome MRD research and WGS-based clinical workflows.
-
Thermo Fisher Scientific Inc. — Broad-spectrum genomics portfolio spanning NGS, Sanger, and supporting consumables, enabling cross-selling to existing laboratory customers.
-
Oxford Nanopore Technologies plc — Differentiated by nanopore long-read platforms and portable solutions that open new use cases in field diagnostics and real-time surveillance.
-
Pacific Biosciences (PacBio) — Focused on HiFi long-read sequencing for applications demanding high accuracy and structural-variant resolution.
-
10x Genomics — Pioneering single-cell and spatial omics integrations that increasingly intersect with DNA sequencing workflows.
-
Element Biosciences, Ultima Genomics, BGI/MGI, QIAGEN, Clear Labs, and Tempus — A mix of platform challengers, cost-innovation plays, assay specialists, and integrated clinical genomics providers.
Our competitive analysis evaluates each firm across platform economics, consumables dependency, clinical validation status, regulatory readiness, partnerships, and route-to-market. Importantly, the study offers vendor selection matrices tailored to five archetypal buyer personas — from national public-health agencies to decentralized clinical labs — making it directly actionable for procurement teams.
Regulatory, standards, and policy context shaping 2026 strategies
-
Regulatory momentum: Draft guidance from the FDA in April 2026 addressing NGS-based safety assessment in genome-editing therapeutics signals growing regulatory sophistication around sequencing readouts used in clinical trials. Companies that align early with these guidance expectations will face lower friction in trial initiation and downstream approval pathways.
-
Public health mandates: The EU’s recent regulation requiring whole-genome sequencing for several key foodborne pathogens underscores a near-term demand surge for validated WGS pipelines in government surveillance and diagnostics — a durable revenue channel for compliant vendors.
-
Quality and interoperability standards: Ongoing work on genomics informatics quality-control standards (e.g., ISO/DIS 22692) is creating a common language for assay performance, enabling greater interoperability across instruments and bioinformatics stacks — and raising the bar for vendors that have not invested in robust QC frameworks.
What the PW Consulting report delivers (practical, decision-ready content)
Our full study is constructed as a playbook for executives and strategy teams. Highlights include:
-
Commercial roadmaps and scenario planning: Three adoption scenarios (conservative, base, accelerated) linked to procurement timelines, revenue waterfalls, and capex/opex sensitivity analyses.
-
Go-to-market and partnership playbooks: Actionable models for channel strategies, co-development agreements, and bundling approaches that optimize lifetime value across instruments, consumables, and services.
-
Vendor selection and RFP templates: Scored supplier evaluation frameworks that factor clinical validation, throughput scalability, total cost of ownership, and regulatory readiness.
-
Investment theses and M&A target screening: Financial and strategic criteria to shortlist acquisition targets or JV partners that close capability gaps (e.g., informatics, sample prep automation, or specialized assays).
-
Implementation and lab-ops playbook: Bench-level process flows, staff training roadmaps, and automation integration guides designed to compress time-to-value post-purchase.
-
Risk matrices: Compliance, reimbursement, supply-chain, and obsolescence risks with mitigation steps and trigger-based monitoring dashboards.
To preserve the report’s utility as a commercial research product, we deliberately withhold detailed sub-segment allocations and full numerical breakdowns in this preview. The full dataset contains granular splits by technology type, application, and region, plus unit-level pricing models and per-use economics required for procurement and financial modelling.
Case examples: how 2026 leaders will deploy sequencing strategically
-
Clinical networks: Integrated health systems will prioritize validated whole-genome workflows for oncology decision support and MRD detection, pairing sequencers with end-to-end informatics and local reimbursement strategies.
-
Public health agencies: National labs will invest in standardized WGS pipelines for routine surveillance and outbreak response, seeking partners with validated assays and compliance-ready reporting functionalities.
-
Population genomics initiatives: Governments and consortiums will favor suppliers that can deliver high-throughput, low-cost per-sample solutions plus turnkey logistics for sample collection and data governance.
-
Industrial and agrigenomics applications: Companies in food safety and agriculture will adopt automated NGS platforms for traceability and pathogen surveillance, leveraging regulatory mandates to finance deployments.
Recent moves worth watching (signals of near-term competitive shifts)
-
Product innovations: Several major vendors announced platform rollouts and early-access programs in 2025–2026 targeted at clinical-grade whole-genome applications and automated infectious-disease assays — moves that compress validation timelines for end-users who prioritize vendor-backed, turnkey solutions.
-
Automation and assay partnerships: New automated solutions and integrated assays for rapid pathogen identification are accelerating adoption in clinical microbiology and food-safety labs.
-
Standards and regulation-driven demand: Regulatory guidance and mandatory surveillance programs are creating predictable demand waves that can be captured by vendors who offer validated, standards-compliant stacks.
Decision checklist for 2026
-
Align procurement with regulatory timelines — choose platforms whose validation roadmaps map to anticipated guidance milestones.
-
Prioritize modularity — pick architectures that allow incremental upgrades to cost-effectively capture future performance improvements.
-
Capture recurring revenue — build commercial models that combine instrument placement with consumables, software subscriptions, and managed services.
-
Mitigate supply and standards risk — require audit trails and interoperability commitments in vendor contracts to protect operations against evolving QC standards.
Next steps
PW Consulting’s full DNA Sequencing Market report contains the detailed segmentation, vendor models, and numerical forecasts needed to operationalize any of the strategies sketched above. If you are preparing capital plans, vendor sourcing, or an investment thesis for 2026, the report offers the data, templates, and scenario playbooks to move from insight to execution.
Contact PW Consulting to request the complete dataset, vendor scorecards, and our executive briefing packages — designed to get your leadership aligned and ready to act in 2026.
For detailed analysis of this topic, please visit the official page: DNA Sequencing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com