

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Wheel Balancer Market to Reach USD 320M by 2032 at 4.1% CAGR

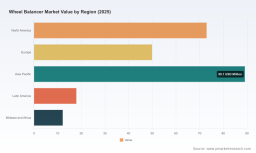
Wheel Balancer Market — 2026 Strategic Preview
As fleet operators, OEM aftermarket strategists, private equity sponsors, and service-chain leaders plan for 2026, the wheel balancer market presents a disciplined, technology-led growth opportunity. This preview synthesizes the strategic implications from PW Consulting’s new Wheel Balancer Market research (base year 2025) and explains how executives should translate macro momentum into practical decisions this year. It demonstrates the depth of our analysis while deliberately withholding the granular segment tables that form the full dataset — a design choice intended to guide decision-makers to the full report for executable metrics and models.
Wheel Balancer Market
Market snapshot: trajectory and implications
-
The market has expanded steadily over the past half decade, rising from approximately USD 183.0 Million in 2020 to USD 242.0 Million in 2025 (base year). The research models a continuation of growth into the forecast window, reaching roughly USD 320.0 Million by 2032 — a compound annual growth rate (CAGR) of about 4.1% across the 2026–2032 period.
Wheel Balancer Market -
That profile — mid-single-digit CAGR with sustained incremental gains — signals a mature equipment category driven by replacement cycles, workshop productivity upgrades, regulatory enforcement, and targeted capital investments from fleet and dealer networks rather than by episodic consumer-driven spikes.
Wheel Balancer Market
Why this research matters to 2026 decision-makers
-
Capital allocation: With modest but consistent growth, timing CAPEX for balancing equipment is a question of ROI cadence. Our models show payback horizons compressed when balancing hardware is bundled with automation and connected diagnostic services — a crucial insight for budgeting in 2026.
-
Product & R&D roadmaps: Companies pursuing differentiation should prioritize hands-off automation, integrated diagnostic capabilities, and fleet-oriented interfaces. Early adopters of such features are positioned to capture share from high-volume operators and to command premium aftermarket software revenues.
-
M&A and partnership screening: The category exhibits a medium level of consolidation; the top three participants control a meaningful but not overwhelming portion of global value (our research estimates third-party concentration metrics indicating space for targeted bolt-on acquisitions). Buyers should prioritize targets that bring either systems integration capability or captive fleet distribution agreements.
Emerging strategic themes for 2026–2032
-
Automation and “hands-off” workflows: The newest product introductions emphasize speed and safety — automation reduces labor intensity and addresses technician shortages. Recent product launches that automate inflation, measurement, and data capture compress service times and reduce operator variability.
-
Integration with diagnostics and tire changers: Leading manufacturers are integrating wheel balancing into broader service ecosystems (tire changers, alignment systems, and shop management software). These integrations create sticky solutions and recurring data-revenue opportunities.
-
Fleet programs and validation: Approval by major logistics operators following field evaluations positions certain suppliers to secure programmatic replacements. Fleet endorsements materially change total addressable aftermarket opportunity and provide proof points for other customers.
-
Regulatory and safety drivers: Compliance regimes (national vehicle inspection programs and occupational safety standards) are a non-cyclical demand pillar. Ensuring equipment meets OSHA, CE and relevant ISO requirements and aligns with TÜV/MoT inspection criteria is increasingly table-stakes for suppliers and buyers.
-
Regional service network economics: While growth is not uniform globally, the service economics favor suppliers that combine competitive hardware pricing with strong aftermarket support and spare-parts logistics to shorten downtime for workshops and fleets.
Competitive landscape — who to watch
The sector’s competitive dynamics are defined by a mix of global incumbents and specialized equipment manufacturers. Key players profiled in the report include:
-
Hunter Engineering Company (Bridgeton, Missouri, USA) — https://www.hunter.com — Known for diagnostic wheel balancers such as the Road Force range; recent product activity highlights an emphasis on automation and integrated inflation that reduce tire changeover times.
-
Coats Company LLC (La Vergne, Tennessee, USA) — https://coatscompany.com — Focused on heavy-duty, direct-drive balancers designed for high-volume operations; product positioning centers on robustness and throughput in tire service environments.
-
Snap-on Incorporated (Kenosha, Wisconsin, USA) — https://www.snapon.com — Offers motorized workshop balancers for high-volume shops, emphasizing reliability and dealer channel reach.
-
CEMB S.p.A. (Italy) — https://cemb.com — Supplies garage and truck balancers with vibration analysis and touchless alignment compatibility, targeting workshop productivity gains.
-
IMI Products (Chambersburg, Pennsylvania, USA) — https://www.imiproducts.com — Delivers adaptive internal balancing systems for fleet truck tires; recent approvals by major logistics operators validate fleet-scale performance and durability claims.
-
Balance Group (China) — https://www.unitequipment.com — Integrates balancers into comprehensive tire-service equipment lines; competitive on price and breadth, with growing international distribution.
Market concentration is moderate: our competitive-concentration metrics show the top three and top five suppliers control a significant share of market value but leave scope for regional specialists and new entrants that can offer system-level value. This dynamic favors a bifurcated approach: incumbent players should pursue platform-level differentiation while mid-sized vendors focus on niche technical advantages and channel partnerships.
Recent developments shaping 2026 strategy
-
Product innovation: Late-2025 launches emphasized automation and workflow reduction, with suppliers publicly demonstrating integrated machine pairings at major industry shows.
-
Fleet authorization: In 2026, field-evaluation approvals for fleet programs confirmed the commercial viability of adaptive balancing solutions and unlocked programmatic replacement pathways.
-
New heavy-duty offerings: Suppliers continue to push precision and ease-of-use into the truck segment, closing performance gaps between shop-oriented and fleet-oriented equipment.
What the full PW Consulting report delivers (high-level)
PW Consulting’s Wheel Balancer Market research provides a complete decision kit for executives needing to operationalize strategy in 2026. The full report includes (summary):
-
Proprietary demand models and region-agnostic forecasts mapped to vehicle parc and replacement cycles (historical 2020–2025, forecast 2026–2032).
-
Go-to-market playbooks for equipment OEMs and distributors that cover channel economics, leasing strategies, and retrofit service packages.
-
Vendor scorecards and capability matrices — hardware, software, service, compliance — plus a shortlist of high-probability acquisition targets using validated deal-selection criteria.
-
Operational tools: total cost of ownership calculators, payback analysis across automation tiers, and deployment roadmaps optimized for different shop and fleet archetypes.
-
Compliance and safety annexes that translate OSHA, CE, ISO, and inspection regime requirements into procurement checklists and retrofit schedules.
How to apply these insights in 2026 (practical next steps)
-
For OEMs and product leaders: prioritize R&D that bundles automation with diagnostic data capture and remote service capabilities; pilot one-click workflows with marquee fleet customers this year.
-
For distributors and workshop chains: evaluate bundling opportunities (balancer + changer + software) to increase ticket size and lock in recurring service revenue.
-
For fleet managers and operators: leverage the 2026 purchasing window to run field pilots that quantify downtime reduction and fuel/maintenance benefits tied to vibration mitigation.
-
For investors: target acquisitions that bring either integration capability (software + hardware) or exclusive access to fleet programs; ensure diligence captures in-use reliability and spare-parts economics.
Methodology note and how to access the full intelligence
The study’s base year is 2025, with a historical window covering 2020–2025 and a forecast horizon spanning 2026–2032. Forecasts and scenarios combine bottom-up equipment installed-base analysis, replacement-cycle modeling, vendor shipment data, and primary interviews across workshops, fleets, and OEM service networks. To preserve the integrity of our commercial offering while demonstrating analytical depth, we have presented headline market trajectory and strategic implications here. Detailed segment tables, regional breakdowns, competitive scorecards, and downloadable models are included in the full PW Consulting Wheel Balancer Market report.
For executives looking to operationalize these insights in 2026 — whether to optimize CAPEX, shape product roadmaps, or identify acquisition targets — the full report and supporting datasets provide the granular inputs and playbooks necessary to act with confidence.
For detailed analysis of this topic, please visit the official page: Wheel Balancer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com