

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Enzyme for Pulp & Paper Market Poised for 8.6% CAGR Through 2032

Enzyme for Pulp & Paper Market — Strategic Preview for 2026 Decision-Makers
As companies step into 2026, the enzyme value chain for pulp & paper sits at a strategic crossroads: accelerating sustainability commitments and cost pressures on one side, and rapid technological maturation and supplier consolidation on the other. This preview synthesizes PW Consulting’s latest market study (base year 2025) to show why enzyme strategies must move from pilot projects to boardroom-level prioritization this year. We present the high-level market trajectory, competitive implications, and the practical decision levers executives should act on now — while preserving the granular regional, product-type, and application splits for readers who download the full study.
Enzyme for Pulp & Paper Market
Market trajectory — what the headline numbers tell you
Our market model (USD, revenue unit: Million; base year 2025) shows a clear growth path: after recovering from mid-cycle volatility in the early 2020s, the enzyme market for pulp & paper reached an inflection point in 2024–2025 and is forecast to expand at a compound annual growth rate (CAGR) of 8.6% through the 2026–2032 horizon. The market size in the base year (2025) sits within the low hundreds of USD millions and is projected to approach the high hundreds by the end of the forecast window. This pace of growth — materially above many adjacent chemical and additive categories — reflects a convergence of regulatory pushes, mill-level ROI from process optimization, and supplier innovation in enzyme formulations and service models.
Enzyme for Pulp & Paper Market
Two features of the historical series are instructive for 2026 planning: first, growth has been uneven, reflecting sensitivity to raw-material and energy swings; second, once deployed, enzymatic interventions deliver recurring unit-cost benefits (energy, chemical use, runnability) that compound over time, giving early adopters an advantage as the market scales.
Enzyme for Pulp & Paper Market
Why 2026 is a strategic inflection for corporates
- Regulatory momentum converts into procurement mandates. Recent EU guidance explicitly favors enzyme-assisted bleaching and pulping to lower toxic by-products and water use, and tighter enforcement in several Asian markets is accelerating conversion away from legacy chemical recipes. Compliance is shifting from discretionary sustainability projects to required operational upgrades.
- Unit economics increasingly favor enzymes in retrofit decisions. Enzymatic pre-treatment and process optimization reduce electricity and chemical consumption, improve drainage and runnability, and can lengthen machine run-times — generating Total Cost of Ownership (TCO) improvements sufficient to justify modest capital or OPEX reallocation in many mill archetypes.
- Supply-side concentration drives supplier strategy. The sector shows high top-player concentration, meaning market access, long-term supply terms, and co-development advantages will be shaped by a small set of strategic suppliers. This dynamic makes vendor selection, multi-sourcing, and contractual protections central to 2026 procurement strategies.
- Macro volatility is a catalyst, not a brake. Recent fluctuations in pulp prices and labor-cost indexes highlight the sensitivity of mills to feedstock and operating costs. Where enzyme solutions reduce variable costs, they become an effective hedge — especially for mills processing recycled fiber or operating at narrow margin thresholds.
Practical strategic questions for leadership in 2026
- Which mills in your footprint deliver the fastest payback from enzyme adoption — and what capital or incentive structures unlock that conversion within this fiscal year?
- How many suppliers do you need under contract to secure continuity and pricing leverage without sacrificing access to innovation and co-development options?
- What governance, measurement, and digital controls must be in place to ensure enzyme dosing translates into repeatable KPI improvements (energy per tonne, chemical savings, production up-time)?
- Where should R&D focus — formulation adaptation for recycled feedstock, enzyme stability under variable mill conditions, or enzyme+digital service bundles — to secure differential margins by 2028?
Competitive landscape — what suppliers are signaling
The market is shaped by a small set of experienced industrial biosolutions providers and specialized enzyme houses. Leading players combine product portfolios with application expertise and service models that integrate into mill operations. Highlights from vendor behavior and public announcements provide tactical cues for decision-making:
- Novonesis (Copenhagen, Denmark) — https://www.novonesis.com
Novonesis positions itself around industrial biosolutions with a fiber-focused portfolio (FiberCare®) aimed at refining, strength improvement, and energy reduction. Their product catalog updates emphasize scaling refining capacity while reducing energy intensity — a direct appeal to mills seeking immediate OPEX reductions without heavy CAPEX. - BASF SE (Ludwigshafen, Germany) — https://www.basf.com
BASF leverages broader biochemical expertise to position enzyme solutions as enablers of bleaching optimization and process efficiency, drawing on previous biotechnology acquisitions. For clients, BASF’s scale can mean integrated supply, risk management, and cross-application know-how. - AB Enzymes (Darmstadt, Germany) — https://www.abenzymes.com
AB Enzymes has explicitly targeted drainage, deposit reduction, and “runnability” with ECOPULP® offerings. Their product innovation and mill-level trial results are useful benchmarks for procurement specifications and pilot designs. - Buckman (Memphis, Tennessee, USA) — https://www.buckman.com
Buckman’s enzymatic portfolio focuses on mill operational challenges — stickies control and deinking — and their commercial moves (including recent price adjustments in certain regions) illustrate how input-cost pressures propagate through enzyme pricing and should be anticipated in forward budgeting. - Enzymatic Deinking Technologies (EDT) — https://www.edt-enzymes.com
EDT’s specialization in recycling and deinking offers a useful comparative lens: boutique specialists often outperform on niche applications and service intensity, making them attractive partners for mills prioritizing recycled-fiber streams.
Collectively, the top three to five suppliers capture a substantial share of the market, which concentrates negotiating power but also reduces buyer search costs for validated solution packages. For corporates, that means negotiating beyond price — securing knowledge-transfer, performance guarantees, and joint ROI governance becomes the differentiator.
Operational, commercial and M&A playbook for 2026
- Operational pilots, standardized scale-up. Move from single-trial pilots to a standardized pilot-to-scale protocol with predefined success criteria (energy per tonne, chemical dose reduction, run-time improvement). Insist on A/B controlled trials and third-party measurement where possible.
- Procurement as a strategic function. Shift procurement dialogue from unit price to outcome-linked contracting: multi-year supply agreements with performance SLAs, volume-flex mechanisms, and R&D co-investment clauses.
- Smart CAPEX allocation. Prioritize low-capex enzyme retrofits with clear payback thresholds in 12–36 months, and earmark a portion of sustainability capex for enzyme-enabled process changes that deliver measurable emissions and effluent reductions.
- M&A and partnerships. Given the high market concentration and specialized capabilities, acquisitive or JV strategies can accelerate access to proprietary formulations and service teams — particularly for companies seeking to own recycling/deinking expertise or digital dosing capabilities.
Report deliverables — what the full study provides (practical, actionable)
PW Consulting’s full Enzyme for Pulp & Paper Market study is designed as a tool-kit for decision-makers, not just a narrative. It includes:
- Comprehensive market sizing and a dynamic forecast model (2026–2032) with scenario toggles to test price, raw-material, and adoption-rate sensitivities.
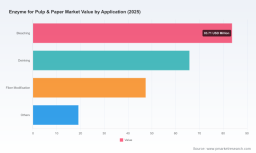
- Segmented demand analysis by region, enzyme type, and application — presented with decision-useful KPIs rather than only percentage tables (note: granular splits are intentionally reserved for the full report to preserve actionable value).
- Supply-side intelligence: vendor profiles, capability maps, commercial model comparisons, and a negotiation playbook tailored to enzyme contracts.
- Operational playbooks: standardized pilot design templates, ROI and TCO calculators, KPI dashboards, and a step-by-step mill conversion checklist.
- Regulatory and risk matrix: mapping of regional regulatory levers (including EU BREF recommendations and major Asian enforcement trends), permitting timelines, and compliance-impact scenarios.
- M&A and partnership shortlist: screened targets and partnership archetypes with estimated rationale and high-level valuation mechanics for corporate development teams.
- Case studies and benchmarking: anonymized mill case work showing realized energy, chemical, and runnability improvements, and sensitivity analyses on payback under different pulp-price regimes.
Immediate actions we recommend for 2026
- Commission a 90-day portfolio review to identify priority mills for enzyme adoption pilots, and align CFO, plant, procurement, and sustainability KPIs before pilots begin.
- Negotiate pilot-inclusive supply agreements that include escalator protections and outcome-based rebates to share implementation risk with suppliers.
- Assign a centralized “enzyme program office” to harvest cross-mill learnings and accelerate scale-up once pilots meet predefined KPIs.
- Evaluate strategic partnerships or tuck-in acquisition targets among specialist enzyme providers to secure IP and service capabilities that are increasingly valuable in a concentrated supplier landscape.
Conclusion — why accessing the full report matters now
2026 will determine which companies treat enzyme adoption as a tactical sustainability checkbox and which convert it into a structural efficiency lever. The market’s double-digit growth trajectory (CAGR 8.6% across the forecast window) and concentrated supplier landscape create both opportunity and execution risk. PW Consulting’s full study equips executives with the models, playbooks, and supplier intelligence required to move from pilots to portfolio-level deployment while preserving negotiating leverage and demonstrable ROI.
For senior teams preparing CAPEX cycles, procurement commitments, or M&A deliberations this year, the granular segmentation, mill archetype recommendations, and downloadable financial models in the full report are the necessary next step. Contact PW Consulting or visit the report page to access the detailed splits, supplier scorecards, and the scenario model that will underpin your 2026 enzyme strategy.
For detailed analysis of this topic, please visit the official page: Enzyme for Pulp & Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com