

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 6.12% CAGR for Worldwide Automated Poly Bagging Machines Market, Topping USD 724.18 Million by 2032

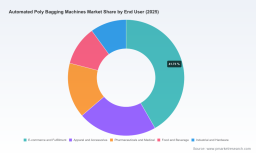
Worldwide Automated Poly Bagging Machines Market: Strategic Imperatives for 2026 Decision-Makers
As global supply chains continue to evolve under the twin pressures of e-commerce acceleration and labor availability, automated poly bagging machines have moved from niche efficiency investments to core infrastructure for fulfillment, retail and light industrial operations. PW Consulting’s latest market study—covering 2020–2025 historicals and a 2026–2032 forecast horizon—delivers the forward-looking intelligence that procurement leaders, operations VPs and private equity investors need to make high-confidence decisions in 2026.
Worldwide Automated Poly Bagging Machines Market
High‑level market trajectory: what the numbers tell us
- The automated poly bagging machines market has demonstrated steady expansion over the past five years, growing from a base of USD 345.12 Million in 2020 to an estimated USD 478.45 Million in 2025.
- Our scenario-based forecasts project continued expansion through the 2026–2032 period, with the market reaching an estimated USD 724.18 Million by 2032. The modeled compound annual growth rate (CAGR) for the forecast window is 6.12%.
- These topline dynamics underscore a market that is mature enough to support supplier specialization and scale, yet still presents multi-year upside for early adopters of next‑generation automation and integration strategies.
Why this report matters for 2026 strategic choices
During calendar-year 2026, capital allocation and vendor selection choices will lock in operational performance for at least the next five years. The PW Consulting report is structured to inform those choices through three decision-centric lenses:
Worldwide Automated Poly Bagging Machines Market
- Timing and sizing of capital expenditure: which equipment classes deliver the fastest payback under prevailing labor and throughput constraints.
- Vendor and technology selection: comparative performance, service footprint, and upgrade pathways for horizontal vs. vertical, tabletop vs. floor-mounted and modular vs. monolithic systems.
- Supply chain and procurement risk management: raw material exposure, aftermarket spare parts strategies and options for nearshoring versus continued global sourcing.
We designed the report as a practical toolkit rather than an academic exercise—aimed to move teams from insight to implementation faster.
Worldwide Automated Poly Bagging Machines Market
What’s inside: practical sections that drive implementation
- Executive playbook: succinct scenarios and a recommended 18‑month roadmap for pilot-to-scale automation rollouts tailored to different throughput profiles.
- Market sizing and trend analysis: topline historicals and modeled forecasts (2026–2032) with sensitivity testing across demand, material cost and labor scenarios.
- Buyer’s guide and TCO templates: standardized CAPEX/OPEX models, KPI definitions (e.g., throughput per labor hour, mean-time-to-repair), and a vendor short‑list matrix for rapid RFQ development.
- Competitive vendor scorecards: capability matrices and procurement playbooks to negotiate bundled equipment-and-service contracts, including SLA templates and spare‑parts cadence planning.
- Supply chain & cost dynamics: analysis of raw material trends, lead‑time risk, regulatory considerations and cost pass‑through models.
- M&A and consolidation outlook: deal themes, valuation levers, and integration checklists for strategic acquirers and corporate development teams.
- Case studies and implementation vignettes: real‑world RoI profiles drawn from diverse end‑use contexts—fulfillment centers, apparel/goods, and light manufacturing—highlighting pitfalls and accelerants.
Key market dynamics and risks to model into 2026 plans
Three core forces should be explicitly modeled into any 2026 investment plan:
- Labor dynamics: persistent shortages and rising wage pressure in warehousing are key drivers of automation adoption. Our analysis shows that automation investments displacing repetitive bagging tasks can materially shorten order cycle times while reducing reliance on expensive temporary labor pools.
- Raw material and input cost exposure: stainless steel remains a significant bill-of-materials component for machines and frames. For example, China FOB stainless steel prices were around USD 2,082 per metric ton in March 2026—an input cost signal that buyers and OEMs must hedge via long‑lead purchasing, alternative sourcing or design substitutions where appropriate.
- E‑commerce and fulfillment demand: sustained growth in online order volumes increases demand for flexible, high‑speed bagging solutions capable of handling variable SKUs, bespoke pack‑ins and integrated labelling/printing functions.
Beyond these core vectors, organizations should consider lifecycle support economics, software and automation platform compatibility, and sustainability signals—particularly the move toward recyclable and reduced‑film packaging formats—which will shape retrofit and replacement cycles.
Competitive landscape: vendor positioning and strategic implications
The market is neither fully fragmented nor highly consolidated—our concentration metrics indicate a market where a small group of suppliers hold meaningful share but competition from specialist and regional OEMs remains fierce. Specifically, the combined share of the three largest suppliers (CR3) sits at approximately 38.5%, while the top five (CR5) account for about 52.2%.
Key vendor archetypes and what they imply for buyers:
- Scale-oriented systems providers: Firms such as Sealed Air (AUTOBAG) offer high‑speed, scalable systems designed for throughput-centric operations. Their value proposition centers on end‑to‑end automation with strong service networks—an attractive choice for large fulfillment centers seeking aggressive OEE gains.
- E‑commerce and retail specialists: Pregis and PackSmart provide solutions optimized for variable‑size poly mailing envelopes and print‑on‑demand workflows, making them natural fits for omni‑channel fulfillment where order heterogeneity is high.
- Compact and tabletop innovators: PAC Machinery (Rollbag) and Advanced Poly‑Packaging specialize in space‑efficient tabletop and mid‑speed solutions—competitive where floor footprint and modular scalability are primary constraints.
- Vertical and bespoke solutions: Rennco’s vertical bagging systems and Tension Packaging’s variable‑length HPS offerings highlight the importance of matching machine orientation to product form factor and line architecture.
- European high‑speed and labelling integrators: Audion’s Speedpack series demonstrates the market’s emphasis on combined bagging-and‑labelling throughput for high‑volume, regulatory‑sensitive segments such as pharma and medical.
- Regional specialists and hybrid suppliers: Companies like WeighPack, Bagmatic and Impackt deliver specialized solutions for food, hardware and rapid‑pack operations, often combining mechanical simplicity with domain know‑how.
Recent vendor activity underlines the product cadence and go‑to‑market dynamics you should anticipate in 2026. For example, PAC Machinery showcased the Rollbag R785 tabletop poly bagger with thermal print integration at Pack Expo Southeast (exhibited March 2025), while Rennco unveiled an electric EZ20 vertical bagging solution at PACK EXPO International in late 2024—signals of continued product refresh and trade‑show led demand stimulation.
Strategic playbook: five actions for 2026 leaders
- Prioritize modularity and software openness. Choose systems that support incremental automation lifts and open interfaces to WMS/TMS, enabling phased ROI capture while preserving optionality for future upgrades.
- Embed raw‑material and supply‑chain hedges in contracts. Given stainless steel cost volatility, include price escalation clauses, multi‑sourcing commitments and strategic safety stock for critical spare parts.
- Run short, outcome‑driven pilots. Execute two‑quarter pilots that measure throughput per labor hour, downtime, and integration complexity. Use these pilots to refine scope before committing to multi‑site rollouts.
- Design procurement around lifecycle economics, not just sticker price. Factor in spare‑parts velocity, local field service availability, and software subscription models when calculating total cost of ownership.
- Prepare for consolidation and M&A. With the market’s mid‑range concentration, OEMs with proven service footprints or software differentiation will be attractive acquisition targets—buy‑side teams should be ready with diligence frameworks focused on recurring revenue and installed base analytics.
Where PW Consulting adds unique value
Our report blends empirical market sizing (with a detailed topline that shows growth from USD 345.12 Million in 2020 to an estimated USD 478.45 Million in 2025, and modeled expansion to USD 724.18 Million by 2032 at a 6.12% CAGR for 2026–2032) with executable procurement templates, vendor scorecards and scenario playbooks. Crucially, the deliverable is crafted to be actionable for 2026 budgets—linking strategy to spreadsheets and pilots so that decisions can be executed within the current fiscal cycle.
To preserve commercial value for clients and to encourage direct engagement, the report summary intentionally omits granular regional and application revenue splits and other proprietary sub‑segment tables. Subscribers and qualified enterprise clients can access the complete annexes, raw datasets, and vendor model comparisons via the PW Consulting research portal.
Next steps for executives
- Download the executive snapshot to compare our topline forecast and the vendor landscape against your current CapEx plan.
- Schedule a briefing with our industry analysts to walk through the buyer’s guide and test the TCO templates against your warehouse metrics.
- Commission a bespoke supplier‑selection engagement if you are planning multi‑site orchestration in 2026; our M&A and integration checklists will accelerate diligence and post‑deal value capture.
Automated poly bagging machines are no longer a peripheral investment. For organizations seeking durable gains in throughput, cost control and order accuracy, 2026 is a decisive year to act. PW Consulting’s Worldwide Automated Poly Bagging Machines Market report provides the market intelligence, commercial frameworks and tactical playbooks to make those decisions with confidence.
To access the full report, detailed annexes and interactive tools, visit the PW Consulting research portal or contact our industry practice team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Automated Poly Bagging Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com