

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Surging Demand: PW Consulting Forecasts 8.9% CAGR for Worldwide Traumatic Brain Injuries Assessment and Management Devices Market (2026–2032)

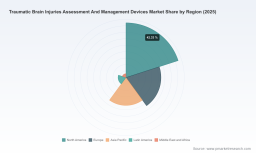
Worldwide Traumatic Brain Injuries Assessment And Management Devices Market: Strategic Imperatives for 2026
PW Consulting's latest market assessment — with a 2025 base year and a forecast horizon through 2032 — frames traumatic brain injuries (TBI) devices as a growth segment poised for continued expansion. Our model shows the market exhibiting a compound annual growth rate (CAGR) of 8.9% across the 2026–2032 forecast window, building on a multi‑year historical series. For executives deciding capital allocation, product roadmaps, or M&A targets in 2026, this report translates macro momentum into clear, actionable levers without disclosing the granular segment tabulations reserved for the full study.
Worldwide Traumatic Brain Injuries Assessment And Management Devices Market
Why 2026 Is a Pivotal Year for TBI Device Strategy
- Market momentum. The market’s trajectory entering 2026 reflects steady adoption of both point-of-care diagnostic tools and advanced neuromonitoring systems in acute and subacute care settings. The projected mid‑single-digit to high‑single-digit CAGR signals a mix of organic adoption and product-driven uptake.
- Regulatory and clinical inflection points. Between device clearances for bedside biomarker assays and the growing evidence base for brain tissue oxygen monitoring, 2025–2026 marked several regulatory and clinical milestones that will shape purchasing cycles and clinical protocols in the coming years.
- Strategic timing for investments. With an evolving payer/regulatory landscape and pockets of consolidation, 2026 represents an opportune window to lock in distribution agreements, accelerate field evidence generation, or pursue tuck‑in acquisitions that can be integrated quickly into hospital procurement pathways.
What the Report Delivers (Practical Content for Decision-Makers)
- Robust market sizing and scenario modeling grounded in a 2020–2025 historical series and a 2026–2032 forecast. Our models include base, upside, and downside scenarios informed by regulatory events, reimbursement trends, and clinical trial outcomes.
- Go‑to‑market playbooks for device manufacturers, segmented by product archetype (imaging, bedside monitoring, wearable/portable assessment). Each playbook provides field trial designs, payer engagement templates, and procurement negotiation levers tailored to hospitals and diagnostic centers.
- Demand‑side adoption curves and clinician acceptance maps that identify the fastest adoption clusters and friction points in decision workflows inside emergency departments, neuro ICUs, and outpatient concussion clinics.
- Regulatory and reimbursement trackers: timelines, likely accelerants (e.g., breakthrough designations), and potential barriers, with recommended regulatory strategies for submission, labeling, and claims language for biomarker and neuromonitoring tools.
- Vendor benchmarking and technology scorecards that synthesize performance, evidence depth, commercialization maturity, and integration complexity to support partnering and M&A diligence.
- Commercial scenarios and valuation impact analysis for transactions, including sensitivity tables that translate shifts in adoption rates or reimbursement into revenue and EBITDA outcomes.
Competitive Landscape — What We Found and Why It Matters
The competitive environment is a mix of established medtech incumbents and agile specialty innovators. Market concentration is meaningful: the top three players account for a sizeable portion of the market, with the top five extending that share further — a structure that favors strategic partnerships for challengers and tuck‑ins for consolidators. Below we summarize the roles and strategic postures of core players analyzed in the report.
Worldwide Traumatic Brain Injuries Assessment And Management Devices Market
- BrainScope Company Inc. — An early mover in EEG‑based, point‑of‑care concussion assessment. BrainScope’s handheld, AI‑enabled platform positions the company at the intersection of prehospital and emergency department triage, with strengths in rapid decision support and low operational friction.
- Abbott Laboratories — With blood‑based TBI biomarker assays cleared for bedside use, Abbott occupies a critical adjacencies role between laboratory diagnostics and point‑of‑care assessment. These assays are explicitly indicated as aids to clinical evaluation — a nuance that shapes payer conversations and clinician adoption.
- Integra LifeSciences and RAUMEDIC AG — Both offer core neurocritical care monitoring systems (intracranial pressure, brain tissue oxygen). Their product suites are entrenched in neuro ICU workflows and surgical pathways, where device compatibility and long clinical lifecycles determine procurement decisions.
- Major imaging and critical care vendors (Philips, GE HealthCare, Elekta) — These incumbents leverage imaging and integrated monitoring platforms to sell end‑to‑end neuro‑ICU solutions. Their competitive advantage is systems integration, enterprise contracting, and installed base leverage.
- Niche innovators (InfraScan, Oculogica, SyncThink, Headsafe) — Focused on rapid hematoma detection, eye‑tracking, or portable EEG, these companies are advancing lower‑cost, high‑speed triage tools. Recent regulatory clearances and U.S. market entries have elevated their strategic relevance to EMS systems and sports medicine networks.
- Neurodiagnostic specialists (Natus, Compumedics, Nihon Kohden, Advanced Brain Monitoring) — These firms provide EEG and neuromonitoring platforms widely used in both acute care and rehabilitation settings. Their differentiator is clinical depth and product adaptability across care phases.
Collectively, this mix of players creates a two‑tier competitive dynamic: large platform vendors compete for enterprise share and integration mandates, while focused innovators compete on speed, cost, and specific clinical use cases. The balance between these tiers will determine pricing and procurement negotiations through 2026 and beyond.
Worldwide Traumatic Brain Injuries Assessment And Management Devices Market
Regulatory, Clinical and Reimbursement Signals to Watch in 2026
- Regulatory approvals and designations. Breakthrough device designations and additional 510(k) clearances materially influence adoption speed; sponsors should prioritize pre‑submission engagement and real‑world evidence strategies to shorten commercialization lead times.
- Emerging clinical evidence. Results from trials and meta‑analyses — for example, studies on adjunctive brain tissue oxygen monitoring — will be decisive in shaping guideline updates and ICU practice patterns. Manufacturers must plan post‑market studies aligned with endpoints that payers and guideline committees value.
- Payer behavior and procedural economics. Historical trends demonstrate modest, sometimes negative, real‑term reimbursement pressure on certain neurosurgical procedures. Companies should construct reimbursement playbooks that emphasize downstream cost avoidance, reduced admissions, and clear patient‑flow benefits.
- Military and occupational adoption. Departments of Defense and large employers can accelerate volume adoption for select technologies; engagement with these channels remains a high‑leverage pathway to scale for devices that demonstrate field utility.
Actionable Recommendations for 2026 Executives
- Prioritize portfolio moves that reduce time‑to‑value. Consider licensing partnerships or targeted acquisitions for technologies that close key gaps in triage-to‑ICU pathways (e.g., rapid biomarker assays, portable EEG/NIRS devices).
- Invest in pragmatic evidence generation. Short, well‑designed real‑world studies demonstrating ED throughput improvements, reduced imaging utilization, or ICU outcome benefits will unlock payer and hospital buying committees.
- Tailor commercialization models to buyer economics. For hospitals and diagnostic centers, emphasize integration, service contracts, and total cost of ownership. For point‑of‑care diagnostics, prioritize channel partnerships with EMS and occupational health networks.
- Hedge regulatory and reimbursement risks. Allocate resources for post‑market surveillance, labeling updates, and health economics dossiers to support coding and coverage discussions.
- Monitor consolidation opportunities. With a mid‑to‑high level of market concentration, 2026 is a window where strategic divestitures and tuck‑ins can shift competitive dynamics; maintain an M&A scorecard that scores targets on revenue synergies, clinical evidence, and integration complexity.
Methodology and Confidence
PW Consulting’s assessment triangulates proprietary surveys of health‑system procurement leaders, device shipment and revenue tracking, regulatory filings, clinical literature review, and interviews with key opinion leaders. The base year is 2025 and historical inputs span 2020–2025; forward projections run to 2032 and incorporate multiple scenarios. We provide probability‑weighted forecasts and sensitivity analyses in the full report. Note: while this press summary highlights high‑level growth and competitive dynamics, we intentionally withhold detailed segment and regional breakdowns here to preserve the value of the full report.
Next Steps and How the Report Supports 2026 Decision-Making
- Download the full study for complete segmented forecasts, country‑level models, cost‑benefit case templates for purchasers, and vendor scorecards that quantify technical and commercial readiness.
- Engage our team for a tailored executive briefing: we provide custom scenario runs (e.g., accelerated biomarker uptake, delayed reimbursement approvals) that map directly to your investment and go‑to‑market choices.
- Use our M&A diligence addendum to stress‑test potential deals against clinic adoption curves and payer sensitivity analyses.
PW Consulting’s Worldwide Traumatic Brain Injuries Assessment And Management Devices Market report equips leaders with the market context, competitive intelligence, and pragmatic tools needed to make decisive investments in 2026. For access to the full dataset, detailed segment and regional forecasts, and executable playbooks, visit PW Consulting’s report page or contact our neurotech practice for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Traumatic Brain Injuries Assessment And Management Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com