

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Ultra‑Long Endurance UAV Market Set to More Than Double — From USD 3.45 Billion in 2025 to USD 7.70 Billion by 2032 at a 12.15% CAGR, Led by HALE and Internal Combustion Platforms

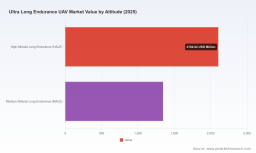
Worldwide Ultra Long Endurance UAV Market: Strategic Outlook for 2026 Decision-Making
PW Consulting’s new market study on the Worldwide Ultra Long Endurance (ULE) UAV market synthesizes five years of historical tracking and a seven-year forward-looking forecast to equip executives with the intelligence needed to make decisive investments in 2026. Anchored on a 2025 base year analysis, the ULE UAV ecosystem has grown from under USD 2.0 billion in 2020 to an estimated USD 3.45 billion in 2025, and our structured forecast projects the market to more than double by 2032, reaching approximately USD 7.7 billion—a compound annual growth rate (CAGR) of 12.15% across the 2026–2032 forecast horizon. This trajectory, combined with rising strategic demand for persistent ISR, communications relay, and long-duration science missions, makes 2026 a pivotal year for procurement, partnership formation, and capability scaling.
Worldwide Ultra Long Endurance UAV Market
Why 2026 Is an Inflection Point
-
Commercial entry and regulatory momentum. Several stratospheric and high-endurance platforms have reached consecutive demonstration milestones and are moving toward commercial entry-to-service. These progressions compress the window for early-adopter advantage in commercial HAPS and persistent ULE services.
Worldwide Ultra Long Endurance UAV Market -
Technology convergence. Breakthroughs in battery chemistry (notably high-energy-density silicon-anode cells), lightweight composites, and autonomous flight controls are shifting the value equation for endurance vs. payload and operational cost. The rapid maturation of these subsystems lowers technical risk but raises the strategic value of timely supplier selection and integration planning.
Worldwide Ultra Long Endurance UAV Market -
Operational demand and new mission classes. Defense, maritime, and telecom customers are recalibrating requirements toward uninterrupted persistence and lower total cost of ownership. This stimulates procurement cycles and creates new commercial demand segments for connectivity-as-a-service and extended environmental monitoring.
What the Report Delivers: Actionable Intelligence, Not Just Forecasts
The PW Consulting report is structured as an operator’s playbook for boardrooms and program managers who need to move from strategic intent to executable plans in 2026. Core deliverables include:
-
Clear market sizing and trajectory—multi-year historical tracking and a rigorous forecast to 2032, enabling financial planning and investment gating aligned with a 12.15% CAGR scenario.
-
Scenario-based demand models—tailored to different adoption curves (conservative, base-case, accelerated commercialization) so procurement teams can stress-test program timelines and cashflow needs.
-
Technology and supplier roadmaps—practical guidance on component readiness, integration complexity, and recommended sourcing strategies for batteries, composites, propulsion, and payload suites.
-
Commercial go-to-market playbooks—pricing pressure points, service models (capex vs. opex), and recommended partnership archetypes for operators and service providers planning to monetize endurance platforms.
-
M&A and investment screening—compact diligence packs, valuation sensitivities, and candidate profiles that accelerate target assessment without exposing confidential models in preliminary conversations.
-
Regulatory and certification pathway maps—practical checklists and milestone calendars for HAPS, HALE, and Group 5 platforms, enabling policy-aware procurement and compliance sequencing.
-
Operational cost and TCO frameworks—models for life-cycle costing, maintenance planning, and mission-specific payload economics that executives can adapt to internal finance systems.
Competitive Landscape: Who Is Shaping Persistence and How
Market concentration remains moderate: the top three vendors account for a meaningful share of vendor revenues and capability leadership, with a five-firm concentration that underscores clear leader clusters. Our qualitative and quantitative competitive workbench profiles platform OEMs, systems integrators, and niche technology suppliers to illustrate where differentiation is happening.
-
Platform Aerospace (United States) has proven long-endurance Group 3 capabilities and emphasizes flexible ISR, EW, and airborne logistics payload support—appealing to customers seeking rapid operational deployment with proven endurance records.
-
DZYNE Technologies (United States) is advancing high-altitude Group 5 endurance benchmarks with recent mission-representative flight tests that demonstrate exceptional persistence at operational altitudes, signaling a shift in what operators can expect from Group 5 platforms.
-
AALTO HAPS (Airbus subsidiary) (UK) has turned experimental stratospheric flights into a near-commercial offering, validating continuous multi-week operations and direct-to-device connectivity payloads—creating new competitive dynamics with terrestrial and satellite networks.
-
Skydweller Aero (US/Spain) is pushing the boundaries of solar-electric scale platforms—autonomy and composite manufacturing choices there are a bellwether for maritime patrol and wide-area surveillance services that require weeks-to-months endurance.
-
Established defense primes— General Atomics Aeronautical Systems , Northrop Grumman , Israel Aerospace Industries , Elbit Systems , and AeroVironment —continue to anchor persistent ISR and tactical endurance markets with deep integration, sustainment, and customer relationships that make them preferred partners for mission-critical programs.
Recent public demonstrations underscore how quickly mission expectations are evolving: a leading HAPS developer recorded a continuous stratospheric flight exceeding two months in 2025, another contender completed multi-day naval-oriented demonstrations, and a Group 5 contender achieved a 60-hour sortie at high altitude in early 2026. These milestones are more than PR—they materially shift procurement tolerances for endurance, autonomy, and payload energy budgets.
Strategic Imperatives for Executives in 2026
-
Accelerate supplier qualification for battery and composite suppliers. The marginal gains in energy density and structural efficiency are the difference between multi-day and multi-week persistence—lock in test slots and conditional supply agreements now.
-
Re-evaluate mission architectures for hybrid persistence. Combining HAPS, HALE, MALE, and Group 3/5 assets in layered architectures reduces single-platform risk while enabling new service profiles for comms and ISR.
-
Capitalize on early commercial pathways. Where regulatory calendars indicate 2026 entry-to-service possibilities, prioritize pilot commercial contracts and JV structures that de-risk go-to-market sequencing and spectrum access.
-
Build optionality into procurement contracts. Award structures that include performance-based milestones, modular payload interfaces, and scale discounts preserve flexibility as technology curves accelerate.
-
Use M&A selectively to acquire missing capabilities (autonomy stacks, powertrain tech, or proven operational datasets) rather than duplicating long development timelines in-house.
Risks & Leading Indicators to Monitor
-
Supply-chain concentration for critical materials (battery feedstocks, carbon-fiber precursors) can create schedule slippage—track certification of alternative suppliers and inventory-to-delivery lead times as early warning signals.
-
Regulatory timelines and airspace integration remain fluid across jurisdictions—watch civil certification decisions and spectrum allocation rulings as triggers for commercial scalability.
-
Operational interoperability—standards for payload interfaces, data formats, and command-and-control chains will determine how easily mixed fleets can be fielded; early alignment pays dividends.
-
Geopolitical and export-control shifts can rapidly alter supplier choices and market access; scenario planning is essential to hedge program-level exposure.
How PW Consulting Helps Executives Move from Insight to Impact
Our report combines quantitative models, primary interviews, and systems-level analysis into a compact set of deliverables tailored for 2026 decision cycles: executive briefing decks, board-level scenario maps, procurement clause templates, supplier scorecards, and bespoke financial models that plug directly into capital planning systems. For organizations not ready to commit to full teams, we offer strategic accelerators—workshops, rapid due-diligence sprints, and integration playbooks—that reduce time-to-decision while preserving optionality for disruptive developments.
PW Consulting’s approach follows a strict “trailer” principle: we show the analytics, modeling logic, and executive-grade recommendations that give immediate strategic value, while the full granular segment-level datasets, vendor revenue splits, and downloadable financial models remain available in the complete report package and supporting data annexes. This balance preserves competitive advantage for subscribers while enabling an actionable executive summary for quick decision cycles.
Next Steps
-
Procurement and corporate development leaders should schedule a strategic review in Q1–Q2 2026 to align CapEx and partnership roadmaps with operational milestones for HAPS and Group 5 commercialization.
-
R&D and supply chain teams should initiate supplier qualification pilots focused on batteries and composite assemblies to secure manufacturing lead times aligned to forecast demand peaks.
-
Business leaders should request PW Consulting’s executive briefing package and scenario models to stress-test internal plans against the market trajectories and regulatory milestones described above.
For a full breakdown of segment-level forecasts, vendor share models, and the operational templates referenced here, visit the PW Consulting report page to access the complete Worldwide Ultra Long Endurance UAV Market report and supporting data annexes. The 2026 decision window is short—corporate advantage will accrue to organizations that pair strategic clarity with rapid execution.
For detailed analysis of this topic, please visit the official page: Worldwide Ultra Long Endurance UAV Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com