

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Medical Dynamometer Market to Expand at a 6.6% CAGR, Cross USD 1.13 Billion by 2032

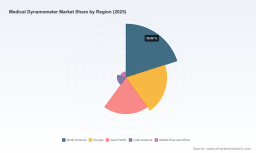
Worldwide Medical Dynamometer Market: Strategic Preview for 2026 Decision-Making
PW Consulting today releases an executive preview of our forthcoming Worldwide Medical Dynamometer Market study — a practical, strategy-focused intelligence product that equips medical-device executives, investors, and health system procurement leaders to make confident 2026 choices. The market for medical dynamometers is sizeable and resilient: our modeling shows the global market reached USD 725.5 Million (base year 2025) after a steady recovery from the pandemic period, and is projected to expand at a compound annual growth rate (CAGR) of 6.6% through the 2026–2032 forecast window, arriving at roughly USD 1,134.8 Million by 2032. This preview summarizes the strategic takeaways, competitive dynamics, regulatory considerations, and the actionable modules included in the full report — while reserving granular regional and segment tables for subscribers.
Worldwide Medical Dynamometer Market
Why this report matters for 2026 strategy
Medical dynamometers — devices used to quantify muscle strength, grip, push/pull force, and isokinetic performance — are moving from niche clinical tools toward integrated components of evidence-based rehabilitation, sports performance programs, and value-based musculoskeletal care pathways. As hospitals, physiotherapy networks, and occupational medicine providers face pressure to demonstrate objective outcomes, demand for reliable, interoperable strength-assessment tools has risen. For companies operating in this space, 2026 will be a pivotal year to convert product innovation into durable commercial advantage. Our research has been designed to reduce execution risk across three common 2026 decision themes:
Worldwide Medical Dynamometer Market
- Market entry and prioritization: where to allocate R&D and sales resources without over-committing to small, volatile pockets of demand.
- M&A and partnership screening: which product capabilities, regulatory clearances, or channel relationships produce outsized valuation multiples in a moderately concentrated market.
- Commercial model redesign: how to transition from transactional device sales to service-, software-, or outcome-linked offerings that improve stickiness with clinicians and payers.
What the market structure tells executives
Two macro characteristics define the competitive environment. First, the market exhibits moderate concentration: the top three manufacturers account for approximately 35% of revenue, and a top-five cluster reaches just over half of the market. This creates room for specialist challengers and regional players to scale with focused product differentiation or strong channel agreements. Second, growth is steady and predictable (CAGR 6.6% in our forecast period), enabling disciplined multi-year planning for capacity, regulatory investment, and software development.
Worldwide Medical Dynamometer Market
From a product perspective, hand-held grip dynamometers remain a leading category in clinical adoption due to low cost, ease of use, and strong clinical utility in primary rehabilitation settings. Meanwhile, isokinetic systems and integrated software-enabled platforms command higher ASPs and stronger ties to high-acuity sports and hospital markets. These dynamics create a two-tier opportunity: high-volume, competitively priced devices and premium systems that can anchor service contracts and data monetization strategies.
Competitive landscape — strengths, gaps, and tactical moves
Our competitive analysis profiles incumbents, scale challengers, and high-velocity start-ups. Key patterns and strategic implications include:
- Established diagnostics and rehab OEMs (for example, manufacturers with long histories in grip and isokinetic testing) leverage brand trust and distribution with clinics and hospitals. Their advantages include regulatory experience, product reliability, and existing procurement relationships.
- Regional players and CE-marked suppliers compete strongly in price-sensitive procurement environments. They may lack broad regulatory clearances in every market, but they are agile in customization and localized service.
Representative vendor developments illustrate these trends. Recent certification and warranty enhancements by a leading U.S. specialist reinforced trust for institutional buyers, while product upgrades adding wireless accessories demonstrate how modular connectivity is becoming table stakes. Another established U.S. manufacturer launched a redesigned dual-handle dynamometer with improved ergonomics and app integration early in 2026 — a clear signal that incumbents are moving to blend hardware improvements with software-enabled clinician workflows.
Regulatory, reimbursement and quality imperatives
Regulatory and reimbursement frameworks will shape go-to-market timelines in 2026. Key considerations covered in the report include:
- Device classification: many electronic dynamometers fall under FDA product codes that frequently require 510(k) submissions (Class II) in the United States; others — particularly simple mechanical devices — may be Class I in certain circumstances. CE marking and national conformity requirements continue to be gatekeepers for European and several APAC markets.
- Quality systems: ISO 13485-compliant design and manufacturing processes remain a near-universal buyer expectation for clinical customers and an essential prerequisite for many procurement tenders.
- Reimbursement context: muscle testing and functional performance measures are often documented within accepted CPT and billing frameworks. Facilities frequently rely on combinations of range-of-motion and functional codes when documenting assessments that rely on dynamometer data; understanding the tight linkage between documentation practices and reimbursement is crucial for positioning value-added services.
For device manufacturers, these realities imply that regulatory strategy, product documentation, clinical validation, and payer engagement must be executed in parallel — not sequentially — to unlock institutional procurements in 2026.
Commercial and product priorities for 2026
Our client workshops and primary interviews reveal that high-impact investments fall into four pragmatic buckets:
- Interoperability and software: Buyers increasingly demand devices that feed into electronic medical records, rehab platforms, or athlete-management systems. Vendors who deliver secure APIs and validated data pipelines will shorten sales cycles.
- Clinical evidence and outcomes linkage: Prospective validation studies that demonstrate how dynamometer-driven interventions change rehabilitation timelines or return-to-play outcomes materially improve payer and hospital receptivity.
- Service and warranty models: Extended warranties, device-as-a-service offers, and outcome-linked pricing reduce procurement friction in capital-constrained systems.
- Channel partnerships: Distributors with therapeutic-device expertise and established relationships with physiotherapy networks can deliver rapid penetration in 2026 if partnered early and aligned on training and reimbursement messaging.
Actionable modules inside the full PW Consulting study
The full report — designed as an execution toolkit — includes the following operational modules (subscriber content):
- Financial model and scenario engine: customizable forecasts, sensitivity testing for ASP, unit volumes, and regional rollout pacing to support board-level investment decisions.
- Commercial playbooks: tailored GTM templates for OEMs targeting hospitals, physiotherapy chains, and elite sports organizations.
- Regulatory pathway tracker: jurisdiction-by-jurisdiction guidance for FDA 510(k) or CE technical dossiers, typical timelines, and resourcing estimates.
- Competitive scorecards: validated product feature comparisons, pricing bands, and service benchmarks to streamline acquisition screening and partnership due diligence.
- Clinical evidence map: summary of key studies tying dynamometer use to clinical outcomes, with gap analysis and trial design templates for vendors seeking rapid evidence generation.
These modules are intentionally practical — delivering templates, checklists, and vendor-neutral negotiation points that teams can implement immediately in 2026 planning cycles.
How PE investors and acquirers should read the market in 2026
For private equity and strategic acquirers, the market’s moderate concentration, recurring clinical demand, and visible upgrade path to software-linked offerings create an attractive risk-reward profile. Targets with validated regulatory clearances, differentiated sensor or software IP, and recurring revenue from service or analytics contracts typically command a premium. Our M&A playbook emphasizes three levers for value creation: consolidate complementary regional suppliers to achieve scale, integrate analytics platforms to increase customer lifetime value, and pursue bolt-on acquisitions that close feature gaps (e.g., connectivity or isokinetic capability).
Next steps — where to get the full intelligence
This preview is intended to demonstrate the depth and actionability of the full PW Consulting Worldwide Medical Dynamometer Market report. The complete publication contains the segmented regional and application-level demand models, manufacturer revenue matrices, pricing benchmarks, and downloadable financial models that underpin the headline projections summarized here. Those granular datasets and scenario runs are available exclusively through the report portal; visiting the report page will also provide access to bespoke briefing sessions and model licensing for corporate planning.
To proceed with a briefing, model license, or tailored advisory engagement that applies these findings to your 2026 planning, please visit our report page or contact PW Consulting’s medical devices practice. Our team combines industry-grade market models, regulatory expertise, and M&A playbooks to help clients translate the market’s 6.6% projected growth trajectory into defensible competitive advantage.
Closing perspective
Medical dynamometers occupy a pragmatic but strategically meaningful niche at the intersection of rehabilitation, sports performance, and outcome-driven care. The market’s steady compound growth and moderate concentration afford incumbents the ability to defend core niches while enabling new entrants to scale through targeted innovation. In 2026, the companies that pair reliable hardware with validated software workflows, regulatory rigor, and creative commercial models will capture the disproportionate upside. PW Consulting’s full study provides the worksheets, regulatory maps, and go-to-market prescriptions that teams need to act with confidence — while the detailed segment tables and scenario models remain available on our report page for subscribers and clients.
For detailed analysis of this topic, please visit the official page: Worldwide Medical Dynamometer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com