

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Benign Positional Vertigo Treatment Market to Climb from USD 989.49 Million in 2025 to USD 1,427.97 Million by 2032 at a 5.38% CAGR

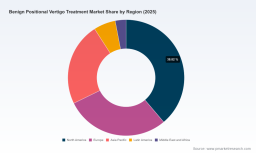
Worldwide Benign Positional Vertigo (BPPV) Treatment Market — Strategic Preview for 2026 Decisions
PW Consulting’s newest market study, "Worldwide Benign Positional Vertigo Treatment Market," equips executives, investors, and clinical leaders with the actionable intelligence required to make decisive moves in 2026. Built on a robust base year of 2025, the report synthesizes five years of historical data (2020–2025) and a forward-looking forecast for 2026–2032. Our modeling shows the global market approaching USD 989.5 Million (revenue unit: Million) in 2025 and accelerating to approximately USD 1.43 Billion by 2032—a trajectory that corresponds to a compound annual growth rate (CAGR) of 5.38% across the forecast horizon.
Worldwide Benign Positional Vertigo Treatment Market
Why this study matters for 2026
-
Timing: 2026 is a pivotal year for product launches, reimbursement negotiations, and consolidation activity in the vestibular care ecosystem. Our forecast and scenario analysis identify the inflection points that will determine winners and laggards.
Worldwide Benign Positional Vertigo Treatment Market -
Capital allocation: With mid-single-digit growth and identifiable pockets of faster expansion, this market is capital-efficient yet sensitive to regulatory and supply shocks. The report translates market growth into investment priorities across R&D, M&A, and commercial expansion.
Worldwide Benign Positional Vertigo Treatment Market -
Operational risk mitigation: Raw-material and labor-cost pressures create discrete operational risks. We provide pragmatic mitigation playbooks that can be executed within 6–12 months to protect margins.
Key takeaways for executives
-
Market trajectory: From a base near USD 989.5M in 2025, the market is projected to expand materially through 2032, offering sustainable tailwinds for diagnostic platforms, repositioning device makers, and ambulatory service providers.
-
Concentration and competition: The market demonstrates moderate concentration—our CR3 and CR5 metrics indicate leading players hold meaningful but not dominant shares, leaving room for nimble entrants and specialist carve-outs to scale rapidly through differentiation.
-
Regulatory and reimbursement levers: Regulatory classification and reimbursement codes are decisive commercial levers. The U.S. FDA’s Class II/510(k) pathway dominates device clearance planning, while payor-level reimbursement (for example, Medicare coverage patterns) materially influences adoption economics in ambulatory settings.
-
Supply-chain fragility: Component-level supply constraints—particularly in polymer resins that affect medical-grade silicone pricing—are already compressing margins. We quantify the likely cost-pass dynamics and outline procurement strategies to stabilize input costs.
-
Clinical evidence as a market-maker: With no approved systemic drug therapies for BPPV, procedural and device-based interventions remain the commercial frontier. Competitive advantage will accrue to companies that pair robust clinical outcomes data with optimized reimbursement pathways.
Report structure — what you’ll find inside
-
Comprehensive market model: Bottom-up revenue modeling for 2020–2032, sensitivity scenarios (conservative, base, accelerated), and explicit assumptions so clients can re-weight forecasts to their strategic views.
-
Segment playbooks (actionable, non-proprietary): Strategic options by treatment type and end-user setting, including go-to-market templates, pricing archetypes, and customer journey maps for hospitals, clinics, and home-care channels.
-
Regulatory and reimbursement map: Country- and region-level clearance pathways, typical time-to-market estimates, and reimbursement benchmarks—critical for designing 2026 regulatory submissions and payer engagement plans.
-
Supply-chain and cost-sensitivity analysis: A supplier risk heatmap focused on polymer resins and other constrained inputs, contingency procurement strategies, and scenario-based margin modeling.
-
Competitive intelligence dossiers: Company profiles, product roadmaps, M&A watchlist, and capability-gap analyses for the key players shaping the market.
-
Strategic imperatives and KPIs: A prioritized set of 12-month and 36-month actions, and the KPIs investors and operators should track to validate strategic hypotheses in 2026.
Competitive landscape — who to watch in 2026
The report provides granular, executive-ready profiles of leading firms that many clients will encounter in partnership, procurement, or M&A discussions. Below are the high-level profiles and the strategic signals we are tracking:
-
Entellus Medical (now Stryker) — Plymouth, MN, USA ( https://www.stryker.com/ent): A leader in minimally invasive ENT systems. Recent product updates enhance navigation capabilities—an important differentiator when procedural precision affects clinical outcomes and reimbursement acceptance.
-
Interacoustics — Middelfart, Denmark ( https://www.interacoustics.com): A primary provider of repositioning chairs and diagnostic goggles. Certification updates and renewed conformity marks materially improve adoption in regulated markets with strict safety requirements.
-
Natus Medical (now Natus Neurology) — Middleton, WI, USA ( https://natus.com): Known for vHIT and videonystagmography systems; next-generation diagnostic platforms sharpen diagnostic throughput and reduce false positives—key for scaling clinic workflows.
-
Bernafon (WS Audiology) — Bern, Switzerland ( https://www.bernafon.com): Focused on vestibular testing and rehabilitation devices; their rehabilitation ecosystem approach can drive longer patient lifetime value through bundled services.
-
Beurer GmbH — Ulm, Germany ( https://www.beurer.com): A strong player in home-use maneuver devices and kits—one to watch as telehealth and home-care reimbursement models evolve.
Recent corporate developments—product updates, certification renewals, and next-gen launches—underscore a market where incremental product differentiation and regulatory validation translate into measurable commercial benefits. Our competitive matrices in the report quantify these advantages against adoption and reimbursement timelines.
Industry dynamics that will steer 2026 playbooks
-
Regulatory pathways: Devices for BPPV are predominantly Class II under U.S. regulation and commonly follow a 510(k) clearance route. This informs development timelines, clinical study design, and competitive entry points.
-
Reimbursement realities: Medicare and other major payors set a commercial tone—CPT-level reimbursement for canalith repositioning procedures materially affects how providers price and adopt adjunct technologies. Understanding these schedules is essential when constructing value propositions for hospitals and ambulatory centers.
-
Input-cost pressures: Medical-grade silicone has faced a 15–20% price increase in recent cycles owing to polymer resin constraints, impacting both device manufacturers and private-label producers. Manufacturers must decide whether to absorb, pass through, or redesign to alternative materials.
-
Labor economics: Procedure-level clinician reimbursement varies by market and setting, and in certain ambulatory contexts provider fees can represent a large fraction of the delivered-cost base. Optimizing device workflows to reduce chair time is therefore a high-ROI product feature.
-
Clinical standards: With no systemic pharmacotherapy approved for BPPV, protocol-driven physical maneuvers and diagnostic verification remain the clinical standard. This central fact focuses R&D and commercial efforts on devices, diagnostics, and rehab services rather than pharmaceutical pipelines.
Where to focus investment and action in 2026
-
Diagnostics-first strategies: Investing in precise, workflow-integrated diagnostics will pay off because better diagnostics accelerate case identification, improve conversion to therapy, and support premium pricing for interoperable systems.
-
Home-care and tele-rehab enablement: Design home-oriented, clinician-supervised solutions that can be billed under evolving telemedicine codes. Home devices lower unit economics for recurrent care and broaden addressable markets.
-
Regulatory acceleration: Prepare 510(k) dossiers and CE technical files in 2026 to capitalize on nearby reimbursement windows. Prioritize clinical endpoints that payors recognize as cost-saving or quality-improving.
-
Supply-chain resilience: Secure tiered sourcing contracts for critical polymers, invest in material-substitution R&D, and pre-negotiate index-linked price clauses to stabilize 2026 margins.
-
M&A and partnerships: Look for tuck-in diagnostic or software-enabled rehabilitation assets that complement existing device portfolios and help bridge fragmentation without the need for large greenfield investments.
How PW Consulting helps
Our report is not an academic exercise. It is a practitioner’s playbook built to be executable in 90–180 days. Clients receive the full market model, scenario workbooks, a supplier risk heatmap, reimbursement playbooks, and tailored recommendations tied to specific investment horizons (12, 24, 36 months). For boards and corporate development teams, we provide shortlist targets and valuation frameworks that reflect market concentration dynamics and forecasted growth rates.
Next steps
This preview highlights the strategic dimensions that will determine success in 2026 and beyond—market trajectory, competitive moves, regulatory inflection points, and operational risks. For the full dataset, proprietary segment detail, product-level revenue splits, and client-ready strategy decks, please consult the complete PW Consulting report. The full study contains the granular insights and plug-and-play tools your executive team needs to translate market trends into profitable action.
For detailed analysis of this topic, please visit the official page: Worldwide Benign Positional Vertigo Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com