

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 4.9% CAGR for Worldwide Food‑Grade Polyvinyl Acetate Market Through 2032

Worldwide Polyvinyl Acetate (Food Grade) Market — Strategic Preview for 2026 Decision-Makers
As companies prepare strategy for 2026, the food‑grade polyvinyl acetate (PVAc) market is transitioning from recovery into a period of steady growth and strategic consolidation. PW Consulting’s latest market study — covering 2020–2025 historicals and a 2026–2032 forecast horizon — projects a compound annual growth rate (CAGR) of 4.9% and models the total market expanding from the mid‑2025 base to meaningful scale by 2032. This briefing synthesizes the operational, regulatory and competitive intelligence executives need to prioritize capital allocation, manage cost exposure and capture differentiated value without revealing the full segment-level breakdown contained in the full report.
Worldwide Polyvinyl Acetate (Food Grade) Market
Market snapshot: resilient, concentrated and predictable
The food‑grade PVAc market experienced a period of volatility in the early 2020s before returning to a growth trajectory. From a PW Consulting base of record for 2025, the forecast through 2032 assumes normalized demand recovery across core food applications, steady improvements in manufacturing efficiencies, and a moderate raw‑material cost trajectory. Our model yields a mid‑single digit CAGR (4.9%) to 2032, reflecting both structural demand drivers and a market that remains meaningfully concentrated among a few large specialty suppliers.
Worldwide Polyvinyl Acetate (Food Grade) Market
- Concentration dynamics: The market exhibits a high degree of supplier concentration; the top three and top five firms together account for a majority share of supply, an important structural factor when evaluating supplier risk, negotiation strategy and potential M&A targets.
- Demand profile: End‑use traction continues to be dominated by established food‑contact formats, with incremental growth from adjacent coating and additive opportunities.
- Price sensitivity: Value captured across the chain is strongly linked to feedstock dynamics and operational flexibility at scale—two themes that will drive margin dispersion through 2026 and beyond.
Why this matters for 2026 corporate strategy
For food manufacturers, ingredient distributors and PVAc producers, 2026 will be a year to convert strategic intent into tangible positioning: secure resilient feedstock routes, prioritize supplier partnerships with certified food‑grade capacity, and decide whether to pursue vertical integration or flexible sourcing. Key considerations include:
Worldwide Polyvinyl Acetate (Food Grade) Market
- Supply resilience. Concentration among suppliers creates both negotiation leverage and single‑point risks. Buyers should stress‑test supply continuity scenarios and lock in contingency plans (dual sourcing, strategic inventories, or toll‑manufacturing arrangements).
- Feedstock exposure. Vinyl acetate monomer (VAM) remains the primary upstream input. Price and availability swings materially affect unit economics for PVAc. Companies that operationalize hedging, cost‑pass mechanisms or alternative feedstock strategies will protect margins more effectively.
- Regulatory posture. PVAc is explicitly listed in recognized food contact frameworks, which reduces technical regulatory risk but raises the bar for documented compliance. Expect customers and auditors to demand rigorous traceability, certifications and supplier auditability in 2026.
What the full report delivers — practical, transaction‑ready intelligence
PW Consulting’s full study is structured as a hands‑on decision tool rather than an academic exercise. The report combines quantitative forecasts with operational playbooks designed for executives who need to act in 2026. Highlights include:
- Scenario‑based demand models calibrated to macro drivers, end‑use adoption curves and feedstock price shock simulations.
- Supplier scorecards that benchmark technical capabilities, food‑grade certifications, geographic footprint and capacity flexibility — enabling rapid short‑listing for sourcing or partnership conversations.
- Margin sensitivity matrices linking VAM price movements and utilization assumptions to gross and EBITDA performance for typical PVAc production configurations.
- Regulatory compliance checklists and audit templates mapped to major food contact frameworks — useful for procurement, quality and regulatory teams preparing supplier DD or supplier onboarding.
- M&A and investment playbooks: valuation levers, integration risks and post‑close value capture options tailored to both strategic and financial buyers.
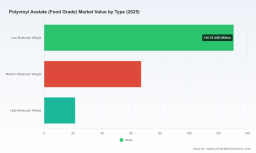
We deliberately withhold the detailed region‑ and application‑level splits in this preview; those segment tables, granular unit economics and transactional comparables are available only in the full report for subscribers and purchasers.
Competitive landscape — leaders, challengers and tailored responses
The supplier landscape is anchored by established specialty chemical firms and regional manufacturers that focus on food‑grade certifications and supply chain proximity. Key profiles inform strategic choices for buyers and potential acquirers:
- Wacker Chemie AG (Munich, Germany): A global player with dedicated food‑grade PVAc brands and a specialized production plant in Nanjing, China. Wacker’s portfolio strength and global reach make it a preferred strategic partner for multinational food manufacturers seeking scale, technical support and consistency.
- Nitchen New Material Co., Ltd. (China): A focused producer of certified food‑grade PVAc grades, marketed in granule and flake forms for gum base and other food contact applications. Its HACCP and Halal certifications position it well for manufacturers that prioritize compliance and value regional supply continuity.
- Jiangsu Yinyang Gumbase Materials Co., Ltd. (China): A producer oriented to chewing‑gum and related markets, offering manufacturing depth in established application niches.
- ElephChem Holding Limited (China): A versatile supplier with capabilities across PVAc grades and a pathway to service both food‑contact and adjacent industrial markets.
- Muby Chemicals / Aadhunik Industries (India): An exporter of regulatory‑compliant PVAc grades that can be an attractive second‑tier sourcing option for buyers balancing cost and compliance.
Strategic implications: large multinational buyers should secure long‑lead supply contracts or co‑development agreements with a global supplier for supply assurance, while regional, cost‑sensitive buyers may optimize by qualifying accredited local manufacturers and leveraging multi‑sourcing to reduce logistics and tariff exposure. Potential acquirers should evaluate targets not just on nameplate capacity but on certification breadth, traceability systems and proximity to critical food manufacturing clusters.
Raw materials, regulation and cost management — what to monitor in 2026
- VAM volatility. The market remains sensitive to upstream availability and regional differential pricing. Procurement teams should implement rolling exposure analysis and adopt flexible contracting terms to mitigate short, sharp price moves.
- Regulatory clarity as an advantage. PVAc’s inclusion in recognized food‑contact inventories and explicit listing in major food‑contact regulations reduces market friction for compliant suppliers. However, compliance is table stakes — buyers will reward suppliers who can demonstrate end‑to‑end traceability and third‑party certifications.
- Sustainability and disclosure. Buyers increasingly require lifecycle and sustainability data. Carbon intensity and solvent management in PVAc production are emerging negotiation points that can be converted into commercial differentiation with the right measurement and reporting systems.
Actionable playbook for 2026
Translate market insight into operational moves with a focused set of actions tailored around supply, cost, compliance and growth:
- Immediate (0–6 months): Conduct a supplier stress test focused on top three suppliers; qualify one alternative certified source; launch a VAM price‑exposure dashboard to inform purchasing cadence.
- Medium term (6–18 months): Negotiate multi‑year contracts with flexibility clauses linked to agreed price indices; pilot co‑development of application‑specific PVAc grades with strategic supplier partners; embed regulatory audit requirements into procurement contracts.
- Strategic (18–36 months): Evaluate bolt‑on acquisitions or minority investments in regional, certified players to secure capacity and technical know‑how; develop a sustainability roadmap for PVAc procurement tied to customer ESG requirements and potential cost incentives.
What’s not included here — and why you’ll want the full report
This preview intentionally omits the granular regional and application split tables, unit‑level price series, and the detailed supplier benchmarking matrices that underpin our valuations and scenario outputs. Those elements materially change negotiation posture and investment timing and are provided in the full PW Consulting study so that clients can base decisions on defensible, auditable data rather than directional insight alone.
Conclusion — positioning for distance and agility
Food‑grade PVAc in 2026 represents a market where structural fundamentals favor disciplined players: those who combine supply resilience, technical compliance and cost discipline will secure outsized returns in a concentrated market. The market’s mid‑single digit CAGR to 2032 provides predictability, but the path to capture margin is through operational rigor, selective partnerships and timely investment. PW Consulting’s full report provides the tactical tools — from sensitivity models to supplier scorecards — to convert strategic intent into measurable outcomes.
For executives building 2026 sourcing, product or M&A roadmaps, the full Worldwide Polyvinyl Acetate (Food Grade) Market report is the operational compass that connects high‑level trends to transaction‑grade decisions. Access the complete analysis, data tables and playbooks through PW Consulting’s report page.
For detailed analysis of this topic, please visit the official page: Worldwide Polyvinyl Acetate (Food Grade) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com