

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Market Insights: Smart Motorcycle Helmet with Heads-Up Display Market to Nearly Double—USD 385.0 Million in Base Year 2025 to USD 878.07 Million by 2032 at 12.5% CAGR; Europe (USD 135.95M), Full‑Face & Bluetooth Lead

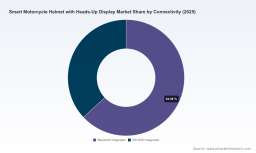
Smart Motorcycle Helmet with Heads-Up Display Market: Strategic Imperatives for 2026 Decision-Makers
PW Consulting’s latest market research on Smart Motorcycle Helmets with Heads-Up Displays (HUDs) synthesizes five years of historical evidence, current product dynamics, and a seven-year forecast to equip executives with the actionable intelligence they need for 2026. Our base-year analysis (2025) and forecast window (2026–2032) show a market that has moved beyond early experimentation into structured commercialisation—driven by rapid technology maturation, regulatory pressure on safety, and a converging supplier ecosystem. The global market reached approximately USD 385.0 million in 2025 and, at a compounded annual growth rate (CAGR) of 12.5%, is projected to approach the high hundreds of millions by the end of the forecast period. These headline figures are only the starting point: the strategic questions for 2026 are about how to capture share, de-risk product development, and build scalable go-to-market models in a market of rising concentration and technical complexity.
Smart Motorcycle Helmet with Heads-Up Display Market
Why this report matters for 2026 planning
-
Timing: 2026 is a critical inflection year. Product launches and pre-orders in late 2025 have shifted many initiatives from R&D pilots to full production planning and channel commitments. Our report isolates the decision levers that separate successful commercialization from costly setbacks.
Smart Motorcycle Helmet with Heads-Up Display Market -
Data-driven forecasting: By integrating historical performance (2020–2025) with component supply dynamics and adoption scenarios, the report provides demand curves, sensitivity analyses, and upside/downside cases to support capex and inventory planning.
Smart Motorcycle Helmet with Heads-Up Display Market -
Regulatory and standards alignment: New safety protocols—such as enhanced rotational impact testing requirements under ECE 22.06 and the ongoing obligations embedded in self-certification regimes like FMVSS No. 218—create both constraints and commercial advantages. The report evaluates compliance pathways and product design trade-offs for embedding electronics without compromising core protection.
-
Competitive playbook: We map incumbent helmet makers, HUD specialists, retrofitter suppliers, and electronics integrators—distilling each player’s capability stack and partnership logic to inform alliance and M&A decisions.
What’s inside the report (practical deliverables)
-
Market sizing and forecast models (2020–2032) with scenario sensitivity and breakouts by product archetype, channel, and business model—presented as downloadable models suitable for integration into financial planning systems.
-
Go-to-market playbooks for OEMs, aftermarket retrofit suppliers, Tier-1 electronics partners, and retail/channel partners—covering pricing strategies, warranty economics, and service networks.
-
Regulatory impact matrix and certification roadmaps—translated into product specification checklists and test sequencing to de-risk time-to-market.
-
Technology readiness assessments and component supply risk heatmaps (displays, optics, batteries, sensors, carbon-fiber shells), plus BOM-level margin modelling for sample platforms.
-
Competitive benchmarking and strategic options analysis for the leading vendors, including partnership maps, IP positioning, and suggested response strategies for incumbents and challengers.
-
Commercial scenarios for software and data monetization—HUD-enabled telematics, safety-as-a-service, over-the-air updates, and subscription communication bundles.
-
Implementation templates—procurement checklists, sample RFP language for HUD subsystem suppliers, and a phased rollout timeline with KPI milestones for 0–24 months.
Competitive landscape: who matters and why
-
Shoei Co., Ltd. (Tokyo) in partnership with EyeLights represents the frontier of integrated OEM solutions. Their GT-Air 3 Smart showcases fully integrated visor-mounted nano-OLED HUDs—a technological leap in readability and integration that sets a new bar for OEM-grade quality. For strategic planners, Shoei’s move demonstrates the scale and brand premium achievable by deep integration versus retrofit approaches.
-
EyeLights (Labège/Toulouse) is a specialist HUD provider that bridges OEM and aftermarket strategies. Their dual role—supplying production helmets and supporting retrofit products—illustrates a scalable supplier model and highlights the importance of flexible interfaces and software ecosystems.
-
Intelligent Cranium Helmets (ICH, Virginia) and CrossHelmet (Tokyo) are examples of vertically integrated challengers offering high feature density (wide-FOV HUDs, multi-camera systems, comprehensive rider sensing). These players underscore how convergence of sensors and AI capabilities creates differentiation beyond display technology.
-
Xi’an Vidoar (MOTOEYE) and Tilsberk (digades) represent the retrofit and compact HUD segments—lower-cost, modular approaches that enable fleet upgrades and broaden addressable demand. Their presence reinforces an important strategic choice: pursue OEM integration or enable large-scale aftermarket conversion.
-
Sena (Irvine) highlights the role of established communication and audio players who can leverage existing channel relationships and software platforms to upsell HUD capability as part of a communications ecosystem.
Across these players, market concentration is meaningful but not prohibitive: the three- and five-firm concentration ratios indicate a market where leading partners control a sizable share, yet opportunities remain for specialized suppliers and regional players to carve niches—particularly in software, retrofit services, and certification support.
Technology and regulation: practical implications
-
Nano-OLED and optics: Advances in display materials (nano-OLED) have materially improved daytime readability and reduced power consumption—enabling visor-mounted implementations without excessive bulk. Procurement strategies should prioritize display suppliers with proven outdoor-readability benchmarks and thermal management experience.
-
Certification constraints: ECE 22.06’s emphasis on rotational impact testing and FMVSS self-certification mechanisms mean that electronics integration must be planned in parallel with structural shell development. Late-stage changes to electronics routing or battery packaging can trigger costly re-testing—budget time and capital accordingly.
-
Materials and weight: Carbon fiber shells remain the lightest route to integrate electronics while meeting protection thresholds, but cost volatility and manufacturing complexity require paired sourcing strategies (primary/secondary suppliers and alloy/layup alternatives).
Strategic implications for 2026
-
R&D and product architecture: Prioritize modularity. A two-track product architecture—one fully integrated OEM line and one modular retrofit-compatible offering—reduces market risk and maximizes channel reach. Modular interfaces (mechanical, electrical, and software APIs) become commercial leverage points for both OEMs and suppliers.
-
Partnerships and M&A: Focus M&A on software stacks and HMI expertise rather than commodity electronics. Small, specialised HUD or sensor firms can deliver immediate capability boosts and accelerate route-to-market.
-
Manufacturing & testing: Invest in early-stage co-validation facilities and a re-test contingency budget linked to certification pathways. Consider strategic partnerships with testing labs to compress certification timelines.
-
Commercial model: Explore blended revenue models—device sales plus recurring services (navigation subscriptions, safety analytics, cloud updates). Service margins will be essential to offset lower hardware ASPs as retrofit competitors scale.
-
Regulatory engagement: Engage with standards bodies and safety institutes proactively. Demonstrated participation in standards development accelerates certification acceptance and reduces non-tariff barriers in key markets.
Three-tier roadmap for 0–36 months
-
Immediate (0–12 months): Finalize supplier agreements for displays, optics, and batteries; lock product architecture and interface specifications; pilot-first production validation with certification lab partnerships; commercial pilot with lead channel partner(s).
-
Mid-term (12–24 months): Scale manufacturing to support retail and fleet channels; launch subscription/service pilots; execute targeted marketing for safety and convenience value propositions; refine pricing using early sales data and sensitivity testing from the report’s financial models.
-
Longer-term (24–36 months): Consolidate software ecosystem (OTA, app integrations, telematics), seek strategic M&A to close capability gaps, and expand into adjacent segments (e.g., commercial two-wheeler fleets, urban micromobility partners).
Call to action
For 2026 planning cycles, the choice for executives is not whether the smart-helmet market will grow—it will—but how to position for sustainable economic returns as the technology moves from headline launches to mass-market viability. PW Consulting’s full report provides the detailed segmentation, downloadable financial models, supplier scorecards, and decision-ready templates necessary to execute with confidence. Contact our Smart Mobility practice to request access to the complete dataset and a tailored executive briefing to map these insights onto your corporate strategy.
For detailed analysis of this topic, please visit the official page: Smart Motorcycle Helmet with Heads-Up Display Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com