

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
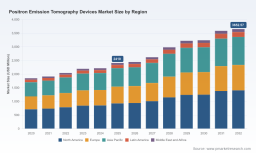
PW Consulting: Worldwide Positron Emission Tomography Devices Market to Hit USD 3,652.57 Million by 2032, Growing at a 6.12% CAGR

Worldwide Positron Emission Tomography Devices Market: Strategic Preview for 2026 Decision-Making
As health systems, device manufacturers, investors, and imaging service providers set budgets and strategic plans for 2026, compact and credible intelligence on the positron emission tomography (PET) devices market is rapidly moving from helpful to imperative. PW Consulting’s latest market study — covering historical performance from 2020–2025 and projecting through 2026–2032 — synthesizes the macro trajectory, competitive dynamics, regulatory and reimbursement levers, and actionable playbooks that executives need to translate uncertainty into opportunity.
Worldwide Positron Emission Tomography Devices Market
Headline market trajectory and what it means for 2026
The PET devices market has exhibited a sustained recovery and expansion over the past half decade, driven by accelerating clinical adoption, upgrades from analog to digital systems, and the emergence of total-body PET applications. Our model shows overall market value moving from roughly USD 1.85 billion in 2020 to an estimated USD 2.41 billion in the 2025 base year, and continuing to expand at a compound annual growth rate of about 6.1% through the forecast window. By the end of the study period the market reaches the mid-single-digit billion range, underscoring a multiyear phase of capital cycle renewal and technology upgrade.
Worldwide Positron Emission Tomography Devices Market
For 2026 planners, the implication is straightforward: the PET market is not static cost-center equipment replacement — it is a growth market with pockets of premiumization (digital detectors, time-of-flight, wide axial field-of-view and total-body systems) that will command differentiated reimbursement and throughput advantages. Capital allocation that assumes flat imaging spend risks being outmaneuvered by competitors who prioritize next-generation modalities and service-based models.
Worldwide Positron Emission Tomography Devices Market
Competitive structure — consolidation and strategic positioning
The market remains concentrated, with the leading vendors collectively controlling the lion’s share of new installations and upgrade cycles. Our concentration metrics corroborate an oligopolistic environment — a structural reality that shapes pricing power, service networks, and product roadmaps. For entrants and smaller players, this connotes an uphill commercialization path but also clearly defined white spaces for focused specialization (e.g., preclinical systems, niche clinical workflows, or bundled isotope services).
- Major incumbents continue to invest in digital PET/CT and hybrid PET/MR capabilities and have been active with regulatory clearances and high-profile showcases that reinforce their technology leadership and channel reach.
- Recent product and regulatory milestones from leading suppliers signal how competition is being fought: approvals for wide axial field-of-view digital PET systems, multi-sensitivity platforms showcased at global conferences, and CE/510(k) clearances for iterative digital upgrades.
- These developments emphasize two concurrent strategies: capture share through differentiated hardware and defend share through expanded service, workflow, and software ecosystems.
Recent vendor moves that alter 2026 playbooks
- Regulatory progress for wide axial field-of-view and digital PET platforms has accelerated throughput and clinical throughput economics, enabling providers to rethink patient scheduling and tracer utilization strategies.
- Leading vendors are deploying product variants that emphasize sensitivity and lesion detectability, which can influence modality choice in oncology and neurology programs as hospitals weigh diagnostic accuracy against capital and operating costs.
- Consolidated product roadmaps and global rollouts by top manufacturers increase the importance of regional service footprint and spare parts agility as differentiators in procurement decisions.
Market forces shaping procurement, operations, and R&D
Several non-product forces will materially affect 2026 decisions. Reimbursement policies — such as national coverage determinations that codify clinical use of FDG-PET in oncology — continue to underpin demand for PET services. Regulatory classification as Class II devices requiring 510(k) premarket notifications in certain jurisdictions means that time-to-market remains tied to regulatory strategy and device equivalence arguments. Supply-side economics are also influential: semiconductor detectors and lutetium-based scintillators remain cost drivers, and industry data indicate that detector components are a meaningful share of system bill-of-materials.
Capital-expenditure behavior among providers will be informed by hospital-level budgeting norms — U.S. hospitals routinely target a mid-single-digit percentage of annual CapEx to imaging upgrades — creating predictable windows for large-ticket replacements. Meanwhile, European MDR requirements and the evolving reimbursement landscape require cross-functional teams to align clinical value propositions with health economics dossiers earlier in the product lifecycle.
What PW Consulting’s report delivers for executives (practical outputs)
The report was built to be pragmatic: it translates macro growth trends into discrete decision tools that procurement, strategy, and clinical leaders can use when preparing 2026 plans. Core deliverables include:
- A validated market sizing and forecast model (historical 2020–2025; forecast 2026–2032) with scenario toggles for adoption speed, pricing trajectories, and capital constraints.
- A supplier landscape and competitive heatmap, including profiles of global leaders, their strategic strengths, recent regulatory or product milestones, and playbook implications for partners and buyers.
- A buyer’s guide that aligns clinical use cases to device classes and total cost of ownership constructs — useful for hospitals and imaging center capital committees evaluating trade-offs between throughput, diagnostic performance, and operating expense.
- An actionable reimbursement and regulatory matrix covering major jurisdictions, including guidance on evidence generation needs to support favorable payer positioning.
- Service and business-model templates that show how vendors can migrate to outcome-linked contracts, subscription-based access, and managed service arrangements to optimize lifecycle revenue.
- An M&A and partnership screening tool highlighting value-creation levers and integration risks for strategic acquirers seeking footprint expansion or technology acceleration.
Note: the report includes deeper segmentation by region, modality, application, and end-user to support granular commercial decisions. In line with our preview approach we intentionally withhold the itemized segment tables here — full segmentation and downloadable model access are available through the report portal for paid subscribers.
Actionable strategic recommendations for 2026
- For hospital systems: prioritize interoperability and workflow automation in procurement specifications to maximize throughput gains from new digital PET installations; negotiate service packages that align uptime guarantees with throughput-based rebates.
- For device manufacturers: accelerate evidence generation that ties diagnostic sensitivity improvements to downstream clinical pathways and payer economics; consider flexible financing and site-as-a-service models to reduce buyer budget friction.
- For investors and private equity: target smaller, high-margin niches such as specialty PET/MRI hybrid workflows, software analytics that enhance diagnostic yield, or isotope supply chain plays that capture recurring revenue.
- For imaging centers and networks: evaluate consolidation and alliance strategies to leverage purchasing scale and centralize tracer logistics for operational efficiencies.
Risk scenarios and early warning signals
Three core risks should be monitored through 2026: reimbursement tightening for certain tracers or indications; supply chain constraints for detector materials that could extend lead times; and competitive disruption from lower-cost entrants that undercut incumbents on price rather than technology. Early warning signals include changes to national payer coverage policies, lengthening component lead times, and accelerated market entries in cost-sensitive geographies. PW Consulting’s forecast model includes scenario stress-tests that quantify the P&L and ROI impacts of each risk pathway.
How this intelligence changes tactical 2026 choices
Procurement calendars should be recalibrated: facilities with mid- to long-term imaging growth can justify premium investments today to capture cumulative throughput and diagnostic advantages, whereas price-sensitive buyers may prefer incremental digital upgrades and managed-service options. Vendors, meanwhile, must align their 2026 roadmaps to secure not only product approvals but also payer acceptance and site-level workflow wins — a trifecta that will determine installed-base longevity and recurring service revenue.
Closing — why this preview matters
Payers, providers, and vendors entering 2026 will face a market that is simultaneously growing and consolidating. PW Consulting’s study offers the strategic context and operational tools to convert market momentum into sustained competitive advantage. This preview has outlined the macro trajectory, key competitive signals, and practical response options — while preserving the granular segment-level evidence and proprietary models that practitioners rely on for final capital decisions. For the full data tables, segmented forecasts, vendor scorecards, and downloadable financial models, access the complete Worldwide Positron Emission Tomography Devices Market report on our website.
For detailed analysis of this topic, please visit the official page: Worldwide Positron Emission Tomography Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com