

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts Worldwide Aerosol Disinfectants Market to Expand at a 5.85% CAGR Through 2032

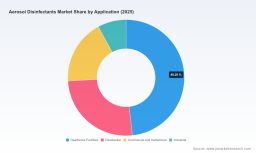
Worldwide Aerosol Disinfectants Market — Strategic Outlook and Decision Playbook for 2026
PW Consulting’s latest market study on the Worldwide Aerosol Disinfectants Market (base year 2025; forecast period 2026–2032) delivers a practitioner-focused intelligence package designed to inform boardroom decisions, commercial plans, and product-roadmap investments in 2026. The market is recovering from pandemic-era volatility and, having grown to roughly USD 6.85 billion in 2025, is projected to expand at a compound annual growth rate (CAGR) of approximately 5.85% through the forecast horizon — reaching just over USD 10.2 billion by 2032. This report synthesizes those macro dynamics into actionable choices while intentionally reserving core segmentation matrices to the full report, so leaders can validate the paths that best fit their risk appetite and capital plans.
Worldwide Aerosol Disinfectants Market
Why this report matters for 2026 decision-making
-
Timing for portfolio reconfiguration: As the market transitions from episodic demand spikes to steady, innovation-led growth, firms must decide whether to prioritize premium specialty products (e.g., sporicides, air sanitizers) or defend volume-led consumer lines.
Worldwide Aerosol Disinfectants Market -
Regulatory inflection point: With 2025–2026 updates to EPA programs (including Safer Choice criteria), formulation strategy and claim substantiation have become central to market access and marketing differentiation.
Worldwide Aerosol Disinfectants Market -
Cost and supply-chain volatility: Historical price swings in key feedstocks have compressed margins; leaders will need defensible hedging and sourcing plans to preserve profitability.
-
Competitive landscape parity: Market concentration is moderate (CR3 ~38.4%; CR5 ~52.2%), indicating sizeable incumbents but persistent room for specialized challengers and bolt-on acquisitions.
-
Channel and customer evolution: Professional and institutional buyers are demanding validated efficacy and sustainability credentials, while retail and e‑commerce continue to favor recognizable brands and clear environmental narratives.
What’s inside the PW Consulting report (practical deliverables)
-
Executive synthesis of macro trends and three actionable scenarios (conservative, base, upside) that translate market growth into revenue and margin outcomes for 2026 planning cycles.
-
Proprietary market model (editable) projecting total market size and price/mix impacts across 2026–2032, with sensitivity levers for raw-material inflation, regulatory headwinds, and channel shifts.
-
Regulatory risk register and claims playbook detailing EPA registration pathways, evidence expectations for virucidal/sporicidal claims, and implications of the 2025 Safer Choice criteria on VOCs and microplastic content.
-
Commercial playbooks for three go-to-market archetypes: consumer brand leader, institutional specialist, and value/private-label operator — each with pricing strategy, sales incentives, and six-month pilot templates.
-
Supply-chain resilience toolkit including a supplier-scorecard, contract-clause templates for feedstock hedging, and contingency sourcing maps designed to mitigate 15–20% historic price volatility in alcohols and peroxides.
-
R&D and product roadmap matrix that prioritizes actives and attributes likely to win in 2026 (low-VOC formulations, plant-based actives, rapid-contact claims) along with estimated development timelines and regulatory milestones.
-
Due-diligence checklist for M&A and partnership screening, including EBITDA sensitivity, brand overlap analysis, and integration risk diagnostics tied to market concentration dynamics.
-
Appendices with primary interview excerpts from procurement heads, infection-control specialists, and commercial buyers — providing qualitative validation of quantitative signals.
Competitive landscape — strategic implications for key players
-
Large consumer CPG leaders (e.g., Reckitt Benckiser, The Clorox Company, S.C. Johnson, Procter & Gamble) retain structural advantages: brand equity, broad retail distribution, and regulatory experience to support EPA claims. Their continued investment in air sanitizer formats and plant-based lines demonstrates a dual strategy — defend core surface disinfectants while capturing adjacencies that command premium price points.
-
Institutional and service-focused providers (e.g., Ecolab, Diversey, Zep, GOJO, Kimberly‑Clark) compete on validated efficacy, concentrate and dispense systems, and service contracts. Ecolab’s recent launch of a hydrogen-peroxide-based rapid sporicide underscores an emphasis on higher-margin, specialty offerings tailored to cleanroom and pharmaceutical customers.
-
Technology- and formulation-focused firms (including 3M’s commercial product lines) are differentiating through concentrated chemistries and claims-supporting data packages for healthcare and industrial customers. Such capabilities shorten the path to institutional procurement approvals.
-
Market structure favors both incumbency and opportunistic consolidation: CR3 and CR5 figures show that the top players capture meaningful share, but mid-size specialists and regional manufacturers retain pockets of influence — creating an active M&A and partnership landscape for acquiring technical capability or distribution reach.
-
Recent product activity (e.g., Clorox’s EcoClean plant-based range; Reckitt’s aerosol air sanitizer; S.C. Johnson’s family-focused sprays; Ecolab’s Klercide Rapid Sporicide) signals three parallel trajectories: sustainability-linked reformulation, air and sporicidal adjacencies, and expanded professional offerings. These trajectories create choice pressure for 2026 resource allocation.
Market dynamics and risk factors to monitor in 2026
-
Raw-material exposure: Alcohols (ethanol/isopropanol) remain dominant carriers; quats and hydrogen peroxide are critical alternatives for hospital-grade claims. Historical supply disruptions have driven near-term price swings; teams must adopt inventory and contractual tactics to limit margin erosion.
-
Regulatory stringency: EPA lists and Safer Choice criteria continue to evolve — affecting allowable marketing claims and formulation choices. Early engagement with regulatory bodies and investment in validation science de-risks product launches.
-
Sustainability and consumer expectations: Low‑VOC claims, biodegradability, and reduced microplastic footprints are increasingly important to consumers and procurement teams; these attributes are now table stakes in certain channels.
-
Channel economics: Retailers and e-commerce marketplaces are compressing price points while rewarding differentiation (speed-to-kill, safety, eco-credentials). Manufacturers must balance trade spend with investment in brand equity.
-
Innovation cadence: Rapid-contact disinfectants, air sanitizers, and sporicides represent higher-margin niches but require clinical evidence and longer regulatory timelines; firms should align R&D pipelines to expected procurement cycles.
Priority strategic moves for 2026 (what management teams should do now)
-
Re-run your portfolio through a three-horizon lens: identify which SKUs to accelerate (adjacencies and premiumized formats), which to rationalize, and which to retain for scale economics.
-
Implement a raw-material risk program: secure multi-sourced contracts for alcohols and peroxides, set hedging thresholds, and evaluate on‑shoring options for critical intermediates.
-
Invest selectively in claim-substantiation: allocate budget to third-party efficacy testing and EPA dossier compilation for any product that targets institutional or healthcare procurement.
-
Operationalize sustainability: prioritize low-VOC reformulations and align packaging to recyclability standards to meet Safer Choice and retail requirements without sacrificing efficacy.
-
Evaluate bolt-on acquisitions and joint ventures focused on specialty chemistries or contract manufacturing to accelerate market entry into high-margin niches (air sanitizers, sporicides).
-
Modernize commercial models: deploy account-based marketing for institutional channels, and sharpen e-commerce assortments and digital content for consumer searches tied to efficacy and safety.
-
Adopt advanced demand-forecasting tools that combine epidemiological triggers, seasonality, and channel signals to better plan inventory and promotional calendars.
How PW Consulting supports your 2026 agenda
-
Bespoke market-sizing and sensitivity models calibrated to your product mix and commercial footprint.
-
Regulatory and claims playbooks, including dossier templates and test-lab sourcing to accelerate EPA registration.
-
Commercial due diligence and M&A screening using our proprietary concentration and overlap analytics.
-
Implementation roadmaps for supply-chain de-risking and low-VOC reformulation programs, with vendor selection support.
Conclusion — The 2026 inflection: The aerosol disinfectants market is no longer defined solely by episodic surges. With a stable multi-year growth trajectory (CAGR ~5.85%) and expanding opportunities in specialty chemistries and air/surface adjacencies, 2026 will reward firms that combine disciplined portfolio choices, regulatory foresight, and supply-chain resilience. PW Consulting’s report translates the topline growth trend into concrete operational moves and decision frameworks — preserving the confidential, granular segmentation and scenario outputs for readers who access the full report and supporting models.
To obtain the full dataset, editable models, and the sector-specific appendices that underpin the recommendations summarized here, please visit our report page.
For detailed analysis of this topic, please visit the official page: Worldwide Aerosol Disinfectants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com