

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide P‑chlorophenol Market to Grow at 4.4% CAGR, Reaching USD 568.5 Million by 2032

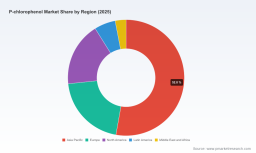
Worldwide p-Chlorophenol Market — Strategic Outlook 2026: A PW Consulting Preview
Executive summary
PW Consulting’s forthcoming Worldwide p-Chlorophenol Market report (base year 2025; historical 2020–2025; forecast 2026–2032) provides a focused, actionable toolkit for executives preparing strategic moves in 2026. The market reached roughly USD 421 million in 2025 and—driven by diversified downstream demand, feedstock dynamics, and tightening regulation—our model projects steady expansion at a 4.4% compound annual growth rate through the forecast window. By 2032 the model points to materially higher market value versus 2025, underlining attractive mid-term upside for well-positioned participants.
Worldwide P-chlorophenol Market
Why this preview matters to decision-makers in 2026
-
Timing: 2026 is a pivot year for capex, sourcing agreements, and regulatory compliance programs across the p-chlorophenol value chain. Delays in strategic action now will compress optionality later in the forecast period.
Worldwide P-chlorophenol Market -
Risk concentration: Market concentration metrics show a moderately consolidated landscape (CR3 ≈ 42.5%; CR5 ≈ 58.8%), which creates both supply-side negotiating leverage for larger producers and entry windows for specialist mid‑market players with differentiated capabilities.
Worldwide P-chlorophenol Market -
Cost and margin pressure: Upstream phenol and chlorine feedstock volatility is already reshaping cost curves and supplier strategies—factors that will determine which producers can sustain margins while meeting compliance demands.
Market dynamics shaping strategic choices
Executives must weigh three interlocking forces when setting 2026 priorities: demand composition across downstream sectors, feedstock cost trajectories, and heightened environmental regulation. The report synthesizes quantitative forecast scenarios with qualitative interviews and plant-level benchmarking so that leaders can convert macro signals into executable plans.
-
Feedstock volatility: Phenol—the primary upstream input for p-chlorophenol manufacture via chlorination—has shown pronounced regional price movement into early 2026. For example, Northeast Asian phenol prices were observed near USD 1.01/kg in March 2026, reflecting pricing pressure from bisphenol A and resin segments, while other regions displayed distinct price dynamics tied to benzene and propylene feedstock swings. These differentials materially affect margin dispersion across producers and will shape sourcing strategies and hedging priorities in 2026.
-
Regulatory intensity: 4‑Chlorophenol has been designated a priority pollutant by the US EPA and is subject to EU REACH assessments. Such classifications increase monitoring, wastewater treatment obligations, and potential permit-related constraints on capacity expansions. Companies that preemptively invest in emissions control and compliance programs will reduce regulatory risk and create optionality for premium supply contracts.
-
Downstream demand complexity: While agrochemical and pharmaceutical intermediates continue to anchor demand, disinfectants, preservatives, dyes, and specialty chemistries intermittently drive surges. The interplay between cyclical industrial demand and structural shifts in pharmaceutical R&D spend leads to asymmetric demand scenarios that we model in the full report.
Competitive landscape — what leaders and challengers signal for 2026
The p-chlorophenol ecosystem comprises established regional producers, global reagent suppliers, and specialized fine‑chemical manufacturers. The market’s concentration profile (CR3 ≈ 42.5%, CR5 ≈ 58.8%) suggests a balance: meaningful market share held by a small set of large incumbents, with room for niche and low‑cost suppliers to capture pockets of growth.
-
Large incumbent manufacturers: Several long-established manufacturers—whose operations range from chlorination-based bulk production to high-purity reagent grading—anchor the supply base. These players have scale benefits in feedstock procurement and logistics, enabling them to service broad industrial needs as well as supply major contract volumes for agrochemical and pharmaceutical intermediates.
-
Specialists and reagent suppliers: Global life‑science and chemical-reagent companies maintain high‑purity product lines tailored to laboratory, analytical, and research markets. Their value proposition is built on consistency, certification, and channel reach rather than raw-scale cost leadership.
-
Regional low-cost players: A group of regional producers is competitive on price and proximity to key downstream clusters. These businesses can disrupt local supply chains, especially where feedstock sourcing or logistics favors regional production. However, regulatory compliance investments are a gating factor for cross-border expansion.
Representative company snapshots and profiles are included in the full report; they cover manufacturing footprint, product grades, regulatory posture, and commercial go-to-market approaches. Among the firms we profile are established Indian producers with decades of experience in chlorination processes; Japanese suppliers who focus on high‑purity reagent production; global lab-chemicals players supplying reliable reagent lines; and Chinese manufacturers with substantial capacity aimed at large-volume intermediates. For detailed competitive scorecards and supplier matrices, the full dataset is available in the report package.
What the PW Consulting report contains — practical, transaction-ready content
This report is designed as an operational playbook for 2026 and beyond. It does not simply restate market direction; it equips teams with stepwise analyses they can act upon. Key deliverables include:
-
Quantitative forecasts and scenarios: Top-line market projections to 2032, including sensitivity analyses that isolate outcomes based on feedstock price paths, regulatory tightening, and shifts in downstream demand cycles.
-
Cost-to-serve and margin models: Granular cost-build models for representative plant configurations and product grades, enabling CFOs to simulate margin outcomes under varied feedstock and energy regimes.
-
Regulatory impact assessments: Detailed mapping of key jurisdictions, compliance requirements, and CAPEX timelines for wastewater, emissions abatement, and product stewardship programs.
-
Commercial playbooks: Go-to-market strategies segmented by customer type (bulk intermediates vs high-purity reagents), including recommended contract structures, pricing levers, and channel optimizations.
-
M&A and partnership shortlist: Identification of potential acquisition targets and JV partners based on strategic fit, technical capabilities, and regional access. Each candidate is assessed for integration risk and upside potential.
-
Operational checklists: Plant-level reliability, safety, and compliance checklists designed to reduce time-to-market for capacity additions and minimize regulatory exposure during scale-up.
Strategic playbook for 2026 — recommended actions by role
-
CEOs and corporate strategists — prioritize scenario planning: Develop at least two 24‑month scenarios that stress-test the business against feedstock spikes and expedited regulatory compliance. Use the report’s scenario models to set trigger points for capex and M&A.
-
CPOs and procurement teams — reconfigure feedstock strategies: Move from transactional buying to multi-sourced, hedged supply agreements that include indexation clauses and options for physical delivery shifts between regions. The report’s cost models allow procurement to quantify the P&L impact of different hedging strategies.
-
R&D and product leads — segment by value: Prioritize high-purity grades and specialty derivatives that command structural premiums and are less exposed to commodity price swings. The report outlines product-differentiation pathways and quality certification needs.
-
Investors and private equity — screen for regulatory-ready assets: Target assets with demonstrable compliance programs and retrofit-ready infrastructure. The market’s concentration profile creates roll-up opportunities in regional markets where compliance upgrades can be amortized across increased volumes.
How PW Consulting’s intelligence accelerates decision cycles
Our methodology combines bottom-up plant modeling, supplier interviews, trade flow analysis, and regulatory audits. The outcome is a set of decision-ready deliverables: valuation knobs for M&A, actionable procurement hedges, and compliance roadmaps with estimated timelines and CAPEX ranges. The report is structured to reduce executive analysis time—turning open questions into explicit options with associated costs and implementation milestones.
Next steps and how to access the full intelligence
This preview is deliberately selective: it signals where the market is moving and why 2026 is a pivotal planning horizon without disclosing the granular regional or application-level revenue tables reserved for the full report. For procurement models, plant-level cost sheets, supplier scorecards, and the complete set of segmented forecasts, please consult the full Worldwide p-Chlorophenol Market report available through PW Consulting. The detailed datasets and annexes are designed to plug directly into financial models and board materials so teams can act immediately.
PW Consulting stands ready to support custom scenario runs, diligence for transactions, and rapid implementation planning. In a market where feedstock dynamics and regulation can flip competitive advantage quickly, moving from insight to action is the deciding factor for leadership in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide P-chlorophenol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com