

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts Worldwide Automotive Angular Position Sensor Market to Reach USD 7,566.86 Million by 2032

Worldwide Automotive Angular Position Sensor Market: Strategic Outlook and Decision Playbook for 2026
PW Consulting’s latest market intelligence report — Worldwide Automotive Angular Position Sensor Market (base year 2025, forecast 2026–2032) — equips executives with the near-term foresight and actionable frameworks required to make high-consequence decisions in 2026. Anchored in a rigorous historical review (2020–2025) and forward-looking scenario models, the study shows a resilient market trajectory (2025 market size USD 4,560.96 Million projecting to USD 7,566.86 Million by 2032 at a 7.5% CAGR). For suppliers, OEMs, investors and Tier‑1 systems integrators, the report translates macro momentum into specific strategic imperatives while deliberately preserving the proprietary granularity that drives competitive advantage — the full data tables, regional and application breakdowns, and transaction-level intelligence are available in the complete report.
Worldwide Automotive Angular Position Sensor Market
What this report delivers — practical, decision-ready content
- Executive synthesis with prioritized strategic opportunities mapped to 12- and 36-month investment horizons.
- Market-sizing methodology, reconciled historical time series (2020–2025) and transparent forecast models for 2026–2032, with scenario sensitivity to technology adoption and regulatory shifts.
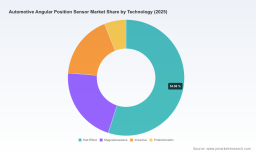
- Technology deep-dive (Hall-effect, magnetoresistive, inductive, potentiometric): performance trade-offs, cost curves, and qualification timelines for automotive applications.
- Comprehensive competitive benchmarking and supplier scorecards covering design maturity, automotive qualifications (e.g., AEC-Q100, ISO 26262), manufacturing footprint, and customer concentration risk.
- Supply-chain risk matrix: magnet and rare-earth exposure, single-sourced semiconductor risks, and mitigation levers (dual sourcing, material substitution, vertical integration).
- Go‑to‑market playbooks for OEMs, Tier‑1s and component manufacturers, including co-development contracting templates and time-to-qualify roadmaps for 2026 programs.
- M&A and partnership screening framework: strategic fit criteria and valuation sensitivities tailored to sensor assets and software-enabled modules.
- Interactive model and downloadable datasets (license options) for C-suite planning and procurement stress-testing.
Market trajectory and implications for 2026 decision-making
After steady expansion through 2020–2025, angular position sensing demand enters a phase where safety, electrification and ADAS investments compound one another. The market expanded from the low-thousands in 2020 to USD 4,560.96 Million in 2025 and is modeled to reach approximately USD 4,922.31 Million in 2026, continuing on a growth path to roughly USD 7,566.86 Million by 2032 at a 7.5% CAGR. This growth is not uniform — it is driven by three convergent forces:
Worldwide Automotive Angular Position Sensor Market
- Electrified powertrains and inverter-driven motors that require high-precision angular feedback for motor commutation and e-axle control.
- Safety and ADAS standards tightening the tolerance and redundancy requirements for steering and yaw-related sensing.
- Replacement and retrofit channels for legacy vehicles, where cost and robustness compete with higher-precision, software‑assisted offerings.
For 2026, the critical decision window centers on technology diversification and qualification lead times. Qualification cycles for safety‑critical components commonly span 12–36 months; hence product roadmap choices made in 2026 will materially influence content of 2028–2030 vehicle programs.
Worldwide Automotive Angular Position Sensor Market
Competitive landscape — strengths, gaps and tactical moves
The market exhibits moderate concentration: the top three suppliers account for a meaningful share of shipments (CR3 ~38.5%) while the top five extend that footprint further (CR5 ~52.15%). This structure creates a competitive environment where scale confers advantages (volume pricing, global OEM relationships), but specialization and technology differentiation still unlock premium margins.
- Allegro MicroSystems (Manchester, NH, USA) — A leader in contactless magnetic sensors, with automotive-qualified A1335/A1339 series geared toward throttle, pedal and steering use cases. Recent product launches emphasize stray-field immunity and precision for motor control applications.
- ams‑OSRAM AG (Premstätten, Austria) — Offers a broad magnetic rotary portfolio optimized for automotive volumes; product catalogue updates in recent cycles target transmission and high-volume throttle sensing segments.
- BorgWarner Inc. (Auburn Hills, MI, USA) — Integrates sensors into actuator modules for both conventional and electrified powertrains, positioning as a systems supplier for OEMs managing mechanical-electrical integration risk.
- Continental AG (Hanover, Germany) — Focused on steering angle and resolver-based solutions for ADAS and chassis control, leveraging systems-level competence in vehicle dynamics.
- Infineon Technologies AG (Neubiberg, Germany) — Supplies hall-effect angular ICs tailored for motor and gearbox applications; strong semiconductor roadmap and manufacturing scale are competitive differentiators.
- Melexis NV (Ieper, Belgium) — Known for Triaxis hall-effect architectures; recent releases include ASIL‑compliant steering sensors aimed at ADAS safety stacks.
- NXP Semiconductors (Eindhoven, Netherlands) — Focuses on magnetic angle solutions positioned as resolver replacements for traction motors and steering actuation.
- Novotechnik U.S. Inc. (Southborough, MA, USA) — Specialist in contactless and inductive solutions for harsh environments; the inductive approach reduces reliance on rare-earth magnets.
- Renesas Electronics Corporation (Tokyo, Japan) — Marketing IPS/LPS magnetic angle sensors for e‑axles, pumps and transmission feedback with strong integration potential into SoC ecosystems.
- STMicroelectronics (Geneva, Switzerland) — Offers hall-based sensors addressing motor commutation and EV position sensing with semiconductor partner synergies.
- TE Connectivity (Schaffhausen, Switzerland) — Provides modular rotary and non-contact magnetic sensors for throttle and pedal assemblies with a distribution and systems-integration focus.
Recent vendor moves underscore technology differentiation as a competitive lever: Allegro’s early‑2024 high‑precision angle sensor launch, Melexis’s ASIL-B steering sensor release, and ams‑OSRAM’s product updates illustrate supplier efforts to align products with safety and motor-control trends.
Supply-chain dynamics and technology risk
Two supply-side dynamics demand urgent attention in 2026 planning:
- Raw-material volatility: neodymium‑iron‑boron magnet pricing and supply constraints have exerted upward pressure on magnetic-sensor BOMs; historical price swings of 15–20% are material to component economics and procurement strategies.
- Material substitution and design shifts: inductive sensing architectures remove rare-earth magnet dependency, offering a strategic hedge but requiring requalification and potential system redesigns. The transition timeline and cost trade-offs vary by vehicle program and application.
Regulatory and safety drivers
Regulatory and standards developments are elevating minimum performance and redundancy requirements in safety-critical sensing. ISO 26262 functional safety mandates, Euro NCAP redundancy requirements for steering angle sensing, and FMVSS‑126 accuracy standards for stability control collectively raise the bar for qualification, testing rigour and system redundancy. These constraints accelerate demand for ASIL‑compliant sensor platforms and multi-sensor fusion approaches, which in turn influence supplier selection and integration strategies.
Strategic recommendations for 2026
- For OEMs: Lock sensor qualification windows into program schedules now. Prioritize suppliers with demonstrated ASIL pathways and dual-technology offerings to mitigate rare‑earth supply risk.
- For Tier‑1 systems integrators: Build software/hardware fusion capabilities that can aggregate lower-cost sensors into safety-compliant solutions; pursue preferred-partnership models with sensor vendors to secure volume pricing.
- For sensor manufacturers: Invest in inductive and resolver‑replacement technologies as hedges; accelerate automotive qualification (AEC‑Q, ISO 26262) and offer system-level IP (diagnostics, redundancy management) to move up the value chain.
- For investors and M&A strategists: Target niche inductive specialists and suppliers with strong ASIL roadmaps; valuation premiums will accrue to firms that reduce critical-material exposure while demonstrating integration capability with vehicle control software.
Scenario planning — near-term triggers to monitor
- Baseline: steady adoption of electrification and ADAS yields the modeled 7.5% CAGR; incumbent suppliers retain share with selective innovation.
- Accelerated electrification: faster EV penetration compresses qualification cycles and rewards suppliers with scalable semiconductor-integrated solutions.
- Material-disruption shock: a severe rare-earth supply shock would cause a rapid shift toward inductive/resolver architectures and create opportunities for non-magnetic sensor specialists.
Key triggers to watch in 2026 include new Euro NCAP protocol updates, large OEM platform platformization decisions for sensor sourcing, and any sudden escalation in magnet supply tensions.
Accessing the full intelligence
This release is a strategic primer designed to orient executive decisions for 2026. It intentionally highlights the market drivers, competitive dynamics and tactical playbooks while withholding the proprietary tables and granular splits that underpin supplier-level and regional go-to-market strategies. The complete report delivers those datasets — regional and application segmentation tables, supplier share matrices, pricing curves and interactive financial models — which are essential for procurement negotiation, program costing and M&A diligence.
PW Consulting stands ready to support tailored briefings, custom scenario runs, and acquisition screening exercises derived from the full dataset. For organizations preparing capital allocation, procurement strategy or qualification roadmaps in 2026, the intelligence and playbooks contained in the comprehensive report convert macro trends into executable actions.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Angular Position Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com