

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Fibroblast Activation Protein (FAP) Inhibitors Market to Climb from USD 320 Million in 2025 to USD 843.46 Million by 2032 at a 14.85% CAGR

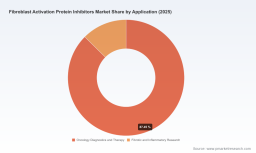
Worldwide Fibroblast Activation Protein (FAP) Inhibitors Market — Strategic Outlook for 2026 Decision-Makers
Executive Summary
The worldwide market for Fibroblast Activation Protein (FAP) inhibitors has moved from a niche research focus toward a structured commercial opportunity. Our PW Consulting baseline shows the market expanding from approximately USD 150 million in 2020 to an estimated USD 320 million in the base year 2025, and—under our central case—continuing to grow at a compound annual growth rate (CAGR) of roughly 14.85% through the 2026–2032 forecast window. By the end of that horizon the market is projected to more than double relative to 2025 levels. This trajectory reflects accelerated clinical activity, expanding theranostic pipelines, and a maturing commercial ecosystem for radiopharmaceutical manufacturing and distribution.
Worldwide Fibroblast Activation Protein Inhibitors Market
Why this report matters for corporate strategy in 2026
For life sciences and specialty radiopharmaceutical executives facing 2026 planning cycles, FAP-targeting agents present a high-opportunity, high-complexity segment. The report is designed to convert that complexity into a pragmatic decision framework. It blends historical performance (2020–2025), near-term inflection points, and multi-scenario forecasts (2026–2032) into actionable guidance for R&D prioritization, partner selection, manufacturing investments, commercial launch sequencing, and M&A timing.
Worldwide Fibroblast Activation Protein Inhibitors Market
- Tactical precision: We map realistic launch windows and commercial runway assumptions to reduce timing risk when allocating late-stage development capital.
- Commercial playbooks: We outline repeatable commercial models for diagnostic radiotracers and therapeutic radioligands that reflect variations in reimbursement regimes and care pathways.
- Investment sizing and timing: Our financial scenarios let leadership teams test different paths—organic scale-up, licensing and co-development, or tuck-in acquisitions—against valuation and funding constraints.
Market Dynamics and Structural Drivers
The FAP inhibitors market is being shaped by four interlocking dynamics that are material to any 2026 strategic plan:
Worldwide Fibroblast Activation Protein Inhibitors Market
- Clinical momentum and theranostic convergence: A growing number of radiolabeled FAP agents are moving through clinical stages. The therapeutic ambition—pairing diagnostic imaging agents with corresponding therapeutic radioligands—creates differentiated value chains but also intensifies the need for companion diagnostic strategies and regulatory coordination.
- Manufacturing and isotope economics: Production relies on a set of specialized radioisotopes (Ga-68, F-18, Cu-64/67, Pb-212) and often requires cyclotron capacity, specialized radiochemistry, and regional distribution solutions to manage short half-lives. Supply security and flexible manufacturing partnerships will be competitive advantages.
- Regulatory and reimbursement uncertainty: As of early 2026, most FAP-targeted agents remain investigational; routine reimbursement for diagnostic or therapeutic applications is not yet widespread. Companies must invest in evidence generation strategies that anticipate payer requirements while balancing commercialization timing.
- Consolidation versus innovation: Market concentration metrics indicate that large-cap and specialist players control a meaningful share of early commercial positioning, but patent activity and small-cap innovation continue to create entry points for differentiated offerings.
Competitive Landscape — What matters in 2026
Our analysis profiles incumbent and emerging organizations across the value chain—from tracer innovators and global radiopharmacy platform companies to clinical-stage therapeutic developers. Several strategic patterns emerge:
- Platform incumbents pursuing exclusivity and scale: Established pharmaceutical and radiopharmaceutical companies have pursued exclusive licensing and global rights to promising FAP-targeting agents, enabling them to align late-stage development with global commercialization strategies. This approach reduces competitive fragmentation for specific compounds but requires heavy capital and regulatory coordination.
- Tracer developers aligning with distribution partners: Specialist radiotracer companies have opted for commercialization partnerships with imaging and distribution majors to overcome the logistical challenges of short-lived isotopes and to scale clinical adoption.
- Theranostic-focused innovators: Clinical-stage developers are pursuing alpha- and beta-emitting therapeutic programs paired with companion imaging agents, reflecting a deliberate move toward tailored patient selection and dosimetry-led development plans.
- Academic-derived pipelines moving to industry: A steady flow of university-origin assets is being licensed or acquired to broaden company portfolios, creating opportunities for both bolt-on clinical capabilities and IP consolidation.
Key corporate actions to watch in 2026 include continued licensing and co-development agreements, targeted acquisitions of manufacturing capabilities (including cyclotron and radiochemistry assets), and strategic collaborations to secure isotope supply chains. Recent public activity—clinical first dosing milestones, patent allowances on novel compositions, and pipeline expansions through in-licensing—illustrates this mix of strategies in practice.
Operational and Regulatory Risks — How to prioritize mitigation
Decision-makers must treat several constraints as central planning variables rather than peripheral risks:
- Regulatory timelines and approval sequencing: The investigational status of most FAP agents means that go-to-market timing remains fluid. A clear regulatory intelligence plan and early engagement with agencies will materially reduce execution uncertainty.
- Reimbursement evidence generation: Diagnostic adoption without payer pathways will slow clinical uptake. Companies that craft parallel clinical and health-economic evidence plans will be better positioned for rapid adoption once approvals are secured.
- Isotope security and manufacturing scale: Investing in flexible manufacturing capacity, regional supply partnerships, or contract manufacturing arrangements mitigates bottlenecks and geographic access gaps.
- IP and freedom-to-operate: Patent grants and composition-of-matter allowances in the field are accelerating; careful mapping of patent estates and defensive filing strategies are essential for mid-term freedom to operate.
What the PW Consulting report contains — practical deliverables for 2026 planning
We built this report as a decision-making toolkit rather than a descriptive summary. Highlights include:
- Time-series revenue modeling (2020–2025 historical; 2026–2032 forecast) with sensitivity bands and scenario toggles for clinical success rates, reimbursement adoption, and supply constraints.
- A strategic playbook distinguishing commercialization approaches for diagnostic tracers versus therapeutic radioligands, including launch sequencing options and central vs. decentralized manufacturing trade-offs.
- Partner and supplier mapping, including cyclotron and isotope suppliers, radiochemistry specialists, and distribution networks—paired with a partnership scorecard to prioritize alliances by capability, geography, and speed-to-market.
- Clinical and regulatory timeline maps linked to value inflection points that impact valuation and capital planning.
- M&A and licensing target screening criteria and a shortlist of translational assets that fit buy/build/partner archetypes.
- Operational checklists for supply-chain resilience, GMP radiopharmaceutical production scale-up, and clinical trial site readiness for short-lived isotope logistics.
- Competitive intelligence dossiers on leading companies and technology differentiators, aligned with our CRx-style benchmarking and concentration metrics.
Strategic Recommendations for Corporate Leadership
For boards and executive teams reconciling competing priorities in 2026, our top strategic recommendations are:
- Prioritize platform flexibility: Favor modalities and partnerships that allow pivoting between isotopes and chelation chemistries; flexibility reduces stranded-asset risk if a given radioisotope pathway underperforms.
- Co-invest in evidence generation: Deploy capital to dual-purpose trials that generate regulatory and payer-relevant endpoints simultaneously—this accelerates both approval and reimbursement readiness.
- Secure supply through layered partnerships: Combine in-house capability development with supplier agreements and regional CMOs to manage isotope scarcity and distribution complexity.
- Use IP strategically: Pursue a mix of defensive patents and selective licensing that enables freedom to operate while avoiding capital-intensive exclusivity battles.
- Be opportunistic on M&A: Target acquisitions that close capability gaps (manufacturing, radiochemistry, regulatory expertise) rather than only portfolio breadth; integration value is highest where operational synergies are achievable within 12–24 months.
How to use the full report
This press summary is intentionally selective. The full PW Consulting Worldwide FAP Inhibitors Market report provides the detailed datasets, breakouts, and modeling assumptions that underpin the scenarios summarized here—alongside exclusive annexes such as partner due-diligence templates, payer evidence matrices, and a prioritized list of operational vendors and global CMOs. If your 2026 planning depends on precise timing, cost-to-market, or potential deal valuations, the full dataset and our custom advisory workshops will materially shorten your path to a defensible investment decision.
Closing Perspective
The FAP inhibitors field sits at a classic inflection point: accelerating scientific validation and active industrialization present rapid upside, but execution complexity—radiochemistry, isotopes, regulatory and reimbursement paths—creates tangible downside for the unprepared. PW Consulting’s analysis quantifies that opportunity at the market level and provides the operational tools to translate long-range growth potential into immediate 2026 actions. For companies that align development priorities with realistic supply, regulatory, and payer strategies, FAP-targeted theranostics and diagnostics could become a durable and high-margin franchise over the coming decade.
For access to the full report, bespoke briefings, or to commission a tailored scenario model for your portfolio, contact PW Consulting’s Healthcare and Radiopharmaceuticals practice.
For detailed analysis of this topic, please visit the official page: Worldwide Fibroblast Activation Protein Inhibitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com