

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide 12‑Channel ECG Market Set to Hit USD 2.27 Billion by 2032 at 6.45% CAGR — Stationary Devices and Hospitals Lead Demand

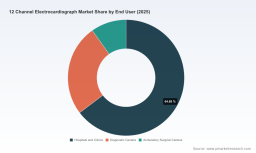
Worldwide 12-Channel Electrocardiograph Market: Strategic Imperatives for 2026 — PW Consulting Insights
As healthcare providers, device manufacturers, investors and payers position for a new phase of cardiac diagnostics modernization, PW Consulting today releases a strategic preview of our Worldwide 12 Channel Electrocardiograph Market study. Grounded in multi-year trend analysis and forward-looking scenario modeling, the report surfaces the high-impact forces that will shape procurement, R&D, channel strategy and regulatory engagement through 2026 and beyond.
Worldwide 12 Channel Electrocardiograph Market
Market trajectory at a glance
Our modeled base year is 2025 and the formal forecast window runs from 2026 through 2032. At the market level, the worldwide 12-channel ECG industry is on a clear growth path: total market revenues rise materially from the 2025 baseline (USD 1,465.5 Million) to an expected USD 2,269.9 Million by 2032, reflecting a 2026–2032 compound annual growth rate (CAGR) of 6.45%. Market concentration is moderate-to-high, with the top three and top five firms capturing meaningful shares of the value pool (CR3: 38.4%; CR5: 54.25%).
Worldwide 12 Channel Electrocardiograph Market
These headline numbers underwrite three fundamental takeaways for 2026 decision‑makers: demand growth is resilient, structural consolidation remains a strategic pressure point, and a wave of technology-enabled product variants is expanding addressable use cases beyond traditional hospital bedside diagnostics.
Worldwide 12 Channel Electrocardiograph Market
Why 2026 is an inflection year
- Regulatory and reimbursement tailwinds: 12‑lead ECG devices continue to be regulated as Class II medical devices (21 CFR 870.2340), while reimbursement clarity — including established CPT codes for standard 12‑lead procedures and newer Category III code recognition for algorithm‑generated ECGs — is lowering barriers to commercial adoption of AI‑assisted and novel sensor designs in outpatient and EMS settings.
- Platform innovation: From single‑use sensor systems and cable‑free synthesized leads to handheld AI interpreters, 2025–2026 has seen multiple regulatory clearances and first commercial deployments that materially broaden clinical deployment models.
- Channel expansion: Early movers are proving the economics of non‑traditional channels (EMS, home‑care, preventive clinics), which has implications for pricing, service models and customer success approaches in 2026.
Technology and commercialization dynamics
The pace of product innovation is accelerating along several vectors:
- AI interpretive engines: Solutions that embed automated interpretation — now with regulatory approvals for expanded cardiac determinations — are shifting value from pure hardware to software and cloud analytics. This creates recurring revenue opportunities from algorithm updates, interpretive licenses and analytics services.
- Sensor and form‑factor innovation: Single‑use sensor arrays and cable‑free synthesized 12‑lead approaches are simplifying workflows (shorter setup times, reduced training burden) and unlocking new use cases such as EMS and at‑home diagnostics.
- Integration with clinical workflows: Buyers increasingly demand plug‑and‑play interoperability with EHRs, cardiology PACS and telemetry systems — not just a standalone device — which elevates systems integration capabilities as a competitive differentiator.
Competitive landscape — who matters and why
Our competitive analysis emphasizes firm capabilities and strategic positioning rather than raw market share numbers (these finer splits are available in the full report). The current field blends established capital‑equipment incumbents with agile device and AI specialists:
- Global capital equipment leaders: Names such as GE Healthcare and Philips Healthcare continue to anchor hospital portfolios with validated resting ECG platforms and enterprise‑grade interoperability. GE’s recent clearance for a versatile MAC series underscores sustained investment in modular print/analysis capabilities.
- Cardiology‑focused OEMs: Schiller AG, Nihon Kohden and Mortara/Mindray remain influential through deep clinical validation, comprehensive interpretation suites and strong clinical service networks.
- High‑growth disruptors: AliveCor, QT Medical and HeartBeam are representative of a new cohort that combines simplified lead technologies, single‑use sensors or synthesized 12‑lead algorithms with AI diagnostics and novel commercial channels. AliveCor’s FDA clearance for an expanded AI engine (early 2026) and HeartBeam’s cable‑free 12‑lead clearance and first commercial contract in late 2025/early 2026 demonstrate how regulatory wins quickly translate into go‑to‑market momentum.
- Low‑cost and emerging market suppliers: Several regional manufacturers are intensifying competition in price‑sensitive segments, while also raising quality and interpretive capability — pressuring margin structures for OEMs that do not differentiate.
Recent developments that change strategic calculus
- Regulatory clearances in 2025–2026 for next‑generation AI engines and synthesized 12‑lead software have created a clearer pathway for handheld and at‑home ECG systems to obtain reimbursement and clinical acceptance.
- Public‑sector pilot programs and early EMS deployments highlight demand from emergency medicine and community health services for compact, fast‑deploy ECG systems that reduce time‑to‑diagnosis.
- Reimbursement policy updates — particularly CMS recognition of algorithmically generated 12‑lead interpretations in certain outpatient settings — materially influence purchase economics and TCO calculations, enabling alternative procurement models.
Strategic implications for enterprise action in 2026
For corporate leaders weighing product roadmaps, M&A targets, channel expansion or go‑to‑market pivots, the report translates market north‑star metrics into operational actions. Below are five priority moves we recommend for 2026:
- Prioritize software‑first product platforms: Convert hardware sales into platform relationships by embedding interpretive engines and subscription services. Focus R&D investment on algorithms that can be modularly updated and certified across geographies.
- Build EMS / at‑home go‑to‑market pilots: Allocate resources to fast‑track clinical validation and small‑scale deployments with EMS providers and preventive cardiology clinics. Early wins in these channels signal broader commercial viability and accelerate payer acceptance.
- Reassess pricing and service models: With device commoditization in certain tiers, introduce outcome‑linked service packages, per‑use interpretive licensing and managed device programs to protect margin pools.
- Targeted M&A and partnerships: Use bolt‑on M&A to acquire AI talent, unique sensor IP or regional distribution strength. Strategic alliances with EHR vendors and telehealth platforms accelerate clinical integration and account access.
- Regulatory and reimbursement playbooks: Invest in regulatory strategies that preemptively align device labeling with emerging CPT/Medicare pathways. Document clinical utility in EMS and outpatient settings to maximize reimbursement capture.
What the PW Consulting report delivers (practical content)
Our Worldwide 12 Channel Electrocardiograph Market report is built as an operational toolkit for decision-makers. Key deliverables include:
- Granular, auditable market sizing and forecasts (2020–2032) with scenario variants for conservative, base and accelerated adoption pathways;
- Segmentation matrices and demand drivers by product archetype, end‑user cohort and region (note: detailed subsegment tables are part of the paid research deliverable);
- Competitive benchmarking across 14+ vendors, including product feature maps, go‑to‑market archetypes and an acquisitions heatmap;
- Regulatory and reimbursement dossier detailing device classification, recent FDA 510(k) outcomes, CPT code dynamics and payer implications for algorithmic ECGs;
- Commercial playbooks for penetrating EMS, home‑care and preventive cardiology channels, with sample KPIs and procurement evaluation checklists;
- M&A and partnership decision framework with valuation heuristics tailored to device vs. software‑heavy targets;
- Risk register and mitigation plans covering supply chain, regulatory timing and clinical adoption hurdles.
Why PW Consulting’s analysis matters to 2026 planning
Many organizations habitually treat ECG devices as low‑complexity capital purchases. Our analysis reframes 12‑channel electrocardiographs as the nexus of several strategic vectors — device, software, channel and regulatory — that together determine long‑term economics. The combination of steady market expansion (6.45% CAGR in our base scenario), moderate concentration and rapid technological change creates windows for both incumbent defense and challenger disruption in 2026. Firms that align product architectures, commercial models and regulatory strategies now will capture outsized returns as adoption migrates to new settings.
Note on data disclosure and next steps
Consistent with the “teaser” intent of this release, we have presented market‑level figures and strategic insight while withholding detailed subsegment tables (regional splits, product‑type dollar shares, and application percentiles) to preserve the commercial integrity of the full report. Organizations seeking the complete dataset, downloadable Excel models, and tailored briefing sessions may obtain the full Worldwide 12 Channel Electrocardiograph Market report via our official report page. The full deliverable also includes bespoke scenario runs for investor diligence, procurement RFP support templates and a one‑hour executive briefing option with our senior analysts.
To arrange a briefing or to license the complete report and forecast models, please contact PW Consulting through the report landing page. Our team stands ready to transform these market signals into a prioritized, executable 90‑day plan for your organization.
For detailed analysis of this topic, please visit the official page: Worldwide 12 Channel Electrocardiograph Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com