

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Automotive ECS Acceleration Sensor Market to Expand from USD 682.5 Million in Base Year 2025 to USD 1,034.39 Million by 2032 at a 6.12% CAGR — MEMS (USD 525.64M), Asia Pacific (USD 290.01M) and Luxury Cars (USD 440.86M) Lead; CR3 at 54.2%

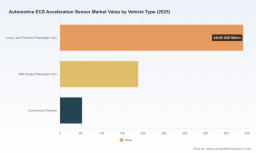
PW Consulting: Strategic Brief — Worldwide Automotive ECS Acceleration Sensor Market (Executive Trailer for 2026 Decision-Makers)
Executive summary
PW Consulting today publishes a strategic industry brief accompanying our forthcoming comprehensive report, "Worldwide Automotive ECS Acceleration Sensor Market." Built on a robust historical window (2020–2025) with a base year of 2025 and a detailed forecast horizon (2026–2032), the analysis synthesizes market sizing, technology trajectories, supplier positioning, regulatory drivers, and executable commercial playbooks targeted at OEMs, Tier‑1s, component suppliers, and private equity investors. Our top‑line findings show the market expanding from approximately USD 511.4 Million in 2020 to USD 682.5 Million in 2025, and we forecast continued growth to about USD 1,034.4 Million by 2032, reflecting a compound annual growth rate (CAGR) of 6.12% over the 2026–2032 period. This brief highlights the strategic implications of that trajectory while intentionally withholding detailed subsegment figures to drive deeper engagement with the full report.
Worldwide Automotive ECS Acceleration Sensor Market
Why this matters for 2026 corporate strategy
- Decision windows are compressing: the sensor roadmap and supplier consolidation trends mean 2026 is the year to lock in partnerships, component roadmaps, and volume agreements to influence 2028–2030 vehicle platforms.
- Regulation is non‑negotiable: Electronic Stability Control (ESC) mandates and safety expectations continue to raise the floor for accelerometer performance and functional redundancy, making EMC/qualification and long‑term supply certainty strategic priorities.
- Technology choices determine margins: MEMS‑based low‑g accelerometers remain the dominant technical approach; suppliers and OEMs that optimize for scalable silicon MEMS fabrication and integrate robust digital interfaces (e.g., PSI5/DSI3 families) will command the best cost‑performance curves.
Market trajectory — what the headline numbers conceal
The market’s macro path from just over USD 500 Million in 2020 to an expected USD 1.03+ Billion by 2032 is not linear: 2025 functions as an inflection base, with modest year‑on‑year growth into 2026 followed by accelerated adoption as active suspension architectures scale across vehicle segments and electronic chassis systems migrate from premium to broader vehicle platforms. The reported CAGR of 6.12% over 2026–2032 captures not only steady volume growth but also a structural shift in value per vehicle — driven by higher sensor counts per chassis, increased functional safety requirements, and emergence of multi‑axis, higher‑precision modules for integrated vehicle dynamics control.
Worldwide Automotive ECS Acceleration Sensor Market
For executives, the implication is clear: short‑term procurement decisions (2026–2027) determine share of wallet for the 2028–2030 vehicle generations. Capital allocation into MEMS capacity, strategic long‑term purchase agreements, and targeted technical partnerships will disproportionately affect P&L through the early 2030s.
Worldwide Automotive ECS Acceleration Sensor Market
Competitive landscape — players, capabilities, and strategic moves
The market is concentrated: the top three suppliers account for a majority share and the top five capture an even larger portion of market revenue, indicating an oligopolistic structure that raises barriers to new entrants but also creates opportunities for nimble challengers with differentiated offerings.
- Bosch (Gerlingen, Germany) — A mature provider with low‑g accelerometer architectures tailored for active suspension (e.g., single‑axis sensors for chassis acceleration). Bosch’s integration capability across system electronics and vehicle dynamics positions it as a preferred partner for OEMs pursuing vertically integrated ECS solutions.
- Murata Manufacturing (Nagaokakyo, Japan) — Known for combined gyro‑acceleration modules and compact form factors optimized for real‑time suspension adaptation. Murata’s strength lies in miniaturization and module integration for constrained chassis spaces.
- CTS Corporation (Elkhart, Indiana, USA) — Recent product launches (multi‑axis chassis sensors announced in early 2025) underscore CTS’s push to compete on functional breadth and digital interface support (PSI5). CTS is positioning to serve both legacy and next‑gen ECU architectures.
- STMicroelectronics (Geneva, Switzerland) — Offers AEC‑Q100 qualified automotive MEMS accelerometers, emphasizing qualification readiness for safety critical applications and strong analog/digital signal chain expertise.
- NXP Semiconductors (Eindhoven, Netherlands) — Combines accelerometer offerings with broader vehicle networking and MCU capabilities, enabling system‑level integration that reduces ECU complexity for OEMs.
- Analog Devices (Wilmington, Massachusetts, USA) — Focused on high‑performance inertial solutions and multi‑sensor fusion, targeting applications where dynamic range and precision materially affect control algorithms.
Recent industry steps underline competitive intensity: CTS’s January 2025 multi‑axis sensor launch and third‑party comparative studies released in 2025 reflect accelerating product development and benchmarking activity. OEMs and Tier‑1s are aggressively field‑testing differentiated modules, forcing suppliers to advance both sensor performance and system integration features at pace.
Technology and supply‑chain dynamics
Two technological constants will shape supplier economics and OEM procurement over the next five years:
- Silicon MEMS fabrication is the cost and scale lever. Low‑g MEMS accelerometers remain the foundational technology for ECS applications, offering the precision and cost advantages required for broad deployment.
- Robust digital interfaces are non‑optional. Protocols such as PSI5 and DSI3 provide deterministic, resilient data paths to the ECU in harsh chassis environments; suppliers that deliver certified, hardened interface stacks reduce OEM integration risk and therefore win preference.
From a supply‑chain perspective, the high capital intensity of MEMS fabs, qualification timelines for AEC‑Q100 devices, and concentrated supplier market shares create asymmetric risks. Component lead times, wafer capacity allocation decisions, and the ability to absorb raw material volatility will determine which suppliers can meet OEM ramp schedules. Our full report models supply stress scenarios and quantifies potential revenue and lead‑time impacts under different disruption assumptions.
What the PW Consulting report delivers — practical, executable content
We designed the report as a decision tool for 2026 investments and procurement cycles. Key deliverables include:
- Market sizing and growth model calibrated to 2020–2025 actuals and a transparent forecast engine for 2026–2032 (expressed in USD Million), adaptable to client‑specific adoption and integration assumptions.
- Supplier scorecards — technology, capacity, qualification status, interface readiness (PSI5/DSI3), and program health indicators to inform short‑list and dual‑sourcing strategies.
- Technology roadmap and patent landscape — MEMS process nodes, packaging innovations, fusion with gyros, and pathway timelines for high‑precision modules.
- OEM go‑to‑market playbooks — negotiation levers, long‑term purchase agreement templates, integration timelines, and risk allocation clauses tailored to Tier‑1 and OEM procurement cycles.
- BOM benchmarking and cost‑curve analysis — empirical models to estimate per‑vehicle sensor cost as a function of volume, integration level, and qualification overhead.
- Scenario planning and supply‑chain stress tests — quantifying impacts of fab constraints, component shortage episodes, and regulatory tightening on availability and pricing.
- M&A and partnership framework — valuation heuristics for bolt‑on MEMS players, integration risk checklists, and suggested diligence questions focused on IP, capacity, and qualification backlog.
Strategic imperatives for 2026
- Lock capacity, not juste price: secure wafer and assembly capacity windows through long‑lead agreements tied to performance milestones to ensure ramp continuity for 2028 platform programs.
- Prioritize interface and qualification readiness: demand PSI5/DSI3 and AEC‑Q100 compliance as table stakes when shortlisting suppliers; include software and verification deliverables in contracts.
- Differentiate through system integration: OEMs and Tier‑1s should seek suppliers that provide sensor + signal conditioning + diagnostics stacks to reduce ECU complexity and accelerate feature validation.
- Use multi‑scenario sourcing strategies: balance incumbent relationships with targeted investments in emerging specialists (e.g., MEMS innovators or module integrators) to mitigate concentration risk.
- Prepare for value migration: as active suspension and ECS functionalities expand beyond premium segments, pricing and feature mix will shift — plan product portfolios and R&D roadmaps accordingly.
Why PW Consulting
Our analysis combines bottom‑up component economics, supplier primary interviews, lab validation inputs, and scenario‑based forecasting to translate technical complexity into boardroom‑ready recommendations. The report is tailored to the 2026 decision cadence: procurement cycles, platform commitments, and capital allocation windows that determine market share across the 2028–2032 plateau.
Access and next steps
The above is a strategic trailer: it demonstrates the analytical depth and practical orientation of our work while reserving the granular subsegment breakouts, supplier revenue shares, and client‑grade Excel models for the full report. To access the detailed segmentation, supplier scorecards, downloadable models, and our recommended negotiation templates, visit the PW Consulting report page (link available in the footer of this release) or contact our sales team to arrange a briefing.
Note: PW Consulting has deliberately omitted the detailed subsegment tables and proprietary supplier revenue breakdowns from this release to protect client confidentiality and to preserve the actionable value of the full dataset included in the paid report.
For inquiries, briefing requests, or to license our market model for internal use, contact PW Consulting’s Automotive Practice. Equip your 2026 planning with the foresight to convert market growth into sustainable competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive ECS Acceleration Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com