

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Medical Powered Air‑Purifying Respirators Market to Grow at 6.32% CAGR, Reaching USD 590.47 Million by 2032

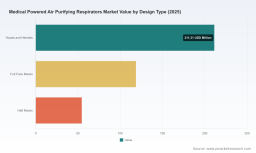
Worldwide Medical Powered Air Purifying Respirators Market: Strategic Insights for 2026 Decision-Makers
PW Consulting’s latest market research brief on the Worldwide Medical Powered Air Purifying Respirators (PAPR) market delivers targeted intelligence designed to shape resilient commercial strategies in 2026 and beyond. Drawing on a rigorous base-year analysis (2025), multi-year historical tracing (2020–2025), and a forward-looking forecast (2026–2032), the study synthesizes regulatory inflection points, procurement signals, and supplier positioning into pragmatic guidance for executives, investors, and procurement leaders. This release highlights the strategic value of the report while preserving the granular segmentation and proprietary datasets that subscribers rely on to execute decisions.
Worldwide Medical Powered Air Purifying Respirators Market
Market trajectory: the numbers that matter (high level)
The medical PAPR market shows a clear path of adjustment and recovery from the pandemic-era shock. After a pronounced retraction in the early 2020s, the market stabilized through 2024 and reached a robust base in 2025. Our base-year assessment identifies 2025 as the reference point for planning, and our forecast projects steady expansion through 2032 at a compound annual growth rate (CAGR) of 6.32%. By 2026 the market is poised to continue its recovery trajectory and, under the scenarios modeled in the full report, it reaches materially higher levels by 2032 as healthcare systems, pharmaceutical manufacturers, and laboratory operators accelerate investment in higher-protection respiratory solutions.
Worldwide Medical Powered Air Purifying Respirators Market
Those macro dynamics reflect two simultaneous forces: a structural reset in routine demand following pandemic peak stockpiling, and a sustained, technology-driven upswing in adoption where PAPRs deliver operational benefits—reusable platforms, improved wearer comfort, and simplified compliance pathways—that outpace single-use alternatives over multi-year capital cycles.
Worldwide Medical Powered Air Purifying Respirators Market
Why this report is strategic for 2026 planning
- Regulatory inflection points are accelerating buyer decisions. Recent policy activity—ranging from federal proposals that may narrow medical evaluation requirements for loose-fitting PAPRs to continued NIOSH filter-class standards—changes the compliance calculus for hospitals, EMS, and industrial healthcare users. These shifts reduce a subset of adoption frictions while simultaneously raising the bar on documented filtration performance and approvals.
- Procurement windows are opening within large public health systems. High-value solicitations and centralized purchasing programs are being issued that favor pre-qualified PAPR systems with established approvals and lifecycle service plans. These institutional signals make 2026 a critical year to convert R&D and regulatory preparedness into winning contract positioning.
- Consolidation and competitive concentration create both opportunity and risk. The market displays a concentrated supplier structure—our concentration metrics indicate that the top-tier manufacturers control a majority share of commercial supply. For new entrants and niche players, this intensifies the importance of route-to-market partnerships, differentiated value propositions, and service-led models.
- Reimbursement and cost-accounting pressures persist. Policy mechanisms that adjust payment to reflect the cost differential of higher-protection PPE influence hospital purchasing behavior—making lifecycle cost models and demonstrable operational ROI essential for market penetration.
Competitive landscape: positioning the core players
The competitive map is diverse: multinational industrial safety incumbents, specialized medical PPE innovators, and a small set of NIOSH-focused manufacturers that occupy high-protection niches. The full report provides proprietary profiles and capability matrices, but the strategic implications are evident from public positioning and recent moves:
- 3M Company — A broad platform player offering Versaflo PAPR systems tailored to healthcare environments, with an emphasis on HEPA-grade filtration and headtop compatibility. 3M’s ecosystem approach makes it a default contender in bundled PPE procurements.
- MSA Safety Incorporated — Aggressively expanding distribution reach through partnerships (notably an exclusive North American distribution tie-up for optrel PAPR models announced in 2024). MSA’s strategy underscores the role of channel breadth in achieving scale quickly.
- Bullard — Focuses on reusable PAPR systems across healthcare and high-purity manufacturing settings; its service and upgrade programs illustrate how aftermarket propositions extend product economics.
- Syntech, Int’l Inc. (Maxair Systems) — A specialized player and sole NIOSH-approved manufacturer for a specific CAPR line; notable for surgical and sterile-processing credentials that make it attractive to hospital and OR buyers.
- ILC Dover — Targets pharmaceutical and biopharma operations with very high assigned protection factors and clear-hood solutions, positioning itself where contamination control is mission-critical.
- Gentex Corporation, GVS-RPB (RPB Safety), Drägerwerk, Honeywell, Avon Protection — These suppliers collectively illustrate the mix of healthcare-endorsed offerings and industrial lineage entering medical use cases; each brings differentiated strengths in approvals, global reach, or ergonomic design.
Recent industry activity underscores the competitive dynamics: exclusive distribution agreements, public sector solicitations for backpack PAPR systems, and regulatory proposals that change compliance burdens. Each move re-rates supplier value depending on approval status, service footprint, and ability to demonstrate real-world cost amortization.
What the full report contains (practical, operational deliverables)
PW Consulting’s comprehensive deliverable is structured to convert insight into action for 2026 initiatives. Highlights include:
- Top-line market sizing and validated forecasts (historical 2020–2025 and forward to 2032) presented in monetized, scenario-based views.
- Concentration and competitive scoring (including CR metrics) and an acquisition-target shortlist based on strategic fit and capability gaps.
- Regulatory-impact models that quantify adoption sensitivity to NIOSH approvals and pending OSHA/MSHA rule changes—allowing you to stress-test investment timelines.
- Go-to-market playbooks for hospital systems, pharmaceutical manufacturing, and laboratory channels—covering contracting levers, proof-of-value studies, and service/maintenance economics.
- Procurement intelligence and bid-prep templates aligned with public-sector solicitations and private group purchasing organizations.
- Operational due-diligence checklists for product lines (design for cleanability, APF performance, headtop ergonomics) and manufacturing ramp scenarios.
- Aftermarket and consumables revenue models to help justify capital investment in reusable PAPR architectures.
We intentionally keep the most actionable segment-level matrices and point-estimate volume flows behind the subscription wall—this “teaser” approach preserves the competitive advantage our clients require while demonstrating the breadth of analytic work available.
How to use these insights to set 2026 priorities
- Investment prioritization: Use our scenario outputs to set R&D and capital allocation timelines. For established suppliers, prioritize conversions of surgical and sterile-processing customers by showcasing clearance and lifecycle cost comparisons. For new entrants, target service-enabled niches where incumbents’ distribution is weakest.
- Regulatory & reimbursement play: Model the commercial impact of the latest OSHA and MSHA proposals and align submissions with NIOSH approval pathways. Where reimbursement adjustments exist, translate them into purchasing incentives for health systems.
- Commercial execution: Rework sales compensation and channel incentives to reward contract wins with long-duration service components. Position bundled offers (blower + headtops + service) as the default procurement choice for large systems.
- M&A and partnership screening: Target assets that accelerate market access (distribution deals, exclusive partnerships) or that provide differentiated regulatory approvals and APF performance—especially in pharmaceutical cleanrooms and surgical theaters.
- Operational resilience: Strengthen supply chain redundancy for critical components (filters, blowers, batteries) and lock in manufacturing capacity to avoid the mismatch between surge demand and lead times that characterized prior cycles.
Methodology and credibility
The report is built on a mixed-method approach: quantitative market modeling calibrated to public procurement data and proprietary supplier disclosures, augmented by expert interviews across healthcare procurement, occupational safety, and regulatory affairs. Base-year currency is reported in USD (units in millions) and the forecast horizon extends to 2032. We explicitly model upside and downside adoption scenarios and stress-test them against regulatory permutations and procurement cadence changes.
Key policy references and recent developments factored into our modeling include federal rule proposals affecting medical evaluation exemptions for loose-fitting PAPRs, NIOSH’s current approval standards for filters used in healthcare settings, and public-sector solicitations indicating near-term demand from integrated health systems.
Next steps — how to get the full intelligence
For executives planning 2026 investments, the full report provides the segment-level demand curves, regional and end-user breakdowns, supplier scorecards, and transaction comparables needed to finalize business cases and board-level asks. PW Consulting’s advisory team is available to walk through bespoke scenarios, validate pricing and reimbursement impacts, and support commercialization roadmaps.
To obtain the complete dataset, proprietary segmentation details, and supplier benchmarking tables that are essential for bid preparation and M&A diligence, please visit our report page or contact a PW Consulting client manager. The granular component of the analysis—where we quantify specific regional and application allocations and present supplier unit economics—remains available only to subscribers and advisory clients.
2026 is a pivotal planning year. The right combination of regulatory foresight, procurement agility, and service-led commercial models will determine who captures durable value as the market transitions from episodic demand to sustained, capability-driven adoption. Our report gives you the evidence base to make those choices with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Medical Powered Air Purifying Respirators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com