

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Rescue Hoists & Cargo Winches Market to Rise from USD 785.4 Million in 2025 to USD 1,136.46 Million by 2032 at a 5.42% CAGR

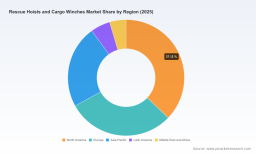
Worldwide Rescue Hoists and Cargo Winches Market: Strategic Imperatives for 2026 Decision‑Makers
PW Consulting’s new market study—base year 2025, historical coverage 2020–2025 and a forecast horizon extending from 2026 through 2032—maps the operational, regulatory and commercial contours that will shape procurement, product development and sustainment strategies in the rescue hoist and cargo winch ecosystem. The global market has expanded from roughly USD 608 million in 2020 to about USD 785 million in 2025, and we project continued expansion through the forecast window (compound annual growth rate ~5.42%), with expected market size variability as platforms, certification timelines and raw‑material cycles re‑price cost bases toward 2032.
Worldwide Rescue Hoists and Cargo Winches Market
Why 2026 Is a Pivotal Year
-
Program timing: 2026 is the inflection point where near‑term sustainment contracts and mid‑life upgrade cycles for rotary‑wing fleets intersect with new procurement programs for next‑generation platforms. Decisions made in 2026 will determine which suppliers capture durable aftermarket revenue streams across the following decade.
Worldwide Rescue Hoists and Cargo Winches Market -
Regulatory synchronization: FAA and EASA certification requirements (and related military testing mandates) are converging on higher performance and environmental standards. That creates compressed windows for compliance certification prior to major platform deliveries.
Worldwide Rescue Hoists and Cargo Winches Market -
Supply‑side stress: material innovation (e.g., HMPE synthetic rope adoption) and conventional alloy shortages are re‑shaping cost and performance tradeoffs—forcing procurement teams to choose between up‑front systems upgrades and long‑term lifecycle savings in service arrangements.
Market Dynamics: Forces That Will Drive 2026 Decisions
-
Demand drivers. Operational tempo for search & rescue and sustained military readiness keep hoist and winch requirements non‑discretionary for many operators. At the same time, expanding commercial utility missions introduce differentiated payload, integration and certification needs that complicate one‑size‑fits‑all solutions.
-
Regulatory tailwinds. Regulatory instruments are materially influencing design requirements. For example, FAA TSO provisions and EASA acceptable‑means documents are mandating higher proof loads, emergency‑release capabilities and overload performance—changes that ripple through design, testing and supplier qualification timelines.
-
Materials and supply volatility. The sector is in active transition: high‑modulus polyethylene (HMPE) ropes deliver dramatic strength‑to‑weight advantages (technical studies cite ~15× improvements over traditional steel wire on a strength‑per‑weight basis), while steel‑alloy shortages have driven near‑term price inflation for wire rope and drum components. These mixed signals are inducing both risk premia in sourcing and opportunity windows for lightweight innovations.
-
Consolidation & concentration. The market exhibits high concentration among a small set of established suppliers, reinforcing pricing power for incumbents but also leaving room for new entrants with disruptive payload or integration capabilities to win niche positions.
Competitive Landscape: What the Leading Players Are Signaling
Our industry tracking and primary research highlight four market leaders that define current competitive dynamics—and their recent activities offer useful leading indicators for strategy.
-
Collins Aerospace (Cedar Rapids, IA) : Known for electro‑mechanical rescue hoists and cargo winches serving both military helicopter platforms and civil SAR operations. Recent trade‑show unveiling of an enhanced rescue hoist with a higher load rating signals a continued emphasis on platform‑level integration and performance differentiation. Strategic implication: Collins is investing to protect OEM integration pathways and win retrofit contracts tied to platform modernization programs.
-
Breeze‑Eastern (Whippany, NJ) : A specialist in high‑capacity rescue hoists and military winch sustainment. Recent contract deliveries under US government sustainment arrangements emphasize the company’s strength in logistics and legacy platform support. Strategic implication: Breeze‑Eastern’s playbook centers on deepening aftermarket services and leveraging long‑term sustainment obligations to stabilize revenue and margins.
-
Onboard Systems International (Vancouver, WA) : Focused on lightweight cargo winches and modular hook systems for commercial and utility platforms. The recent Matrix 600 launch with remote hook capability indicates a push into heavy‑lift commercial missions and off‑board autonomy. Strategic implication: Onboard is positioning to capture commercial growth and to be an attractive partner for OEMs seeking modular, mission‑flexible subsystems.
-
Tractel (Saint‑Hubert, Quebec) : Provider of both electric and hydraulic winches for aerial and industrial use. Their breadth across actuation types gives them the flexibility to address mixed fleets and unconventional use cases. Strategic implication: Tractel’s multi‑technology portfolio makes it a resilient provider in environments where platform diversity and retrofit complexity matter.
Viewed together, these actions illustrate two concurrent strategic trajectories: incumbent OEMs and sustainment specialists protect installed bases and compliance capabilities, while niche and modular suppliers pursue fast‑growing commercial and utility missions. With three firms historically controlling a large portion of the market and the top five commanding an even larger share, strategic moves by any of these players can materially shift procurement dynamics for operators and Tier‑2 suppliers alike.
What PW Consulting’s Report Delivers: Practical, Decision‑Ready Assets
Our report is deliberately structured to convert market intelligence into executable steps for 2026 planning cycles. Highlights include:
-
Executive scenarios (2026–2032): three investment and procurement scenarios that translate macro forecasts into procurement pathways by risk appetite and mission profile.
-
Certification and compliance playbook: a sequenced checklist aligning design decisions with FAA, EASA and DoD testing regimes including environmental (MIL‑STD‑type) testing considerations.
-
Supplier risk heatmap and resilience matrix: supplier concentration, single‑source exposure, and raw‑material dependency mapped to recommended mitigation actions (dual sourcing, hedging, vertical integration options).
-
Total cost of ownership (TCO) model: scenarioable TCO calculators that capture initial acquisition, certification costs, rope lifecycle, maintenance intervals and service network tradeoffs.
-
Procurement templates and negotiation levers: contract clauses, sustainment KPIs and obsolescence management language tailored for military, SAR and commercial purchasers.
-
M&A and partnership radar: target profiles and valuation sensitivity for potential bolt‑on acquisitions or joint ventures focused on HMPE rope systems, advanced drum manufacturing or autonomous release mechanisms.
Note: the report contains granular segmentation tables, country‑level demand models and supplier market‑share data that are intentionally reserved for the full report to preserve its actionable value.
Implications for Key Stakeholders
-
OEMs and Prime Integrators —Prioritize certification pathways and embedded subsystem strategies; consider co‑development agreements with HMPE rope specialists to reduce integration timelines and improve weight performance.
-
Tier‑1 Suppliers —Lock in alloy supply and drum manufacturing capacity via multi‑year contracts; accelerate modularity to serve both military sustainment and commercial lift markets.
-
Operators (EMS, SAR, Utility) —Adopt a lifecycle procurement approach: purchase decisions should weigh short‑term acquisition savings against longer‑term fleet availability, rope replacement cycles and certification costs.
-
Procurement Agencies & Defence Planners —Integrate certification milestones into contract award timelines to avoid retrofit cost escalations; consider total‑life service contracts to transfer technical risk.
-
Private Investors & M&A Teams —Target high‑margin aftermarket capabilities and HMPE value chain technologies; assess portfolio resilience against raw‑material inflation scenarios and regulatory shifts.
A Compact Strategic Playbook for 2026
-
Secure critical materials: lock long‑lead steel and HMPE supplies through contracts and vendor partnerships to stabilize pricing and availability.
-
Prioritize certification early: invest in pre‑certification testing and simulation to shorten time‑to‑market and reduce retrofit risk.
-
Design for serviceability: modular hoist and winch architectures lower lifetime operating costs and improve upgrade flexibility across platform families.
-
Monetize aftermarket: build predictable recurring revenue streams via maintenance bundles, spare‑parts subscriptions and certified sustainment services.
-
Validate strategic M&A: target assets that accelerate HMPE integration, drum manufacturing, or remote/lift automation capabilities.
Conclusion — Where PW Consulting Adds Value
For organizations drafting budgets, negotiating sustainment contracts or defining R&D pipelines in 2026, the choice is between reactive procurement and proactive market positioning. Our study synthesizes performance forecasts, regulatory timelines and supplier actions into a pragmatic roadmap that helps you prioritize investment, manage supplier risk and capture aftermarket value. The public synopsis above intentionally highlights trends and implications while reserving the detailed segmentation, countrylevel forecasts and supplier market shares for the full report—where you will find the precise data and downloadable tools to execute on the strategies summarized here.
To review the full dataset, scenario models and procurement templates that inform these recommendations, please visit the PW Consulting report page or contact your PW Consulting account team for the complete Worldwide Rescue Hoists and Cargo Winches Market report. We stand ready to help you translate insight into a 2026 action plan tailored to your mission and risk posture.
For detailed analysis of this topic, please visit the official page: Worldwide Rescue Hoists and Cargo Winches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com