

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Gardner Syndrome Treatment Market Poised for 4.5% CAGR, Expected to Reach USD 572.25 Million by 2032 (Base Year 2025)

Worldwide Gardner Syndrome Treatment Market — Strategic Outlook and Action Guide for 2026 Decision-Makers
PW Consulting’s latest market intelligence brief on the Worldwide Gardner Syndrome Treatment Market delivers a compact, decision-focused synthesis for executives preparing 2026 strategies. Built on a rigorously validated market model with a 2025 base year and a 2026–2032 forecast horizon, the study projects a steady compound annual growth rate (CAGR) of 4.5%. The global market expands from an estimated USD 420.5 Million in 2025 to an anticipated USD 572.25 Million by 2032, driven by clinical innovation, evolving surveillance standards, and the regulatory economics of orphan-indication development.
Worldwide Gardner Syndrome Treatment Market
Why this report matters in 2026
Gardner syndrome — a phenotypic variant of familial adenomatous polyposis (FAP) — remains a high-priority niche for both clinical development and commercial strategy. Its rarity (incidence roughly 1 in 8,300 live births) creates an unusual mix of constraints and incentives: small patient populations limit peak revenue but enhance the strategic value of orphan exclusivity, expedited regulatory pathways, and premium pricing where clinical differentiation is clear.
Worldwide Gardner Syndrome Treatment Market
- Strategic timing: With recent regulatory activity and new product entries reshaping the treatment landscape, 2026 will be a pivotal year for firms to consolidate market access and evidence-generation programs.
- Market structure: The sector exhibits moderate concentration — the top three and five players control meaningful but not dominant shares — leaving tactical room for new entrants that can demonstrate clear clinical or economic value.
- Clinical and commercial inflection points: Advances in pharmacological regimens that reduce polyp burden, coupled with improved endoscopic and surveillance capabilities, are changing the calculus for when and how surgical intervention is used in the disease course.
What the numbers tell you (high-level)
Our historical series (2020–2025) and forecast indicate resilient, mid-single-digit growth through 2032. Growth drivers include greater adoption of pharmacological adjuncts, increasing emphasis on early and continuous surveillance, and a steady pipeline of agents and combination regimens aimed at reducing the need for colectomy. At the same time, the market’s rare-disease nature concentrates pricing and reimbursement risk in a small patient base, so commercial returns hinge on differentiated clinical data and smart market-access strategies.
Worldwide Gardner Syndrome Treatment Market
Competitive landscape — implication for incumbents and challengers
Two corporate archetypes currently shape market dynamics: established multinational pharmaceutical firms with broad commercialization capabilities and smaller specialty companies focused on orphan indications. For example:
- Pfizer Inc. is active in the therapeutic mix for FAP-associated conditions through an established anti-inflammatory adjunct that is commonly used in surveillance and polyp-reduction strategies. As a global contender, Pfizer’s strengths are regulatory experience, scale in market access, and an existing commercial footprint in gastroenterology and oncology settings.
- Azurity Pharmaceuticals recently secured FDA approval (November 2024) for a combination pharmacologic option that demonstrated a clinically meaningful reduction in polyp burden in Phase 3 data. The product benefited from orphan-designation incentives earlier in development, illustrating how targeted regulatory strategy can materially alter commercial prospects for smaller firms.
These examples illustrate a broader strategic pattern: large firms compete on reach and portfolio breadth, while specialty players leverage agile development, targeted evidence generation, and orphan incentives to build attractive M&A or licensing positions. For 2026, companies on both sides of this divide must answer three core questions: How will we prove differentiated value? How will we secure reimbursed access in a small but high-cost patient population? And how quickly can we scale post-launch?
Regulatory and reimbursement dynamics — key considerations
- Orphan-incentive economics: The U.S. Orphan Drug Act and analogous frameworks remain powerful enablers. Typical benefits — including market exclusivity and R&D tax credits — materially improve project net present value for breakthrough or first-in-class treatments.
- Evidence expectations: Payers increasingly expect both hard clinical outcomes (e.g., polyp burden reduction, colectomy delay) and real-world evidence demonstrating cost offsets from avoided surgeries and surveillance costs. Early health-economic modeling and registry planning are now strategic imperatives.
- HTA variability: Differences across health technology assessment regimes mean manufacturers must prepare tiered evidence and pricing strategies — from label optimization to value-based contracting pilots.
Report deliverables — what you get in the full study
PW Consulting’s report is structured for immediate application by corporate strategists, BD&L teams, and market-access leaders. Key practical components include:
- Comprehensive market model (historical 2020–2025; forecasts 2026–2032) with scenario sensitivity and upside/downside cases
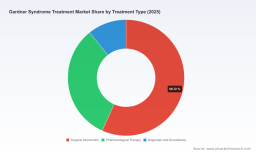
- Granular segmentation by geography, treatment modality (surgical, pharmacological, diagnostics/surveillance), and end-user channels, with downloadable data cubes (note: detailed segment tables are provided in the full report)
- Pipeline and clinical-trial mapping, including mechanism-of-action, development stage, and competitive overlap analysis
- Profiles and strategic assessments of key companies and late-stage assets
- Market-access playbooks: payer evidence requirements, pricing benchmarks, and contracting options for orphan products
- Operational readiness checklist: manufacturing scale-up, distribution, and specialty pharmacy considerations
- Investor-grade risk matrix highlighting clinical, regulatory, reimbursement, and manufacturing risks
Actionable recommendations for corporate leaders in 2026
- Prioritize value differentiation early: Investments in Phase 2–3 programs should include co-primary endpoints that align with payer priorities (e.g., colectomy avoidance, durable polyp reduction) and a pre-planned real-world evidence strategy to support downstream reimbursement.
- Leverage orphan incentives strategically: Secure regulatory advantages early (orphan designation, expedited pathways) and model exclusivity scenarios in valuation and pricing strategies.
- Design flexible commercialization paths: For smaller players, consider staged partnerships — retain label control while outsourcing distribution and market-access capabilities to specialists; for large firms, explore in-licensing or bolt-on acquisitions to broaden the therapeutic offering.
- Invest in diagnostics and surveillance integration: Treatments will achieve better uptake and stronger value propositions when paired with optimized surveillance protocols and diagnostic biomarkers that identify high-risk patients.
- Prepare payer conversations now: Build health-economic models and targeted RWE cohorts pre-launch. Early engagement with payers and HTA bodies reduces time-to-reimbursement post-approval.
- Targeted geographies and centers of excellence: Focus initial commercial roll-outs on clinical hubs that treat concentrated caseloads and can serve as RWE partners; scale geographically in subsequent waves as evidence and reimbursement mature.
- Scenario planning and capital efficiency: Use scenario-driven go-to-market plans to determine optimal capex timing for manufacturing and distribution.
How investors and corporate development teams should use this intelligence
For M&A and licensing teams, the most valuable outputs are the market model scenarios, the pipeline overlap map, and the company profiles with acquisition defensibility scoring. Investors should focus diligence on four dimensions: clinical durability, payer alignment, manufacturability, and the strategic fit of orphan exclusivity windows relative to projected peak sales. Our report distills these elements into a concise investment checklist tailored to the FAP/Gardner syndrome segment.
Next steps — where to get the full intelligence
This release is a strategic preview intended to orient 2026 decision-making. The full PW Consulting report contains the underlying segmentation tables, granular regional and treatment-type splits, detailed competitive benchmarking, and the downloadable market model that support actionable financial planning. Those core data tables and executable playbooks are intentionally withheld from this summary to preserve the integrity and commercial value of the full analysis.
To obtain the full report, detailed data cubes, and bespoke advisory engagement options, please visit our report page or contact PW Consulting’s market intelligence team. The complete study will enable your 2026 planning cycle with board-ready analysis, scenario-tailored financial models, and a tactical roadmap to convert clinical innovation into durable market access.
PW Consulting remains committed to translating rare-disease complexity into clear strategic choices. For organizations evaluating entry, expansion, or portfolio rationalization in the Gardner syndrome ecosystem, this report provides the prioritized intelligence required to act with confidence in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Gardner Syndrome Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com