

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Digital Paper System Market to Rise from USD 3,780 Million in 2025 to USD 10,696 Million by 2032 at a 16.02% CAGR

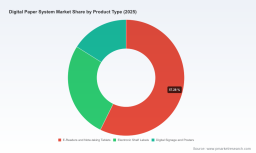
Worldwide Digital Paper System Market: Strategic Imperatives for 2026 Decision‑Makers
Executive summary
PW Consulting’s latest market study on Worldwide Digital Paper Systems equips executives with the strategic context and operational tools required to make high‑stakes decisions in 2026. The market has moved from a niche replacement technology to a diversified platform across signage, reading/annotation devices, ESLs and industrial digital paper applications. Our analysis shows the market expanding from roughly USD 1.85 billion in 2020 to an estimated USD 3.78 billion in 2025, with a projected compound annual growth rate (CAGR) of 16.02% through our forecast horizon. By 2032 the market trajectory points toward a multi‑billion‑dollar opportunity, underscoring why procurement, R&D, sustainability and partner selection choices made this year will materially affect total cost of ownership, brand positioning and supply resilience over the next decade.
Worldwide Digital Paper System Market
Why this matters for enterprise strategy in 2026
-
Energy and sustainability mandates are converging with procurement cycles: digital paper’s ultra‑low power profile and reduced paper consumption mean that sustainability goals are now a procurement advantage rather than a niche selling point.
Worldwide Digital Paper System Market -
Product diversification across color EPDs, large‑format signage, ESLs and flexible substrates is forcing buyers to balance device economics against lifecycle and integration costs—simple unit price comparisons are no longer sufficient.
Worldwide Digital Paper System Market -
Supply chain dynamics (materials for electrophoretic films, IGZO backplanes, and emergent bio‑resin housings) are reshaping supplier selection. Recent moves by major suppliers to expand capacity and form JVs signal accelerating consolidation and vertical integration in specific subsegments.
What the PW Consulting report delivers — practical, deployable intelligence
This research is structured to support both strategic and operational decision‑making. Core deliverables include:
-
Market sizing and scenario modelling calibrated to a range of adoption curves for enterprise verticals.
-
Decision frameworks and TCO templates that compare digital paper deployments against incumbent display and printed workflows across a five‑through‑ten year horizon.
-
Vendor scorecards and supplier risk heatmaps: multi‑criteria assessments covering technology roadmaps, production capacity, IP positions, and partner ecosystems.
-
Use‑case playbooks (education, retail/logistics, corporate document workflows, clinical documentation) with implementation milestones and measurable KPIs for pilot versus scale phases.
-
Regulatory and sustainability mapping that translates material claims (e.g., bio‑resin housings and UL verifications) into procurement and marketing strategies.
-
Negotiation playbooks for JVs, license agreements and volume commitments—designed to be executed within 90–180 day cycles.
Competitive landscape — who matters and why
The supply side is a mix of specialized module makers, large OEMs ramping color and large‑format capabilities, and vertically integrated display groups. Market concentration is meaningful but not prohibitive: the top three firms account for a substantial share of production capacity (CR3 ~42.5%) and the top five consolidate further (CR5 ~58.3%), indicating a market where partnerships matter and scale confers advantage, but where nimble entrants and focused specialists can still capture niche value.
Key company archetypes and strategic implications:
-
E Ink Holdings (Hsinchu, Taiwan) — the foundational electrophoretic technology owner and module supplier. E Ink remains the primary platform supplier for mainstream EPD applications. For buyers, E Ink’s partner network and module roadmap are critical determinants of cost, color roadmap and availability.
-
Sony Corporation (Tokyo, Japan) — targets secure, large‑format digital paper notepads for professional document workflows. Sony’s emphasis on document security and enterprise software integration makes it a preferred partner where content governance and annotation fidelity matter.
-
Sharp Corporation (Osaka, Japan) — combining E Ink electrophoretic films with IGZO backplanes to push color and scale. Their approach signals where industrial partnerships for backplane technology can unlock new signage and corporate display segments.
-
Samsung Electronics (Suwon, South Korea) — moving into color e‑paper with eco‑material housings and an explicit low‑power signage play. Samsung’s recent product launches indicate a strategy to leverage industrial scale and sustainability claims for B2B signage and paper‑replacement use cases.
-
Pervasive Displays & DKE — specialists optimized for ultra‑low‑power industrial IoT modules and ESLs. Their focus on embedded systems and long‑lifecycle performance makes them natural partners for logistics and retail edge deployments.
-
Plastic Logic & Ynvisible — representing innovation vectors: flexible plastic TFT EPDs and printed electrochromics respectively. These vendors are signals of the product innovations that could reframe use cases in wearables, shelf labels and battery‑less signage.
-
BOE, reMarkable, Fujitsu — BOE’s capacity play and the niche device players (reMarkable, Fujitsu) round out a market where both scale and differentiated UX matter. Device OEMs are increasingly pairing hardware with cloud document workflows—opening new value streams via subscriptions and content services.
Recent industry moves to watch: a major JV for large‑size EPD production announced in 2025, and new color/bio‑resin product introductions and showcases in early 2026. These validate our view that the industry is transitioning from component scarcity to capacity‑led competition in selected subsegments.
Industry dynamics and risks
-
Sustainability and certification: UL verification of bio‑resin claims and the overall lifecycle advantages of e‑paper are now a procurement consideration for public and private sectors.
-
Standardization pressure: Electrophoretic display (EPD) remains the dominant commercial standard; buyers should map supplier roadmaps to ensure compatibility and upgrade paths for color and refresh features.
-
Raw material and supplier concentration: Large‑format modules rely on coordinated supply of backplanes and electrophoretic films—enterprises should stress‑test procurement contracts for lead‑time and quality variability.
-
Technology obsolescence and differentiation: Printed electrochromics and flexible substrates are nascent but could disrupt mid‑volume product economics; monitor pilots and IP positions closely.
Strategic playbook for enterprises (concise, high‑impact actions)
For executives planning capital allocation, procurement, and product roadmaps in 2026, we recommend the following prioritized actions:
-
90‑day pilots: Deploy two tightly scoped pilots—one operational (e.g., ESLs or logistics tags) and one human‑centric (e.g., enterprise document workflows). Use our TCO template to capture actual energy, maintenance and user‑productivity metrics.
-
Supplier hedging: Establish primary and secondary sourcing with differentiated technology partners (one scale supplier, one innovation specialist) and secure options around capacity increases tied to JV outcomes.
-
Sustainability verification: Require third‑party verification for material claims (e.g., bio‑resins) and embed compliance milestones in procurement contracts to protect marketing claims.
-
IP and integration diligence: For product teams, align e‑paper hardware selection to software workflows (annotation, DRM, device management) to avoid costly rework during scale‑up.
-
M&A and partnerships: For investors, evaluate bolt‑on acquisitions that add unique substrate capability or differentiated low‑power drivers rather than broad display fabs which are capital intensive.
90‑day and 12‑month decision milestones
-
90 days: Execute pilots, finalize supplier scorecards, and lock minimal viable commercial agreements with clauses for capacity and quality SLAs.
-
6–12 months: Scale proven pilots to defined sites, implement lifecycle monitoring, and negotiate longer‑term supply or JV structures if upstream capacity constraints materialize.
Why PW Consulting’s report is the operational asset you need in 2026
Our methodology blends primary interviews across suppliers and buyers, proprietary supply‑chain mapping, and bottom‑up TCO and adoption modelling. The result is not only a forecast (we model a robust CAGR of 16.02% over the forecast window and provide granular scenarios for enterprise adoption paths) but also a suite of executable tools—scorecards, contract templates and pilot KPIs—that enable rapid, low‑risk decisions.
Next steps
This release is a strategic preview designed to surface the report’s core implications while preserving the detailed segment economics and proprietary supplier scoring that underpin tactical actions. For access to the full market model, detailed segment forecasts, company scorecards and the downloadable TCO toolkit—critical for negotiating 2026 procurement cycles—visit PW Consulting’s Worldwide Digital Paper System Market report page and request a briefing with our senior industry team.
For detailed analysis of this topic, please visit the official page: Worldwide Digital Paper System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com