

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Worldwide Sonobuoy Launcher Market to Reach USD 530.14 Million by 2032, Driven by a 5.46% CAGR

Worldwide Sonobuoy Launcher Market: Strategic Insights for 2026 Decision-Making
PW Consulting’s latest market study on the Worldwide Sonobuoy Launcher Market offers an executive-grade intelligence briefing designed to inform procurement, R&D, M&A, and alliance decisions in 2026. Built on a detailed base year (2025) analysis and a seven-year forecast window (2026–2032), the report synthesizes demand-side drivers, supplier capabilities, platform integration dynamics, and program-level procurement signals into a compact set of strategic actions. The global market is sized in USD (Million) and — after a short cycle of volatility earlier in the decade — stands at an elevated base in 2025, with the forecast pointing to sustained growth through 2032 at a compound annual growth rate (CAGR) of 5.46%.
Worldwide Sonobuoy Launcher Market
Why this report matters to executive teams in 2026
-
Practical foresight for capital allocation: In an environment where maritime and airborne anti-submarine warfare (ASW) modernization programs are accelerating, our analysis connects program budgets and platform roadmaps to near-term launcher demand and aftermarket services.
Worldwide Sonobuoy Launcher Market -
Supplier and supply-chain risk navigation: The study highlights critical material and manufacturing constraints for expendable launch containers and launch tubes, enabling procurement and operations leaders to prioritize dual-sourcing, strategic inventory, and industrial-base investments.
Worldwide Sonobuoy Launcher Market -
Integration playbooks for unmanned systems: As militaries explore sonobuoy launch integration with unmanned aerial and surface systems, the report maps feasible retrofit pathways and incremental capability investments to de-risk demonstrators and scale programs.
-
M&A and partnership signaling: With the launcher market characterized by a concentrated set of established OEMs and specialty suppliers, our competitive overlays and valuation heuristics identify where bolt-on acquisitions and technology partnerships can yield fastest path to capability and market access.
Market trajectory and what it implies for 2026 planning
After measuring the market across a historical window (2020–2025) and translating expected program flows into demand curves, PW Consulting projects steady expansion across the forecast period (2026–2032). The report quantifies the market in monetary terms at the 2025 base year, and models near-term demand reflecting both defense budget continuities and emergent requirements for multistatic and networked ASW. Key modeling assumptions include continued procurement in major ASW airframes, incremental adoption of pneumatic rotary and single-launch solutions, and the operationalization of expendable sonobuoy-launched payload concepts. These drivers underpin the 5.46% CAGR across the forecast horizon — a rate that is meaningful for investment decisions such as capacity expansion, long-lead component contracts, and supply-chain hedging.
Competitive landscape — who matters and why
The sonobuoy launcher market is shaped by a set of incumbent primes and specialized system integrators with deep platform heritage and fielded flight hours. PW Consulting’s competitive assessment focuses on technology alignment, program execution risk, and aftermarket sustainment economics.
-
L3Harris Technologies — With proven pneumatic rotary and single launch solutions that are reloadable in flight and fielded on major maritime patrol aircraft, L3Harris sits at the intersection of mature product offerings and platform upgrade programs. Their full-rate production status and Retrofit programs make them a focal partner for defense customers seeking low-risk modernization paths.
-
Ultra Maritime (Ultra Electronics) — An active developer of next-generation multistatic sonobuoys, Ultra’s work to align new sensor generations with existing launcher infrastructures positions it as both a systems supplier and a technology pathfinder for allied navies aiming to densify ASW sensing networks.
-
Lockheed Martin — Through program-level involvement and launcher upgrades, Lockheed’s role is less as a pure-play launcher OEM and more as an integrator leveraging platform relationships to influence launcher roadmaps and sustainment regimes.
-
Thales Group — Thales’ multi-platform launcher development, designed for both shipborne and airborne environments, and its advanced sonobuoy sensor portfolio illustrate a platform-agnostic strategy that appeals to customers aiming for interoperability across air and sea domains.
-
Specialists and niche suppliers — Firms such as Sparton (Elbit Systems group), Alkan, JSK Naval Support, Geospectrum, Marshall Aerospace, and MES deliver the range of componentry, composite launch tubes, and light stores dispensing units that underpin launcher system supply chains. These suppliers are critical for maintainability, obsolescence mitigation, and local-content strategies.
Recent contract activity reinforces these dynamics: prime contractors continue to secure production awards and retrofit contracts, while specialized vendors win program-specific sustainment and component-level competitions. For program managers and corporate strategists, this means that partnering models and bid strategies should balance proven field heritage with incremental innovation to remain competitive in 2026 solicitations.
Regulatory, materials, and capability trends shaping procurement risk
-
Budget continuity and industrial-base policy: Public budget documents indicate continued support for sonobuoy programs across core platforms. For suppliers, this creates a policy tailwind for capacity investments but also a requirement to maintain multiple qualified vendors for critical launcher components.
-
Materials and manufacturing: Launch containers and tubes rely on aluminum and composite materials to meet strict weight and durability constraints. Volatility in raw material availability or supply-chain disruption can increase lead times and unit costs—an operational risk that planners must price into contracts and inventories.
-
Platform convergence and unmanned integration: The integration of launcher functions with unmanned platforms, and early experiments with expendable payloads launched from sonobuoy infrastructure, expand the addressable market but introduce new certification and interoperability burdens.
-
Geopolitical demand drivers: Renewed emphasis on ASW in key naval forces is creating procurement momentum. Buyers are prioritizing systems that enable networked multistatic sensing, quick rearm capability, and reduced platform familiarity costs.
What the full report contains (high-level preview)
PW Consulting’s full report provides a structured, decision-ready package for executives and program teams, including:
-
End-to-end methodology and transparent market-sizing model built on program-level demand mapping;
-
Competitive benchmarking with supplier capability matrices and execution-risk scoring;
-
Procurement playbooks tailored to platform owners, prime contractors, and specialist suppliers;
-
Supply-chain stress tests and mitigation plans for material and manufacturing constraints;
-
Scenario-based forecasts, including accelerated ASW modernization and technology-disruption pathways;
-
M&A and partnership opportunity maps with valuation heuristics and integration samplers;
-
Appendices with contract timelines, platform retrofit schematics, and technology readiness assessments.
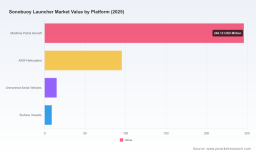
To preserve the strategic value of this market intelligence for subscribing clients and to maintain the integrity of procurement-sensitive data, the report intentionally presents aggregated market numbers and trend directionality in this release while withholding granular regional, platform and application splits, vendor-level market shares, and project-specific contract valuations. These details are available in the complete PW Consulting report and datasets.
Actionable recommendations for 2026
-
For defense customers: Lock in multi-year production and sustainment contracts with staggered delivery profiles to buffer suppliers against material-cycle shocks. Prioritize qualification of at least two sources for critical launcher components to preserve industrial resilience.
-
For prime contractors: Combine field-proven pneumatic launchers with modular interfaces that enable rapid integration of next-generation sonobuoys. Offer retrofit kits and life-extension services as bundled options to capture aftermarket revenue.
-
For specialist OEMs: Focus R&D on lightweight composite tubes and quick-change carousel designs that reduce sortie turnaround time. Position these assets for export through compliance-ready documentation and interoperability testing.
-
For investors and M&A teams: Target bolt-on acquisitions that fill capability gaps in launch integration, composite manufacturing, or software-defined launcher controls. Favor targets with established platform certifications and low requalification burdens.
-
For innovation and capability arms: Sponsor demonstrator projects that integrate expendable payload concepts and unmanned launch options into existing rotary launcher infrastructure—these are high-value experiments that clarify future procurement requirements.
How to use this intelligence in 90-day and 12-month plans
In the next 90 days: validate supplier long-lead items, begin negotiation on multi-year framework agreements, and initiate a high-level interoperability audit for any platform targeted for launcher retrofit.
Over 12 months: execute parallel qualification of secondary suppliers, finalize modular interface standards in collaboration with platform OEMs, and commit to demonstrator funding that de-risks unmanned integration pathways slated for fiscal year 2027 procurement cycles.
Closing perspective
The sonobuoy launcher market in 2026 sits at a strategic inflection point: steady market growth provides a reliable commercial base, while technology and platform shifts create asymmetric opportunities for players who can marry proven systems engineering with nimble innovation. PW Consulting’s Worldwide Sonobuoy Launcher Market report translates these dynamics into concrete options for capital deployment, partnership formation, and program execution. For program managers, strategic buyers, and corporate development teams that need the granular intelligence to act in 2026, PW Consulting’s full dataset and analyst briefings are the recommended next step.
To access the complete report, including the withheld regional and platform splits, vendor market shares, and project-level contract valuations that inform the above recommendations, please visit the PW Consulting report page or contact our client services team for a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Sonobuoy Launcher Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com