

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
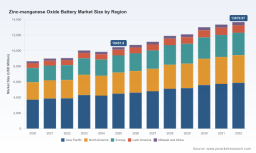
PW Consulting: Worldwide Zinc‑Manganese Oxide Battery Market to Reach USD 10,451.8 Million in 2025, Poised for 3.92% CAGR to USD 13,679.97 Million by 2032 as Asia‑Pacific Leads with USD 4,494.95M

Worldwide Zinc‑Manganese Oxide Battery Market — Strategic Outlook for 2026 Decision‑Makers
PW Consulting today releases a forward‑looking executive briefing derived from our forthcoming Worldwide Zinc‑Manganese Oxide Battery Market report (base year 2025, forecast period 2026–2032). As companies recalibrate product portfolios, supply chains and capital allocation in the wake of shifting energy and consumer electronics priorities, the Zn–MnO2 chemistry is emerging as a differentiated option across primary and secondary power niches. Our research quantifies the market’s trajectory and translates it into practical decision frameworks for 2026 planning cycles.
Worldwide Zinc-manganese Oxide Battery Market
Headline market view — growth, scale and concentration
After a period of steady expansion between 2020 and 2025, the global zinc‑manganese oxide battery market reached an estimated USD 10.45 billion in 2025. Our baseline forecast projects a compound annual growth rate (CAGR) of approximately 3.92% through 2032, supporting mid‑single‑digit annual expansion and a structured, investable path toward a larger installed base by the end of the decade. Market concentration is meaningful: the top three incumbents command just over half of market share, while the top five represent roughly two‑thirds—conditions that shape pricing dynamics, channel strategies and M&A opportunity sets.
Worldwide Zinc-manganese Oxide Battery Market
Why this matters for 2026 strategy
- Portfolio prioritization: Zn–MnO2 offers a suite of technical and regulatory advantages (non‑toxic feedstocks, tolerant transport classification, and proven safety in stationary designs) that warrant differentiated go‑to‑market treatments versus lithium chemistries.
- Cost pathway clarity: abundant zinc and manganese inputs underpin a low long‑run production cost profile; at scale, secondary Zn–MnO2 systems are projected to be competitive on a $/kWh basis versus incumbent technologies.
- Segmented adoption opportunities: manufacturers can extract premium value in high‑volume, price‑sensitive primary applications while pursuing adjacent revenue streams in rechargeable stationary storage and residential backup.
- Regulatory and safety de‑risking: certification milestones and disposal classifications materially reduce compliance friction for producers and end users, influencing procurement timelines for utilities, device OEMs and consumer channels.
What PW Consulting’s report delivers — practical, executable intelligence
This release is a strategic preview. The full report is designed as an operational toolkit for 2026 implementation. Key deliverables include:
Worldwide Zinc-manganese Oxide Battery Market
- Market model and interactive forecast engine — scenario‑ready, with baseline, upside and downside pathways allowing finance teams to stress test revenue, margin and capex implications under alternate demand and input‑cost assumptions.
- Supply‑chain heatmaps — supplier concentration, raw‑material sourcing risk, and logistics sensitivity analyses with mitigation playbooks (dual‑sourcing, hedging, near‑shoring options).
- Technology readiness and roadmaps — validated TRL scoring for primary and rechargeable Zn–MnO2 variants, critical performance metrics (cycle life, energy density, BOM drivers) and prioritized R&D investment themes.
- Commercial playbooks — channel segmentation, pricing architectures, private‑label/OEM strategies and distributor incentive models tailored to incumbent and emerging vendors.
- Regulatory and standards compendium — compliance checklists, certification timelines (including stationary storage standards), and implications for product labelling, disposal and transportation.
- Competitive benchmarking — vendor scorecards, strategic positioning maps and M&A screening templates to identify partnership or acquisition targets aligned to specific growth strategies.
Competitive landscape — incumbent strengths and disruptor pathways
The commercial ecology of Zn–MnO2 remains anchored by large, vertically integrated battery manufacturers that dominate primary cell markets. Those incumbents benefit from scale manufacturing, entrenched channel relationships and brand equity—advantages that translate to resilient pricing power in mainstream consumer applications. At the same time, smaller, more technology‑driven entrants are progressing rechargeable variants that open new end‑use categories and business models.
- Duracell Inc. — As an archetypal leader in primary alkaline Zn–MnO2 cells, Duracell’s high‑performance formulations, marketing reach and retailer relationships create durable defensive moats. Strategic options for Duracell include leveraging core brand trust to accelerate adoption of higher‑value specialty cells and licensed rechargeable products through select partnerships.
- Energizer Holdings, Inc. — Energizer’s scale across brands and form factors positions it to optimize portfolio mix between legacy primary sales and incremental rechargeable solutions. The company’s challenge is converting industrial and specialty channel demand into profitable long‑term recurring revenue.
- Panasonic Energy Co., Ltd. — Panasonic’s global manufacturing footprint and OEM relationships make it a pivotal supplier for both consumer and specialty applications. For Panasonic, the strategic lever is moving from volume to margin through premium chemistry tweaks and integrated product solutions.
- Nanfu, Zhejiang Mustang, Zhongyin — China‑based producers command cost‑position advantages and OEM scale. Their playbook focuses on high‑volume contract manufacture and rapid capacity scaling; international expansion and quality certification will determine which players become true global challengers.
- GP Batteries & VARTA — Regional leaders with strong ties to industrial and specialty customers; their route to growth lies in tailored technical support and co‑development arrangements with OEMs in adjacent sectors.
- Urban Electric Power & Zēlos Energy — These innovators are converting Zn–MnO2 chemistry into rechargeable stationary systems. Recent progress includes demonstration‑scale deployments and laboratory achievements that show attractive cycle life and safety profiles. Their commercialization roadmaps are a critical watch for utilities, integrators and investors evaluating distributed storage alternatives.
Regulatory, safety and raw‑material context
Three contextual dynamics materially affect strategic choices in 2026:
- Regulation and disposal: Primary alkaline Zn–MnO2 cells benefit from permissive disposal classifications in key jurisdictions due to low toxicity and absence of restricted heavy metals—reducing end‑of‑life compliance costs and easing retailer stocking decisions.
- Standards and safety: Rechargeable Zn–MnO2 stationary systems have achieved relevant safety certifications in test programs that indicate no thermal runaway under specified abuse conditions, lowering insurance and permitting friction for grid‑adjacent deployments.
- Raw‑material economics: Zinc and manganese supply characteristics—abundant, widely traded and cost‑competitive—create a favorable cost baseline. Public assessments indicate prospective production costs for secondary Zn–MnO2 at scale that can undercut many incumbent storage chemistries on a $/kWh manufacturing basis.
Strategic recommendations for 2026 — prioritized actions
Based on our integrated analysis, PW Consulting recommends a tiered approach that aligns near‑term proof points with medium‑term scale plays:
- Near term (0–12 months) — Run commercialization pilots targeted at use cases where Zn–MnO2’s attributes (safety, benign disposal, competitive cost) provide immediate advantages: high‑volume consumer products, residential backup power pilots, and select industrial backup applications. Use pilot data to refine BOM cost targets and channel economics.
- Medium term (12–36 months) — Invest in manufacturing flexibility: modular lines that can produce both primary and rechargeable variants, and supplier contracts that secure zinc and manganese feedstocks with price collars. For incumbents, prioritize pricing and packaging innovations to defend margin as new rechargeable offerings gain share.
- Investor and M&A playbook — Screen targets that pair technology IP in rechargeable Zn–MnO2 with established manufacturing footprints or distribution networks. Valuations should be stress‑tested against three scenarios in our model: conservative adoption, accelerated grid services uptake, and rapid commoditization.
- Utilities and integrators — Commission independent certification pilots (safety, cycle life, thermal management) using PW Consulting’s evaluation protocol to compare Zn–MnO2 packs with incumbents under local environmental conditions.
Limitations and what’s in the full report
This briefing intentionally highlights the market dynamics, competitive positions and strategic options without reproducing the full suite of segmented datasets, proprietary price curves or the granular regional and application splits contained in our primary model. The full report includes:
- Detailed regional and application demand curves and sensitivity tables (proprietary).
- Vendor‑level financial benchmarking and cost‑build analyses.
- Interactive spreadsheets and scenario dashboards for board‑level planning.
- Confidential M&A target shortlists and negotiation frameworks.
Next steps — for executives planning 2026 moves
PW Consulting offers tailored briefings and model licenses that map the report’s insights to your balance sheet and product roadmap. For teams preparing 2026 budgets, the decisive actions are clear: validate Zn–MnO2 in a controlled set of priority use cases, secure feedstock optionality, and evaluate selective partnerships with technology innovators and regional producers to capture near‑term growth while preserving optionality for future scale.
To obtain the complete report, interactive models and an invitation to our executive webinar series, visit the PW Consulting release page or contact our industry practice for a confidential briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Zinc-manganese Oxide Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com