

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Lightweight Precast Wall Panel Market to Reach USD 94,864.35 Million by 2032, Expanding at 6.5% CAGR (2026–2032)

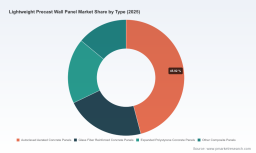
Worldwide Lightweight Precast Wall Panel Market — Strategic Outlook for 2026 Decision-Makers
Executive snapshot
PW Consulting’s latest market study on the Worldwide Lightweight Precast Wall Panel Market establishes the sector as a structurally growing segment of global construction materials. Using 2025 as the analytical base year, our model identifies a steady compound annual growth rate (CAGR) of 6.5% across the 2026–2032 forecast window. That trajectory takes the market from a market-size baseline in 2025 to appreciably larger volumes by the mid-2030s, driven by a confluence of demand for faster, lower-carbon building envelopes, regulatory pressure on embodied carbon, and continuing adoption of prefabricated systems in both developed and emerging markets.
Worldwide Lightweight Precast Wall Panel Market
Why this report matters for 2026 corporate strategy
- Timely investment calibration: A 6.5% CAGR provides a defensible growth baseline for capital allocation, plant sizing, and inventory planning while our scenario suite enables stress-testing against commodity and regulatory shocks.
- Procurement and specification leadership: Buyers and project sponsors are increasingly demanding EPDs and supplier-level sustainability credentials; this report decodes the evolving regulatory expectations and their procurement implications.
- Product portfolio choices: Innovations in autoclaved aerated concrete (ALC), composite sandwich systems, and EPS-core sandwich panels create trade-offs between weight, thermal performance, cost, and circularity—decisions that determine margin pools and market access.
- M&A and partnership signals: The market remains fragmented (low top-tier concentration), indicating attractive consolidation opportunities for platform buyers and strategic partnerships for manufacturers seeking scale or geographic access.
- Risk mitigation: Supply-chain concentration in key inputs (cement, steel, EPS) and state-level “Buy Clean” style procurement policies mean manufacturers must operationalize embodied-carbon management to remain eligible for public and certification-driven projects.
What’s inside the report — practical, decision-ready deliverables
Beyond headline forecasts, PW Consulting’s report is structured as an operator’s playbook. Deliverables include:
Worldwide Lightweight Precast Wall Panel Market
- Proprietary forecast model (2026–2032) with scenario branches for commodity-driven cost shocks, accelerated decarbonization, and accelerated modular adoption—built to be re-run with client inputs.
- Decision matrices that map panel technologies to project archetypes (residential, commercial, industrial/institutional) including build-time savings, on-site labor impact, and likely compliance hurdles.
- Supply-chain heatmaps and cost-curve analysis for core materials and insulation cores (including EPS and ALC inputs), with sensitivity testing for raw-material price swings.
- Regulatory and procurement playbook: actionable steps to comply with EPD/Buy-Clean regimes, specification language templates, and tender-ready sustainability clauses.
- Manufacturing and CAPEX blueprints: from retrofit options for legacy precast plants to full greenfield layouts emphasizing automation, reduced cycle times, and thermal-efficiency line items.
- Commercial go-to-market bundles: channel strategies, pricing playbooks, and partnership frameworks for capturing accelerated offsite construction demand.
- Vendor benchmarking and technology scouting: qualitative and quantitative supplier profiles, technology maturity mapping, and a shortlist of acquisition/partner targets tailored to different strategic intents.
Competitive landscape — what incumbent and emerging suppliers signal for 2026
The sector’s competitive topology is best described as fragmented with pockets of technical leadership. Measured concentration levels reflect a market where regional champions and product specialists coexist with global precast platforms—creating multiple routes to scale.
Worldwide Lightweight Precast Wall Panel Market
- Product innovators: Companies that have refined lightweight architectural or structural panels (for example, thin-profile architectural composites or insulated sandwich panels) command technical differentiation that reduces structural loads and installation time—capabilities that translate directly into project-level cost savings and expanded addressable markets.
- Regional specialists: Several manufacturers leverage patented molding systems, ALC processes, or localized turnkey services to secure rapid adoption in their home markets. These firms often pair speed of delivery with tailored compliance expertise for regional building codes.
- Sustainability-focused manufacturers: Vendors with third-party certifications and green-label product lines are gaining preferential access to public projects and certification-driven private developments as EPDs and plant-level sustainability scoring become procurement gatekeepers.
- Traditional precasters adapting to light-weighting: Established precast players are implementing sandwich and composite technology upgrades to capture new workloads without abandoning existing project pipelines.
Recent industry moves underscore these themes: industry-wide release of updated Environmental Product Declarations for architectural precast establishes a new transparency baseline; certification regime updates that shift more weight to supply-chain performance are accelerating supplier-level ESG disclosure; and case-level evidence of large-scale ALC and lightweight panel deployments signals buildability acceptance in demanding project types such as data centers and modular housing.
Strategic plays for 2026 — a prioritized roadmap
For executives and investment committees preparing 2026 plans, we recommend a tiered set of actions aligned to timing and risk appetite.
- Immediate (0–6 months): mandate EPDs or equivalent cradle-to-gate disclosures for all supplier pre-qualification; conduct embodied-carbon audits on high-volume product lines; establish target KPIs for build-time reduction and waste minimization.
- Near term (6–18 months): pilot modular, factory-installed insulation sandwich panels on representative projects to quantify on-site labor savings and cycle-time improvements; negotiate conditional offtake or long-term material supply agreements to hedge EPS and cement price volatility.
- Medium term (18–36 months): invest in selective vertical integration (e.g., secured EPS or insulation supplies) or acquire regional platforms to secure scale in high-growth corridors; deploy automation to reduce per-panel labor content and improve quality consistency.
- Long term (36+ months): pursue consolidation to capture scale economies and to integrate circular-materials strategies—recycled aggregates, low-carbon binders, and take-back programs that will become commercially material as embodied-carbon pricing and procurement thresholds tighten.
Key risks and sensitivity considerations
Three drivers warrant continuous monitoring and scenario-stress testing:
- Raw-material price and availability: cement, aggregates, and polymer-based cores remain the largest input exposures. Correlated price shocks materially affect margins for commodity-style panel offerings.
- Regulatory and procurement shifts: expanding EPD requirements and state-level Buy Clean policies can rapidly reallocate demand toward suppliers with validated low-carbon footprints.
- Adoption pace of offsite construction: faster-than-expected uptake of fully integrated offsite systems can compress margins for commodity panels while rewarding system integrators with complete wall-system solutions.
How PW Consulting supports your 2026 choices
Clients engaged with PW Consulting receive not only the report but also tailored support: rapid reconfiguration of the forecast model to reflect client-specific project pipelines, supplier due diligence packs, bid-tender templates with EPD clauses, and a prioritized M&A shortlist aligned to strategic intent. For industrial clients, we overlay plant-level productivity targets with a capital and operational investment plan calibrated to return-on-invested-capital thresholds.
Next steps — where to find the missing detail
This press overview intentionally highlights strategy, themes, and actionable recommendations while withholding full regional and application-level splits and certain granular vendor share tables. Those detailed segmentations, downloadable datasets, plant-level KPI templates, and supplier scorecards are available through the full report and our client portal. Access to the complete dataset is the quickest way to convert the structural growth thesis (6.5% CAGR baseline and multi-year forecasts) into executable 2026 budgets, procurement mandates, and M&A playbooks.
To discuss how these findings apply to your portfolio or to commission a bespoke scenario run for your manufacturing footprint, market entry plan, or acquisition target screening, contact PW Consulting’s Lightweight Precast Wall Panel team—we convert market insight into competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Lightweight Precast Wall Panel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com