

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Benzhydrol Market Expansion at a 4.52% CAGR Through 2032

Benzhydrol Market 2026: Strategic Signals for Decision-Makers — A PW Consulting Executive Brief
As companies prepare strategic roadmaps for 2026 and beyond, granular, decision-ready intelligence on niche intermediate chemicals is no longer optional. PW Consulting’s latest Benzhydrol Market report distills the signal from the noise to support commercial, sourcing, and investment choices across pharma, specialty chemicals, and research supply chains. This executive brief previews the report’s strategic value: it surfaces the macro trajectory, highlights structural risks and opportunity vectors, and outlines the practical instruments executives can use to convert insight into action — while reserving the full, segment-level datasets for the complete report.
Benzhydrol Market
Macro snapshot: a measured, resilient growth profile
Benzhydrol (diphenylmethanol) has shown steady expansion through the early 2020s. The market moved from the low hundreds of USD Million at the start of the decade to reach USD 241.22 Million in 2025. PW Consulting’s base-case modeling anticipates a compound annual growth rate (CAGR) of approximately 4.52% over the 2026–2032 forecast window, driving the market toward the low-to-mid three-hundred-million range by 2032. The growth is not uniform across end uses: pharmaceutical intermediates remain the primary growth anchor, while derivatives related to fragrances and certain consumer applications face structural headwinds driven by regulatory shifts.
Benzhydrol Market
Why this matters for 2026 decision-making
- Sourcing stability and cost predictability: A modest but reliable growth profile implies that suppliers and buyers should plan for sustained demand rather than speculative spikes. Procurement teams must therefore move from opportunistic spot buying to layered sourcing strategies that blend contracts, tolling arrangements, and strategic inventories.
- Regulatory risk transposes into commercial risk: Restrictions on benzophenone — the predominant precursor — in certain consumer channels are already reshaping downstream demand patterns. While benzhydrol itself is not universally regulated out of these channels, correlated regulatory trends change the growth mix and must be actively monitored in supplier selection and new product planning.
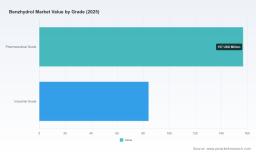
- Value capture depends on grade and certification: Market participants that can reliably deliver pharmaceutical-grade material and documented quality systems will find disproportionate pricing power versus undifferentiated industrial-grade suppliers.
Supply-side realities and operational risks
Manufacturing of benzhydrol is a classical reduction process of benzophenone, most commonly via catalytic hydrogenation or metal-reduction routes. Key inputs and process hazards — from flammable methanol and hydrogen gas to catalysts such as Raney nickel — create a non-trivial safety, permitting, and logistics profile for producers and contract manufacturers. Our field work and pre-feasibility sources confirm that typical site inventories and handling practices require robust EHS systems and contingency planning.
Benzhydrol Market
- Feedstock concentration and regulatory tracing: Benzophenone is registered and monitored in major regulatory regimes. Shifts in its permitted uses (notably in certain cosmetics and consumer applications) will have a lagged but material effect on benzhydrol demand in those end markets. Companies must instrument their demand-sensing to detect leading indicators from regulatory dossiers, not only sales trends.
- Process flexibility as a competitive lever: Producers that maintain multi-modal reduction capabilities (hydrogenation, zinc/aluminum reductions, catalytic approaches) can flex between cost and quality objectives and are better placed to respond to feedstock price volatility.
- Safety and insurance: Inventory and storage of reagents — methanol, metals, bases, and hydrogen — push up insurance and compliance costs. Buyers should incorporate supplier EHS performance into total landed cost calculations.
Competitive landscape: how to read the field
The benzhydrol ecosystem features a dual structure: a broad base of regional manufacturers that supply industrial and bulk intermediates, and select international brands that address research, reference, and high-purity requirements. India houses a dense cluster of manufacturers and exporters; global specialty-chem suppliers and life-science distributors provide branded, high-assurance products and standards for laboratories and pharmacopoeial use.
- Regional bulk suppliers: A number of established Indian producers and exporters occupy the bulk/intermediate lane, serving industrial and pharmaceutical synthesis markets. Their competitive advantages are scale, cost access to regional feedstocks, and proximity to contract-manufacturing partners. Strategic buyers should treat these firms as primary candidates for long-term agreements, tolling, and joint quality-upgrade programs.
- High-purity and standards providers: International suppliers, including major life-science brands, play the role of quality and regulatory assurance for R&D and regulated manufacturing. For companies requiring USP/EP-grade materials or traceable standards, these suppliers remain non-substitutable despite higher unit costs.
- Consolidation opportunities: The market profile favors value-accretive consolidation: mid-size manufacturers can enhance margins through procedural standardization, pharma-grade certification, and targeted capacity expansions. Investors should evaluate bolt-on opportunities that add product-grade capability or regulatory dossiers rather than incremental tonnage alone.
Representative firms profiled in our report include a cross-section of domestic Indian producers and global specialty suppliers. Each profile includes operational footprints, product-grade capabilities, quality certifications, and an assessment of strategic fit for different buyer archetypes. For procurement leaders, the supplier scorecards provide a practical shortlist to initiate audits and sourcing pilots.
Strategic playbook: five tactical moves for 2026
- Implement multi-tier sourcing with capability audits: Blend a limited number of high-assurance suppliers for regulated segments with cost-efficient regional partners for non-critical volumes. Use on-site capability audits and IP-protected sampling programs to de-risk scale-up.
- Negotiate capacity-backstop contracts: For intermediates destined to pharmaceutical supply chains, secure capacity commitments or priority allocation clauses to hedge against upstream feedstock disruptions.
- Invest in quality-upgrade roadmaps: Producers should create investment plans to certify existing lines to pharma-grade standards — the incremental margin uplift often justifies modest capex and procedural investments.
- Monitor regulatory pipelines continuously: Because benzophenone regulatory action can alter application mixes, corporates need a simple regulatory early-warning dashboard that converts legal changes into demand-scenario adjustments.
- Explore downstream integration and value-add: Converting benzhydrol into higher-value derivatives or preformulated intermediates can materially improve margins and customer stickiness — consider co-development with downstream users.
Report deliverables: what we provide (practical, executable intelligence)
PW Consulting’s full Benzhydrol Market report is oriented toward implementation. Key deliverables include:
- Market sizing and modeled demand scenarios (base, downside, upside) with transparent assumptions and sensitivity tables to test price and feedstock shocks.
- Supplier scorecards and due-diligence templates tailored to different buyer archetypes (pharma vs. industrial vs. R&D suppliers).
- Cost-build models for primary production routes, including capex and opex benchmarks, with breakpoint analysis for different scales and regions.
- Regulatory monitoring matrix linking benzophenone and related precursor developments to downstream demand channels and substitution risk.
- Commercial playbooks for sourcing, inventory policy, and shortlist criteria to operationalize a two-tier procurement strategy.
- Scenario-based M&A and investment playbook, highlighting value drivers for consolidation, certification-driven premium capture, and tolling partnerships.
Methodology and data integrity
The base year for the study is 2025, with historical coverage from 2020–2025 and a forecast horizon through 2032. Our market-size model integrates primary interviews, company disclosures, import-export flows, regulatory registries, and techno-economic production models. Wherever possible we triangulate commercial claims with independent permit records and trade flow data. Data tables, assumptions, and calculation scripts are included in the subscriber package to enable your internal stress-testing and auditability.
What this brief intentionally withholds — and why
Consistent with the “trailer” principle, this brief highlights macro trajectory and actionable strategy while withholding the granular segment-level tables and supplier-level quantitative rankings that are the heart of our commercial toolkit. The full segmentation by region, grade, and application — together with downloadable datasets, year-by-year models, and supplier scorecards — are available in the complete report. This approach lets you verify high-level hypotheses here, then access the full evidence base when you are ready to transact or invest.
Immediate next steps for 2026 planning
- Procurement leaders: begin supplier capability audits and issue RFPs with clauses on long-term capacity assurance and EHS verification.
- Operations and plant teams: review capex for quality upgrades that enable pharma-grade supply and run PoCs for alternate reduction processes to improve margins.
- Corporate strategy and M&A: prioritize targets that add regulatory dossiers, quality certificates, or downstream conversion capability rather than mere tonnage.
- Investors and financiers: request the full report to access cash-flow scenarios and sensitivity analysis that underpin valuation theses.
PW Consulting’s Benzhydrol Market report is designed to convert data into decisions. For the full dataset, supplier scorecards, and executable playbooks, visit our report page and download the subscriber package. The complete study gives you the segment-level intelligence and vendor-level metrics needed to operationalize a 2026 strategy that is both resilient and value-accretive.
For detailed analysis of this topic, please visit the official page: Benzhydrol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com