

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Pre‑painted Galvanised Iron Market to Rise from USD 16.42B in 2025 to USD 25.71B by 2032 at a 6.62% CAGR — Asia Pacific Leads with USD 9.81B

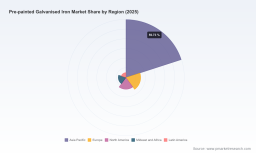
Worldwide Pre-painted Galvanised Iron (PPGI) Market: Strategic Imperatives for 2026 — PW Consulting Insight Brief
Executive summary
PW Consulting’s latest Worldwide Pre-painted Galvanised Iron Market report (base year 2025; historical coverage 2020–2025; forecast 2026–2032) delivers an actionable roadmap for executives who must make definitive supply, pricing, and growth decisions in 2026. Our high‑confidence model shows the global PPGI market expanding from a 2025 total of approximately USD 16.4 billion to roughly USD 25.7 billion by 2032, implying a compound annual growth rate (CAGR) of 6.62% across the forecast horizon. These headline numbers mask important structural shifts — rising feedstock costs, tightened trade regimes, and accelerating premiumization of coatings — that will determine winners and losers next year and beyond.
Worldwide Pre-painted Galvanised Iron Market
Why this report matters for 2026 decisions
-
Immediate tactical impact: Pricing and contract strategy. With volatile zinc, HRC and iron ore costs, producers and buyers need defensible, near‑term pricing rules and hedging frameworks to safeguard margins without ceding market share.
Worldwide Pre-painted Galvanised Iron Market -
Operational priorities: Supply continuity and capacity planning. Raw material constraints and fresh capacity additions create a two‑speed supply picture; decisions on restart, ramp, or brownfield investment must be based on geographies and product grades where demand resilience is highest.
Worldwide Pre-painted Galvanised Iron Market -
Strategic positioning: Product premiumization and sustainability. Premium coatings and branded solutions are becoming value levers in mature markets, while regulatory and buyer pressure on carbon and recyclability will shape product roadmaps.
-
M&A and partnership timing. Our market concentration analysis (CR3 ~34.2%; CR5 ~48.6%) indicates a fragmented but consolidating landscape — ideal conditions for targeted acquisitions, joint ventures, or bolt‑on capacity plays to capture scale advantages.
Snapshot: what the report contains (practical, decision‑ready modules)
-
Robust market sizing & forecasting: Bottom‑up market model reconciling supply, end‑use demand and trade flows across 2020–2032, with scenario variants to stress‑test 2026 revenue and volume outcomes.
-
Raw material sensitivity and pricing outlook: Quantified impact matrices linking zinc, hot‑rolled coil (HRC), and iron ore price moves to PPGI margin swing ranges — essential for procurement and commercial teams.
-
Supply chain mapping and capacity pipeline: Detailed mapping of finishing lines, galvanizing capabilities and planned commissions, plus a risk heatmap for logistics, energy and regulatory exposure.
-
Competitive playbooks and company benchmarking: Strategy briefs for leading integrated steelmakers, specialty coaters and regional champions, including SWOTs, recent strategic moves and go‑to‑market recommendations.
-
Pricing, contract and working capital playbook: Contract clause language, indexation options, and stock/flow optimization templates for CFOs and commercial teams facing rapid cost inflation.
-
Opportunity heatmaps and go‑to‑market templates for 2026: Focused recommendations for product premiumization, channel expansion (trade, builders’ merchants, OEMs), and quick‑win service add‑ons.
Market dynamics shaping 2026
Three macro forces will dominate strategic choices in 2026: raw material inflation, trade and tariff volatility, and premium/coated product demand evolution.
-
Raw material inflation: Zinc concentrate prices saw a sharp uptick in early 2026, and hot‑rolled coil spot prices rose materially from late 2025 into Q2 2026. These movements have translated into meaningful upward pressure on PPGI pricing and forced manufacturers to revisit input sourcing strategies and pass‑through mechanisms with customers.
-
Trade and regulatory shifts: The reinstatement and expansion of U.S. Section 232 measures has created new cost and access dynamics for coated imports. Derivative tariffs applied in some cases have increased effective landed costs and are accelerating localization and nearshoring discussions among buyers.
-
Product and demand structure: End‑use markets such as construction, appliances and automotive are evolving differently — with construction driving volume dynamics while appliances and specialty industrials underpin margin performance via higher‑value coatings and tighter quality specifications.
Competitive landscape: who matters and why
The PPGI competitive set combines global integrated steel majors, regional champions and specialized coaters. PW Consulting’s report benchmarks leaders across capacity, coating technologies, geographic footprints and customer channel control. Key themes include:
-
Integrated steelmakers (e.g., ArcelorMittal, Tata Steel, POSCO, China Baowu) are using scale, captive feedstock and distribution networks to defend share and selectively pursue value‑added coated products. Recent strategic moves include targeted acquisitions and capacity strengthening in key finishing hubs to improve service and shorten lead times.
-
Regional branded players (e.g., BlueScope with its branded COLORBOND solution) leverage localized product differentiation and channel control, which is increasingly valuable where tariffs and logistics elevate the cost of imported coils.
-
Specialist coaters and focused manufacturers (e.g., SeAH Coated Metal, Lienchy Metal, Hengze Steel) are capturing niche OEM and appliances demand by offering tailored surface treatments, tight tolerances and export‑oriented supply models.
-
North American dynamics: Domestic producers such as Nucor and recent pricing actions by major suppliers indicate an environment where minimum base pricing and inventory strategies are being used to manage cyclicality and pass through input cost inflation.
We profile more than a dozen relevant companies in the full report, including strategic implications for customers, suppliers and potential investors.
Recent headline developments and near‑term implications
-
Price actions: Leading producers in late‑2025 and early‑2026 announced base price increases and adjusted commercial terms for pre‑painted and galvanized products — a clear sign that supply‑side actors are attempting to reposition margins in the face of elevated feedstock costs.
-
Capacity and M&A: Strategic capacity additions and ownership consolidations have accelerated in 2024–2026, with major players strengthening regional finishing capabilities — an important counterweight to import shocks induced by tariff changes.
-
Input cost shocks: Zinc, HRC and iron ore price moves in early 2026 materially shifted the cost base for PPGI. Organizations with active hedging, diversified sourcing and vertical integration are demonstrably better positioned to preserve margins.
Actionable recommendations for executives in 2026
Based on our analysis, PW Consulting recommends a set of prioritized actions for 2026 planning horizons:
-
Reassess pricing architecture now — move from ad‑hoc increases to transparent indexation tied to validated material baskets and published benchmarks. Update contract templates to include clear pass‑through and force majeure clauses tailored for raw material shocks and trade actions.
-
Stress‑test supply chains across three scenarios (baseline, disruption, accelerated protectionism) and implement contingency playbooks: dual‑sourcing, consignment stock agreements, and strategic buffer inventories in tariff‑sensitive markets.
-
Prioritize premium coating investments and product segmentation: differentiate commodity coils from value‑added, higher‑margin coated products for appliances, façade and specialty infrastructure where specification stickiness is higher.
-
Revise capital and M&A roadmaps: target bolt‑on finishing capacity in high‑value corridors and evaluate acquisitions that close logistics gaps or add proprietary surface technologies.
-
Embed scenario‑based financial planning: model P&L and working capital under varying zinc and HRC price trajectories and tariff permutations to quantify breakpoints for pricing resets, margin deterioration and required CAPEX.
KPIs and monitoring framework for 2026
-
Input cost to finished product delta (monthly)
-
Order fill rate by market (weekly)
-
Average realized price vs. published benchmarks (monthly)
-
Time‑to‑market for premium coated SKUs (weeks)
-
Working capital days and inventory composition by origin (monthly)
Next steps: how to use PW Consulting’s report
This briefing is a strategic teaser: it outlines the headline market trajectory, structural dynamics and high‑impact recommendations that should shape 2026 decision cycles. For teams preparing procurement negotiations, capital allocation rounds, or M&A diligence in 2026, the full PW Consulting report contains the empirical detail you need — comprehensive segment tables, regional and application splits, company financial benchmarks, line‑by‑line capacity maps, and downloadable models to run your own sensitivity tests.
If your board or executive team needs a focused briefing, PW Consulting can deliver a tailored 90‑minute onsite or virtual workshop that applies these findings to your specific SKU portfolio, procurement contracts and regional market exposure.
Concluding perspective
The PPGI market is at an inflection point. Headline growth remains strong — expanding from roughly USD 11.8 billion in 2020 to an estimated USD 16.4 billion in 2025 and projected to reach about USD 25.7 billion by 2032 at a 6.62% CAGR — but the path between headline growth and realized profitability is being reshaped by input inflation, trade policy shifts, and differentiated product demand. Executives who act quickly to align pricing frameworks, fortify supply continuity, and selectively invest in premium coatings or strategic capacity will convert macro growth into durable shareholder value in 2026.
Access to the full dataset, granular segment tables, and company-level briefs is available via the PW Consulting report landing page — the only place to get the underlying tables, scenario models and implementable toolkits referenced in this briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Pre-painted Galvanised Iron Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com