

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Consumer-Grade Ethernet PHY Chip Market Poised to Grow at a 6.85% CAGR During 2026–2032

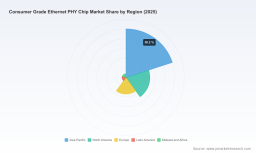
Worldwide Consumer-Grade Ethernet PHY Chip Market — Strategic Imperatives for 2026
Executive teaser
PW Consulting’s latest market study on the Worldwide Consumer-Grade Ethernet PHY Chip Market provides a decision-grade intelligence package tailored for boards, product leaders, and corporate development teams preparing for the 2026 planning cycle. The report synthesizes seven years of historical performance (2020–2025) with a robust forecast horizon (2026–2032), delivering actionable scenario models, supplier risk maps, and go-to-market playbooks that translate industry trends into executable choices. This release is a strategic preview — we surface the most consequential insights to inform near-term moves while reserving detailed segment-level tables and proprietary forecasts for subscribers.
Worldwide Consumer Grade Ethernet PHY Chip Market
Market snapshot: scale, pace, and trajectory
After steady growth through the early 2020s, the consumer-grade Ethernet PHY market reached an estimated USD 1,250.0 million by the 2025 base year. PW Consulting projects continued expansion into the next decade, with revenues expected to climb to approximately USD 1,344.5 million in 2026 and to near USD 1,987.8 million by 2032. That trajectory represents a compounded annual growth rate (CAGR) of 6.85% across the forecast interval. These macro dynamics reflect a combination of ongoing upgrades in home and consumer networking, the emergence of multi-gig requirements in high-bandwidth consumer devices, and the steady incorporation of PHY functions into broader connectivity platforms.
Worldwide Consumer Grade Ethernet PHY Chip Market
Why these numbers matter for 2026 decision-making
- Portfolio prioritization: The market’s healthy mid-single-digit CAGR validates continued investment in Gigabit and multi-gig PHY roadmaps while reminding teams to balance performance with unit cost and power targets.
- Capital allocation: Public and private buyers must weigh R&D and capacity investments against a market that is growing but remains sensitive to supply-chain cost shocks and cyclical semiconductor trends.
- M&A and partnership timing: With market concentration metrics indicating a handful of suppliers capturing the lion’s share of revenues, 2026 presents a window for bolt-on acquisitions, technology licensing, or distribution partnerships that can accelerate scale.
- Trade-offs for OEMs: Device manufacturers should incorporate PHY total cost of ownership and long-term roadmap alignment into supplier selection to avoid late-stage redesigns.
What PW Consulting’s report delivers — pragmatic, operational intelligence
This study is designed as a toolkit for executives, combining quantitative models with executable guidance:
Worldwide Consumer Grade Ethernet PHY Chip Market
- Market-sizing and forecasting models (base-year 2025) with sensitivity scenarios tied to raw material and fab-disruption cases.
- Competitive heatmaps and vendor scorecards that assess product breadth, process node maturity, power/performance trade-offs, and go-to-market reach.
- Demand-driver analysis by device class and usage pattern, supported by primary interviews and channel sell-through data.
- Supply-chain vulnerability assessment, including component sourcing concentration, contract manufacturer exposure, and logistics stress tests.
- Pricing and margin frameworks that help commercial teams model the impact of commodity inflation and OEM pricing pressure.
- Product roadmap playbooks that prioritize features (low-power modes, MACsec, IEEE 802.3 compliancy, single-pair Ethernet variants) based on commercial ROI thresholds.
- M&A screening matrices and valuation benchmarks built around strategic fit, IP strength, and time-to-revenue acceleration.
Competitive landscape — concentration and strategic implications
The consumer PHY market remains meaningfully concentrated: the top three suppliers control a substantial portion of revenue, and the top five capture an even larger share. PW Consulting’s concentration metrics indicate a market structure where incumbents hold decisive advantages in design wins, distribution, and cross-selling into adjacent product families. For 2026 strategy, this matters in three ways:
- Barrier to entry: New entrants face a tightened window unless they bring differentiated technology (e.g., ultra-low-power single-pair PHYs, integrated MAC-PHY solutions) or disruptive cost models.
- Negotiation leverage: Large suppliers can extract favorable contractual terms; smaller suppliers must offset price pressure with feature specialization or local logistics advantages.
- Consolidation runway: Expect continued deal activity that reshapes supplier capabilities and redefines competitive boundaries — both horizontal consolidation (PHY + switch/bridge portfolios) and vertical plays (fab or packaging assets).
Vendor dynamics: capabilities and near-term moves
Leading and strategically relevant suppliers covered in the study include established silicon houses and niche specialists. Profiles examine technology positioning (Gigabit, multi-gig, single-pair variants), product maturity, and route-to-market. Recent industry developments highlighted in our analysis demonstrate the speed of competitive reconfiguration — from new product introductions (optical PHY transceivers and extended-reach single-pair PHY families) to strategic transactions that reassign critical assets. These moves alter supplier roadmaps and should prompt buyers and investors to reassess assumptions about partner stability and technology ownership.
Supply chain and cost headwinds — a 2026 operating reality
Operational costs are a key lever shaping margins and pricing power in 2026. The study integrates up-to-date inputs on raw-material and manufacturing pressures: elevated copper and aluminum price points have increased BOM sensitivity for packaged PHYs and connectors, while volatility in critical process gases (notably helium) has amplified wafer fabrication risk. Further, several assembly-and-test vendors implemented price adjustments in early 2026, creating near-term margin compression for contract-manufactured product lines. PW Consulting’s scenario models quantify the impact of these shocks on gross margins and provide hedging and sourcing playbooks to mitigate downside.
Regulation, standards, and interoperability
Ethernet PHY design is governed by a mature and prescriptive standards set. Compliance with IEEE 802.3 family variants — from legacy 10/100 to Gigabit, 2.5G/5GBASE-T, and single-pair Ethernet specifications — remains table stakes. Interoperability, conformance testing, and timing (PTP/1588) capabilities are frequent deal-breakers in consumer and smart-infrastructure designs. The report offers a standards risk checklist and compliance cost estimator that procurement and engineering functions can use when evaluating design paths.
Strategic recommendations for executives planning 2026 actions
- Prioritize resilient supply chains: build dual-sourcing for key PHY types and secure longer-term allocations with foundries and test houses where lead times are critical.
- Target differentiated feature sets: invest selectively in multi-gig and low-power single-pair PHYs for targeted device classes where willingness to pay is demonstrably higher.
- Hedge material exposure: use commodity hedges or index-linked contracts for copper and critical packaging materials; lock favorable TAT with assembly partners to avoid spot-price shocks.
- Lean into partnerships: where internal scale is constrained, pursue licensing or design-win partnerships with incumbents to accelerate time-to-market without heavy capex.
- Scenario-proof roadmaps: maintain product families with modular PHY integration options to support quick swaps across carrier standards and to accommodate regulatory shifts.
- M&A and IP scouting: focus on targets that add unique PHY IP, test automation, or packaging advantages rather than pure revenue plays; use our M&A matrix to prioritize targets by time-to-synergy.
How to use the full PW Consulting report
This press release is a strategic preview. The full report includes the detailed segmented breakdowns, regional and application-specific forecast tables, vendor market-share matrices, and downloadable financial models that are intentionally withheld here to preserve research value for subscribers. Purchasing the complete study grants access to our interactive forecast model, vendor scorecards, primary interview transcripts, and customizable scenario dashboards that allow teams to model bespoke supply- and demand-side shocks.
Final note — acting with conviction in 2026
The consumer-grade Ethernet PHY market presents a mix of steady growth and concentrated competition. For 2026, executives must act on two simultaneous imperatives: invest where technical differentiation yields clear commercial advantage, and shore up operational resilience against material and fabrication volatility. PW Consulting’s report equips decision-makers with the empirical models and practical playbooks needed to convert market signals into defensible strategies. For access to the complete data set, segment-level forecasts, and our proprietary valuation matrices, please visit the PW Consulting report page.
About PW Consulting
PW Consulting is a strategy advisory and industry research firm serving technology leaders and investors. Our semiconductor and networking practice combines primary research, supply-chain analytics, and financial modeling to deliver market intelligence that drives confident decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Consumer Grade Ethernet PHY Chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com