

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Chemochromic Materials Market to Reach USD 280.39 Million by 2032 on an 8.5% CAGR — Asia‑Pacific Leads at USD 54.07M

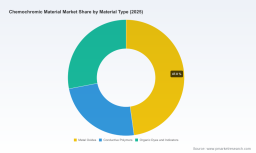
Worldwide Chemochromic Material Market — Strategic Preview for 2026 Corporate Decision-Making
PW Consulting’s latest market intelligence brief — the Worldwide Chemochromic Material Market — offers C-suite and product leaders an operationally focused preview to shape investments, partnerships, and product roadmaps in 2026. Built on a detailed historical analysis (2020–2025) and a scenario-driven forecast (2026–2032), the study synthesizes technical, commercial, and regulatory vectors that will determine winners and laggards in this specialized materials arena.
Worldwide Chemochromic Material Market
Executive snapshot
Chemochromic materials — color- or optical-state-changing compounds that respond to chemicals, gases, moisture, or solvatochromic stimuli — are moving from niche demonstrations toward commercial adoption across hydrogen safety, food quality sensing, medical diagnostics, and security applications. Our market model shows expansion from roughly USD 106.8 million in 2020 to USD 158.4 million in 2025, and projects continued acceleration through the forecast window, reaching approximately USD 280.4 million by 2032 under a central-case trajectory. The forecast period (2026–2032) is modeled with a compound annual growth rate (CAGR) of 8.5% — a meaningful signal that technical maturation and application pull are aligning to create scalable market opportunities.
Worldwide Chemochromic Material Market
Why this report matters for 2026 strategy
-
Precision capital allocation: Distinguish between near-term revenue pathways (e.g., hydrogen detection tapes, food-spoilage indicators) and longer-term platform plays (integrated sensor arrays, chromic inks for secure packaging) to prioritize R&D and pilot investments.
Worldwide Chemochromic Material Market -
Supplier and raw-material risk mitigation: Quantified scenarios around noble-metal indicator exposure and synthesis alternatives allow procurement and treasury teams to evaluate hedging, sourcing diversification, and vertical integration options.
-
Commercial partnerships and licensing playbooks: Practical frameworks for structuring OEM partnerships, white-label arrangements, and co-development agreements that shorten time-to-market while preserving IP upside.
-
Regulatory and standards readiness: Actionable checklist aligned to evolving hydrogen-refueling station standards and other sector-specific norms to reduce time-to-certification and channel friction.
Selected findings — the strategic contours (what we reveal here)
-
Market momentum: Rising adoption across multiple end uses is translating into double-digit adoption rates in select pockets; the overall sector is forecast to nearly double over the coming half-decade under our baseline assumptions.
-
Moderate market concentration: The market exhibits a compact supplier structure with top participants controlling a meaningful share of revenue — our concentration metrics indicate that incumbents have the capability to influence price, specification, and supply dynamics, while emergent players remain able to capture niche, high-value segments.
-
Technology bifurcation: A split is emerging between commodity chemochromic formulations optimized for cost-sensitive applications and advanced chemistries (including conductive polymers and hybrid composites) targeting performance-critical uses such as ppm-level hydrogen detection and medical diagnostics.
-
Cost and input volatility: Reliance on precious-metal indicators for certain hydrogen-sensitive formulations continues to expose manufacturers to raw-material price swings; our sensitivity runs model +/-15–20% annual volatility scenarios and their impact on tape and sensor economics.
What is inside the full report (practical, non-generic deliverables)
-
Integrated market model (2020–2032): Dynamic revenue paths, scenario toggles for regulatory shifts, and sensitivity tables for raw material price paths.
-
Commercial due-diligence toolkit: Scorecards and negotiation templates for evaluating contract manufacturers, licensing partners, and acquisition targets.
-
Technology readiness and scale-up guide: Stepwise lab-to-pilot-to-production checklists, CAPEX and OPEX benchmarking ranges, and quality certification pathways.
-
Regulatory tracker and compliance playbook: Consolidated mapping of applicable standards and test protocols, with action items for hydrogen refueling infrastructure and food-contact applications.
-
Go-to-market playbooks: Channel and pricing strategies for B2B, industrial-OEM, and consumer-facing product launches, plus example ROI models for three representative use cases.
-
Risk matrix and mitigation templates: Supplier concentration heat maps, alternative-material substitution pathways, and procurement hedging strategies.
Competitive landscape — who to watch and why
The industry combines specialist material innovators, legacy chemical and advanced-material firms, and emerging tape- and ink-focused manufacturers. A few emblematic players provide a useful view on competitive dynamics and partnership opportunities:
-
OliKrom (Pessac, France — https://www.olikrom.com): A developer and industrial producer of custom chemochromic pigments, inks, and paints with ISO 9001-certified production at kilogram-to-ton scales. Their portfolio spans gas-sensitive pigments alongside solvatochromic and hydrochromic variants, positioning them as a candidate for co-development and localized manufacturing partnerships. Their public presence at global industry events underscores a go-to-market emphasis on B2B industrial applications.
-
HySense Technology LLC (United States): Commercializes chemochromic pigment-based hydrogen leak detection materials born from space-agency technology transfer. Their product focus on hydrogen safety — and established customers in aerospace and industrial hydrogen — demonstrates the pathway from high-trust sectors to broader industrial adoption.
-
Merck KGaA (Darmstadt, Germany): A diversified advanced-materials incumbent with offerings relevant to chromic applications. Their scale and breadth make them a potential consolidator or large-scale supplier capable of integrating chemochromic functionalities into broader material systems.
-
Chromatic Technologies Inc. (CTI) (United States): A long-standing developer of color-changing materials whose chromic expertise is applicable to chemochromic indicators and inks. CTI illustrates the value of established application know-how when partnering for market access.
-
DaeHyun Corp / DaeHyun ST (South Korea): A specialist in hydrogen detection tapes and colorimetric sensor tapes for rapid visual leak detection. Their product-level focus indicates that application-specific businesses can capture disproportionate value when reliability and certification are required.
Recent developments we track — indicative, not exhaustive — include improved hydrogen-detection sensitivity in tape products and increased trade-show activity by specialist pigment suppliers. These moves reflect an industry preparing to serve scaling hydrogen infrastructure and higher-volume commercial channels.
Regulatory and supply-chain dynamics demanding executive attention
-
Standards alignment: Advances in chemochromic detection for hydrogen are increasingly engineered to align with the ISO framework for hydrogen refueling stations — companies targeting that vertical must plan early for required testing and standards conformity in their product roadmaps.
-
Raw-material exposure: Certain high-performance chemochromic formulations rely on noble-metal indicators that are subject to price volatility; our modeling demonstrates how +/-15–20% swings in raw-material prices can materially change unit economics for hydrogen-sensing tapes and similar products.
-
Synthesis and sustainability constraints: Leading producers actively review synthesis protocols to adapt to evolving environmental and economic constraints; this creates windows for process innovation and for firms that can deliver lower-cost, lower-footprint chemistries at scale.
Five tactical recommendations for 2026
-
Diversify material pathways: Fund parallel development tracks for noble-metal-free chemistries where feasible, to reduce sensitivity to metal-price shocks and to meet sustainability criteria.
-
Secure supply early: Negotiate multi-year offtake or conditional purchase agreements with specialty pigment producers when scaling pilot lines to production, and evaluate strategic equity or JV options for critical synthesis capabilities.
-
Prioritize standards-led productization: Make ISO and sector-specific adherence a gating criterion for commercialization in hydrogen and food segments to avoid costly rework during certification.
-
Design for manufacturability: Invest in process development and QC systems early; the gap between lab-scale performance and production-grade reliability is a common reason for delayed launches.
-
Plan channel and co-development plays: Target partnerships with materials suppliers that also offer application engineering expertise—this reduces integration risk and accelerates adoption among conservative industrial buyers.
How to use this preview
This public preview is intended to orient executives to the strategic levers and operational contingencies that will matter in 2026. It deliberately omits granular sub-segmentation tables and proprietary regional shares that are core to customer decision processes. Those detailed datasets, downloadable models, and vendor scorecards are available in the full report package, which includes the underlying assumptions and the scenario-model spreadsheets you need to stress-test capital and go-to-market plans.
Next steps
For companies evaluating entry, expansion, or partnership in the chemochromic materials space, PW Consulting provides tailored advisory engagements that extend the report’s outputs into a practical roadmap: supplier due diligence, productized prototype-to-production programs, and negotiation support for strategic sourcing contracts. Contact our industry team to request the complete Worldwide Chemochromic Material Market report and to schedule a briefing tailored to your organization’s priority use cases.
— PW Consulting, Global Chemicals & Advanced Materials Practice
For detailed analysis of this topic, please visit the official page: Worldwide Chemochromic Material Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com