

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide High-Purity Silicon Nitride Powder Market Poised for a 10.15% CAGR Through 2032

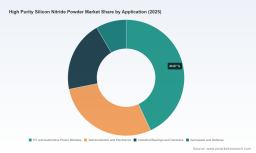
Worldwide High Purity Silicon Nitride Powder Market: Strategic Imperatives for 2026 Decision-Makers
PW Consulting’s new market study on Worldwide High Purity Silicon Nitride Powder (base year 2025; forecast 2026–2032) translates rigorous primary research into pragmatic strategic guidance. With the market reaching approximately USD 161.2 million in 2025 and a projected compound annual growth rate (CAGR) of 10.15% through the 2026–2032 forecast window, the sector is entering a phase where technical differentiation, supply-chain resilience, and regulatory navigation will determine winners and losers. This article synthesizes the report’s high-level findings, explains why this intelligence matters for executives planning in 2026, and outlines the specific operational levers companies should prioritize—while preserving the granular tables and proprietary segmentation that underpin our conclusions for subscribers to the full report.
Worldwide High Purity Silicon Nitride Powder Market
Why 2026 Is a Strategic Inflection Point
The high-purity silicon nitride powder market is no longer a niche input market. Robust demand from advanced automotive power modules, semiconductor-related applications, high-performance industrial ceramics, and aerospace components is lifting the addressable market. Our modeling shows the total market almost doubling across the forecast horizon, driven by structural adoption in electrification, tighter tolerance electronics, and higher-performance refractory and wear-resistant components.
Worldwide High Purity Silicon Nitride Powder Market
For 2026 specifically, three converging forces make timely, well-informed decisions essential:
Worldwide High Purity Silicon Nitride Powder Market
- Accelerating end-market demand that compounds the effect of capacity constraints.
- Raw-material and energy cost dynamics that are moderating input prices but raising expectations around environmental compliance.
- High market concentration: leading suppliers collectively control a substantial majority of output, intensifying M&A and capacity-planning implications for challengers and customers alike.
What the Report Delivers — Practical, Executable Outputs
Beyond headline market sizing and growth rates, PW Consulting’s study is designed as an execution toolkit for commercial, manufacturing, and corporate strategy teams. Key deliverables include:
- Forward-looking demand matrices aligned to end-market adoption curves and technology substitution scenarios—useful when setting 12–36 month commercial targets and inventory policies.
- Supply-side capability mapping that links production routes (including imide-decomposition and direct nitridation processes), feedstock dependency, and unit-cost drivers—critical for capital allocation and make-versus-buy decisions.
- Risk heat maps quantifying exposure to raw-material volatility, freight, and regulatory constraints by production geography.
- Actionable M&A and joint-venture playbooks that translate concentration metrics and proprietary supplier profiles into near-term deal criteria and integration checklists.
- Commercial negotiation levers for buyers—pricing elasticity, quality segmentation, and long-term offtake structuring—backed by benchmarking data and scenario P&Ls.
Note: The report contains detailed segmentation tables, region-by-region and application-specific demand curves, and unit-cost model spreadsheets. Those granular datasets are intentionally gated to preserve competitive value; readers requiring transaction-ready analysis should consult the full report.
Competitive Landscape: Who Shapes the Market and Why It Matters
The market exhibits significant concentration, with a handful of established players controlling the lion’s share of production and technical leadership. This concentrated structure creates predictable behaviors—capacity expansions by a leading producer can materially shift pricing and supply dynamics across the chain.
- UBE Corporation (Japan) — Globally recognized for its proprietary imide-decomposition route and consistent low-impurity powders, UBE stands as a de facto technical benchmark. Its January 2026 announcement to expand capacity at Ube City (targeting an incremental ~500 metric tons per year, expected online in Q3 2027) is a clear example of how a single investment decision can reshape near-term availability and force downstream buyers to reassess sourcing strategies.
- Denka Company Limited (Japan) — Strong in thermal and mechanical grades that serve both advanced ceramics and construction-related advanced materials; their technology and quality reputation make them a preferred partner where performance certainties are non-negotiable.
- AlzChem Group AG (Germany) — European technology leader using calcium cyanamide-derived routes, offering chemical-purity advantages for specialized high-performance applications where impurity control is critical.
- Saint-Gobain (France) — A materials conglomerate with production and finishing capabilities oriented toward demanding sintered and hot-pressed applications.
- SINTX Technologies, SAM, AEE, and Chinese producers — These suppliers round out the market with differentiated capabilities spanning biomedical grades, industrial volumes, and regional supply saturation.
Our competitive profiles section dissects each firm’s technological positioning, capacity roadmap, quality certifications, and strategic intent—enabling buyers to prioritize supplier qualifications and investors to rank acquisition targets based on defensibility and margin expansion potential.
Supply-Chain and Raw-Material Dynamics Executives Must Track Now
Two raw-material trends require immediate attention. First, high-purity silicon nitride production predominantly depends on very high-purity silicon metal feedstock, and production economics are sensitive to feedstock quality and availability. Second, the market saw moderate downward pressure on silicon metal prices in late 2025 as raw-material and energy costs eased and freight rates from Europe moderated—this offers a tactical window to renegotiate supply terms, but it may also compress supplier margins.
Concurrently, environmental regulation and energy-efficiency standards—particularly across Asia-Pacific—are tightening. Producers with legacy, energy-intensive plants face either significant capex to decarbonize or the risk of operational curtailments. Our report provides a compliance-cost overlay that lets buyers and producers estimate the operational impact of regional regulatory scenarios.
Regulatory and Policy Signals: Opportunities and Risks
National policy is already shaping demand patterns. Notably, China’s 2025 catalogue promoting certain high-performance building materials explicitly recognizes high-purity silicon nitride powders for advanced refractories and ceramics. This institutional endorsement accelerates adoption in targeted construction and industrial programs and creates an addressable market lift for compliant producers and downstream integrators.
For multinational participants, understanding the interplay between local government support, export controls, and environmental permitting is now a board-level concern. Our report includes a decision framework for assessing where to expand, partner, or limit exposure based on regulatory tailwinds versus compliance headwinds.
How to Use This Intelligence in 2026 — Tactical Recommendations
- Prioritize near-term supplier qualification: Use the next 6–12 months to lock in dual-source agreements with technology-differentiated producers, while negotiating conditional capacity commitments tied to transparent quality metrics.
- Revisit product roadmaps: For OEMs in automotive and electronics, accelerate qualification programs for grades that enable higher-temperature, higher-power-density modules—winning the next design cycle will require both material performance and supply assurance.
- Stress-test capital plans: Capital projects should be evaluated against our market scenarios—optimal timing can mean the difference between underutilized assets and premium-priced incremental output during supply tightness.
- Monitor regulatory exposure: For manufacturers with plants in high-regulation jurisdictions, incorporate environmental retrofit timelines into financial forecasts and captive supply strategies.
- Explore strategic partnerships: For mid-sized producers, consider JV structures with technology leaders to access specialized production routes and compliance expertise quickly and cost-effectively.
Scenario-Based KPIs and Early Warning Signals
To operationalize the report’s insights, PW Consulting recommends tracking a small set of leading indicators:
- Feedstock bid-ask spreads and silicon metal spot movements (monthly).
- Acceptance and qualification cycle times for high-purity grades at OEMs (quarterly).
- Capacity additions announced by top producers and capitalization timelines (continuous; our report tracks announced expansions).
- Regulatory changes in key jurisdictions and public procurement directives that reference high-performance materials (as-issued).
These KPIs, combined with our proprietary demand model, allow commercial teams to convert market signals into contract volumes, pricing corridors, and inventory targets in near real time.
Call to Action: Where to Go from Here
PW Consulting’s report is explicitly structured to support 2026 decision-making. It equips leaders with the scenario models, supplier scorecards, and tactical playbooks necessary to navigate an industry that is growing quickly, consolidating structurally, and subject to evolving regulatory constraints. While this executive summary highlights the structural picture—market size, a robust mid-double-digit growth trajectory in aggregate terms, and concentrated supplier dynamics—the full report contains the detailed segmentation, regional and application breakouts, and downloadable financial models that trading, procurement, and strategy teams will need to execute effectively.
For executives preparing budgets, negotiating supplier terms, assessing M&A targets, or designing product qualification programs, the window to act is now. The choices made in 2026—on capacity commitments, supplier diversification, and regulatory compliance investments—will determine market position through the 2030s.
Further Engagement
Contact PW Consulting to receive the complete Worldwide High Purity Silicon Nitride Powder Market report, including the gated segmentation datasets, scenario-priced supply-demand models, and supplier due-diligence templates. Our team can also provide custom workshops to translate the report’s findings into a tailored action plan for your organization.
For detailed analysis of this topic, please visit the official page: Worldwide High Purity Silicon Nitride Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com