

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Automotive Inspection Services Market to Reach USD 62.8 Billion by 2032, Growing at a 5.66% CAGR

PW Consulting Releases Strategic Briefing: Worldwide Automotive Inspection Service Market — What 2026 Decision‑Makers Need to Know
As the automotive industry accelerates toward software-defined vehicles, electrification and tighter regulatory scrutiny, inspection services have shifted from a compliance backwater to a strategic battleground. PW Consulting’s new market research briefing — based on a 2020–2025 historical base and a 2026–2032 forecast horizon — synthesizes proprietary primary research, vendor interviews and scenario modelling to deliver actionable guidance for executives planning for 2026.
Worldwide Automotive Inspection Service Market
Snapshot: Market Trajectory and Structural Dynamics
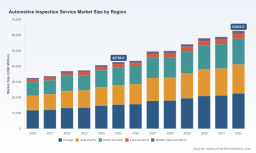
Our analysis values the global automotive inspection services market at approximately USD 42,750.6 Million in the 2025 base year. Under our central case assumptions, the market is forecast to grow at a compound annual growth rate (CAGR) of 5.66% through 2032, reaching an estimated USD 62,830.5 Million by the end of the forecast period. This expansion reflects the interplay of legacy inspection requirements, rising complexity of vehicle systems (EV batteries, ADAS, connectivity), and growing demand for inspection-enabled remarketing and fleet assurance services.
Worldwide Automotive Inspection Service Market
Despite steady headline growth, the market remains structurally fragmented — CR3 and CR5 concentration metrics are low relative to other automotive service segments, indicating that national and specialist players continue to account for a material share of activity. That fragmentation creates both consolidation opportunities and fragmentation-driven execution risk for global entrants.
Worldwide Automotive Inspection Service Market
Why This Report Matters for 2026 Strategic Choices
- Investment prioritization: The briefing translates macro trajectories into risk‑adjusted opportunity pools so CFOs and corporate development teams can prioritize geographies, service lines and capability investments without relying on generic comparables.
- Product and service roadmaps: We map inspection service vectors (statutory testing, pre‑purchase and remarketing inspections, EV and wireless testing, collision program verification) to OEM, fleet and retail demand curves — enabling product managers to align development spend with quantifiable market pull.
- Regulatory preparedness: A forward-looking regulatory tracker highlights national policy moves and county‑level nuances that materially affect service demand and operational models, helping regulatory affairs teams anticipate compliance and advocacy needs.
- M&A and partnership origination: The report’s competitive and capability heatmaps identify gap areas for bolt‑on targets, JV opportunities and partnership frameworks for scale players and local incumbents alike.
What’s Inside: Practical, Transactional and Operational Deliverables
PW Consulting’s briefing was developed to be immediately usable by commercial, operational and corporate development teams. Key deliverables include:
- Market sizing and scenario-based forecasts (base year 2025; forecast 2026–2032) with sensitivity bands and breakpoints tied to EV adoption, ADAS penetration and regulatory shocks.
- Service line playbooks for statutory inspection, pre‑purchase/remarketing inspection, voluntary assurance programs and collision/certified repair networks — each with go‑to‑market models, margin expectations and KPIs.
- Capability gap analysis and prioritized capability build roadmaps (AI inspection, wireless testing, battery diagnostics, cybersecurity assessment) with time‑to‑value estimates.
- M&A screen and valuation priors for targets ranging from national inspection networks to niche testing labs and digital inspection platform providers.
- Regulatory tracker and scenario response playbook that translates legislative changes into operational options (e.g., relocation of testing facilities, emissions‑only testing models, digital proofing for mobile inspection).
- Interactive appendix of primary interviews, supplier and buyer sentiment matrices, and an executable 100‑day and 12‑month action plan for market entrants and incumbents.
Competitive Landscape and Strategic Implications
The competitive environment combines global TIC (testing, inspection and certification) leaders, regional vehicle inspection incumbents and remarketing/digital platform players. Our briefing examines strategic positioning across the leading operators and identifies where scale, digital integration and specialized testing capabilities matter most.
- Large TIC firms (e.g., global testing and certification leaders): These organizations bring broad testing portfolios and global networks that can be leveraged for end‑to‑end OEM and supplier assurance. Their challenge is converting diversified capability into high‑margin, repeatable inspection services tailored for modern vehicle systems.
- Traditional vehicle inspection giants: Longstanding periodic technical inspection leaders retain deep regulatory relationships and operational scale in on‑site inspection networks. Several have publicly announced transformation programs to expand into digital, battery and wireless testing to remain relevant in software‑defined mobility.
- Specialist firms and remarketing integrators: Platform and remarketing players have emerged as critical partners for inspection services tied to used car markets and reconditioning workflows. Integrating digital inspection outputs into marketplace transactions is a rapid source of value capture.
Notable market signals we analyze in depth include strategic moves and partnerships such as expansions of certified collision programs, targeted acquisitions to shore up wireless testing, rebranding of remarketing inspection arms to increase platform integration, and public merger/combination discussions among large TIC firms. These developments underline two themes: scale alone is insufficient — ownership of data flows and digital inspection standards is a decisive differentiator.
Technology, Regulation and Service Innovation — The Forces Rewriting Market Boundaries
Three converging forces are reshaping inspection economics:
- Vehicle complexity: Modern vehicles require battery health diagnostics, wireless protocol and electromagnetic compatibility testing, ADAS calibration and cybersecurity checks. Inspection providers that embed these capabilities will capture incremental wallet share from OEMs, fleets and insurers.
- Digital integration: AI‑driven visual inspection, standardized digital inspection reporting and cloud APIs for marketplace integration are becoming baseline expectations — particularly in remarketing and insurer workflows.
- Regulatory divergence: While some jurisdictions remove legacy annual safety checks for non‑commercial vehicles, emissions requirements and targeted county‑level mandates persist. Providers need nimble operational models that can adapt to mixed regulatory environments.
We quantify the influence of these factors on adoption curves and margin pressure, and we provide concrete build vs buy decision criteria for technology investments. For example, wireless and EV battery testing capabilities can be acquired cost‑effectively through targeted M&A in certain markets, while AI visual inspection platforms may offer faster payback through partnerships or licensing.
Priority Recommendations for 2026
Based on scenario analysis and customer interviews, PW Consulting recommends the following strategic actions for organizations competing in or adjacent to automotive inspection services:
- Hardwire digital inspection outputs: Standardize data schemas and APIs now to ensure inspection outputs can be consumed by OEM warranty systems, remarketing platforms and insurers. Early adopters will set the de facto standards.
- Invest selectively in EV and wireless testing: Prioritize battery diagnostics and wireless certification capabilities in markets where OEM and regulatory demand intersects. Consider partnerships with specialist labs where capital deployment would be slow to scale.
- Build agile operating models: Design mixed‑mode inspection footprints with mobile teams, fixed inspection centers and remote triage supported by AI to optimize cost per inspection while meeting regulatory mandates.
- Pursue bolt‑on consolidation in fragmented markets: Use market concentration asymmetry to acquire regional networks that offer immediate scale and regulatory know‑how. Our M&A screen identifies target archetypes that consistently show rapid synergies.
- Engage regulators proactively: Participation in rule‑making and piloting of digital inspection proofs reduces regulatory uncertainty and creates first‑mover advantages for service models that deviate from legacy gatekeeping frameworks.
How to Use This Briefing in Your 2026 Planning Cycle
Executives should use this briefing as the basis for four immediate planning activities in the 2026 cycle:
- Incorporate the report’s scenario‑based forecasts into capital allocation and product roadmaps to stress‑test investments against both faster electrification and slower regulatory change scenarios.
- Run a 90‑day mobilization to standardize inspection data outputs and negotiate early partnerships with remarketing platforms and insurers.
- Conduct a focused M&A diligence sprint using our target archetypes to assess near‑term consolidation opportunities.
- Establish a regulatory monitoring cell using the report’s tracker to prioritize market entries and exit options based on local legislative shifts.
Next Steps and Access to the Full Intelligence
PW Consulting’s full Worldwide Automotive Inspection Service Market report includes the underlying model, interactive scenario worksheets, detailed vendor capability matrices and country‑level appendices. The briefing above is intended to surface the strategic implications and recommended actions for 2026 decision‑makers while preserving the detailed segment and country data available in the full report.
For subscription access to the complete report, datasets, and our advisory services for execution, please visit the PW Consulting research page or contact your account representative. Our team can provide tailored workshops to convert the briefing into an executable 100‑day plan aligned to your organization’s risk appetite and strategic priorities.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Inspection Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com