

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Dry AMD Market to Reach USD 11,582.2 Million by 2032, Driven by a 10.25% CAGR

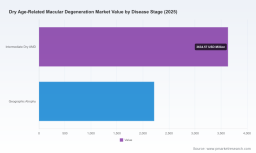
Worldwide Dry Age-Related Macular Degeneration Market: Strategic Intelligence for 2026 Decision-Making
PW Consulting’s latest market study on the Worldwide Dry Age‑Related Macular Degeneration (dry AMD) market synthesizes clinical, commercial, regulatory and reimbursement forces shaping a rapidly evolving therapeutic landscape. Built from a validated patient-flow model, structured interviews with payers and KOLs, and a proprietary commercial adoption framework, the report provides the kind of actionable intelligence that corporate strategy, business development, and commercial teams need to set winning priorities in 2026.
Worldwide Dry Age-Related Macular Degeneration Market
Executive snapshot: market trajectory and competitive shape
Dry AMD is transitioning from an area with no disease‑modifying options to a competitive, multi‑modal market. Our macro forecast places the market at USD 5.85 billion (base year 2025) with a compound annual growth rate of 10.25% through the forecast horizon. This pace of expansion reflects a combination of approved complement inhibitors, newly authorised non‑invasive devices, late‑stage oral candidates, and an accelerating gene‑ and cell‑therapy pipeline. Market concentration is meaningful: the top three players control a majority share (CR3 ~58.4%), and the top five approach three‑quarters of the market (CR5 ~72.1%), indicating strategic opportunities for mid‑sized entrants and differentiated modalities to carve out sustainable niches.
Worldwide Dry Age-Related Macular Degeneration Market
Why this report matters for 2026 planning
- Translate clinical readouts into go/no‑go choices: With multiple Phase 3 and pivotal programs maturing, 2026 will be a turning point for portfolio prioritisation. The report maps clinical timelines to commercial levers so R&D and BD teams can quantify the market impact of a late‑stage win or setback.
- Model payer scenarios: Reimbursement for chronic intravitreal regimens is under scrutiny; our payer scenarios simulate unit cost, adherence erosion, and coverage thresholds to show how price, administration frequency, and real‑world effectiveness change Net Present Value (NPV) outcomes.
- Commercial readiness and launch playbooks: We provide practical guidance on channel mix, retina clinic engagement, hub‑and‑spoke infusion and injection pathways, and patient support strategies that drive uptake while containing cost of care.
- Manufacturing and supply risk assessment: The report enumerates common biologics and device manufacturing constraints and proposes contingency models and cost‑to‑scale assumptions for capital planning.
What’s inside: report content that drives execution
- Market sizing & forecasting methodology: Transparent assumptions, inputs, and sensitivity checks—enabling teams to re‑run scenarios under alternative prevalence, uptake, or pricing assumptions.
- Patient flow & treatment pathway models: Stage‑specific incidence/prevalence and diagnosis‑to‑treatment timelines that feed commercial demand curves.
- Value and access playbooks: HTA submission templates, payer evidence dossiers, and real‑world evidence (RWE) strategies tailored to high‑value payers.
- Segment economics: Profitability benchmarks and margin drivers across modalities (injectables, oral agents, gene and cell therapies, and devices).
- Competitor intelligence: Profiles, near‑term catalysts, SWOTs, and commercialization strategies for leading biotech and pharma players active in dry AMD.
- M&A and licensing framework: Valuation ranges under multiple uptake scenarios, milestone structures that bridge clinical risk, and post‑deal integration playbooks.
Competitive landscape: who matters and why
The competitive table in dry AMD already combines commercial leaders with deep pipelines. Intravitreal complement inhibitors launched in recent years have established the first routine treatment regimens for geographic atrophy, changing both clinical practice and payer calculus. At the same time, non‑invasive photobiomodulation devices, oral visual cycle modulators, mitochondria‑targeted peptides, gene modifiers and RPE cell therapies are maturing—creating a diverse therapeutic mix where modality choice will depend on efficacy tradeoffs, administration frequency, safety profiles and cost of care.
Worldwide Dry Age-Related Macular Degeneration Market
- Established commercial entrants: Companies that have commercialised first‑generation complement inhibitors now face choices about label expansion, dosing cadence, and lifecycle management to protect share from oral and gene alternatives.
- Late‑stage challengers: Several US‑based small and mid‑cap developers are advancing oral agents and novel biologics through Phase 3, offering differentiated value propositions centered on administration convenience and mechanistic diversity.
- Large pharma and strategic players: Global pharmas and big biotechs are active through collaborations, acquisitions and in‑house programs—bringing scale, payer relationships and regulatory experience that influence market access dynamics.
Key companies featured in the report include commercial leaders and high‑impact developers across modalities: Apellis Pharmaceuticals, Astellas Pharma, LumiThera, Alkeus Pharmaceuticals, Belite Bio, Stealth BioTherapeutics, Annexon Biosciences, Lineage Cell Therapeutics, Aviceda Therapeutics, Ocugen, Roche, Novartis, Regeneron, Johnson & Johnson Innovative Medicine, and Boehringer Ingelheim. For each, we provide a concise profile, clinical and regulatory timeline, and a calibrated assessment of commercial potential—crucial input for partnership, defence and launch plans.
Recent developments shaping 2026 strategies
- Astellas’ regulatory update in early 2025 extended the practical label for its intravitreal therapy, altering treatment duration assumptions and influencing patient retention forecasts.
- Ocugen completed dosing in a Phase 2 gene‑modifier study, a milestone that will determine the feasibility and timing of a registrational path.
- Late‑stage data from an oral visual cycle modulator demonstrated meaningful quality‑of‑life preservation signals—reshaping assumptions about non‑injectable adoption among earlier‑stage patients.
- Sanofi’s Fast Track designation for a one‑time gene therapy underscores regulator and industry interest in durable solutions that could upend recurring‑treatment economics.
- Regulatory momentum for non‑invasive devices—illustrated by recent device clearances—introduces alternative care pathways that payers may prefer for early and intermediate disease.
Dynamics to watch: payer, patient and regulatory inflection points
Three structural dynamics will dominate strategic choices in 2026:
- Payer scrutiny of chronic intravitreal schedules: Therapies requiring monthly or bi‑monthly injections raise adherence and total cost concerns. Our payer models show how frequency reductions and real‑world effectiveness can materially change formulary position.
- Clinical benefit vs. expectation gap: Existing disease‑modifying therapies slow lesion growth but do not restore lost vision. This efficacy profile affects uptake curves, patient demand, and HTA value thresholds—especially where quality‑adjusted life‑year (QALY) frameworks remain dominant.
- Modal diversity: The expanding set of modalities (orals, device, gene/cell) creates cross‑modal competition and opportunities for combo strategies; commercial teams must make deliberate choices about indication sequencing and co‑promotion tactics.
Actionable recommendations for 2026 corporate planning
- Prioritise modality fit to target segment: Align clinical development and commercial plans to the patient segment most likely to benefit and payers most likely to cover—early adoption pathways differ for GA vs earlier stages.
- Design payer‑centric evidence generation: Invest in pragmatic trials and RWE that demonstrate functional outcomes, adherence, and cost offsets (e.g., delayed progression to advanced AMD clinics) to support reimbursement.
- Prepare differentiated launch architectures: For injectables, build retina clinic partnerships and hub services; for orals and devices, focus on primary ophthalmology networks and retail distribution strategies.
- Scenario‑based portfolio valuation: Use our sensitivity analyses to re‑price assets under alternative uptake, pricing and manufacturing cost scenarios—essential for BD&L negotiations and M&A risk adjustment.
- Advance patient affordability solutions: Develop access programs that mitigate initial uptake friction while preserving long‑term payer relationships; consider outcomes‑based contracting where possible.
Why PW Consulting’s report is the strategic lever for 2026
This study is designed as a decision support tool, not merely a market narrative. We combine modelling transparency, clinical insight, payer simulation and competitive forensics to give teams the ability to run "what‑if" scenarios and prioritise investments ahead of critical 2026 catalysts. The analysis is deliberately deep on cross‑modal tradeoffs and commercial playbooks while omitting proprietary subsegment allocations in public summaries—ensuring our clients gain the full competitive advantage from the detailed intelligence.
Next steps
For teams preparing board presentations, refining 2026 budgets, third‑party partnering and HTA submissions, the report provides executable recommendations and the quantitative tools to defend them. To access the complete dataset, segmented forecasts and actionable annexes (including payer evidence templates and financial models), please visit PW Consulting’s report page or contact our strategy desk to arrange a briefing and customised scenario run.
For detailed analysis of this topic, please visit the official page: Worldwide Dry Age-Related Macular Degeneration Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com