

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Portable Single‑Phase Generator Market to Grow at a 5.18% CAGR, Powering New Opportunities Through 2032

Worldwide Portable Single Phase Generator Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting is pleased to release an executive briefing drawn from our comprehensive market research report on the Worldwide Portable Single Phase Generator Market (base year 2025). This briefing synthesizes the structural dynamics, competitive pressures, regulatory inflections, and near‑term strategic options that corporate leaders, OEMs, distributors, and private equity investors must weigh as they plan through 2026.
Worldwide Portable Single Phase Generator Market
Market snapshot: scale, trajectory, and concentration
The portable single‑phase generator market has demonstrated steady expansion over the past half decade, rising from approximately USD 4.12 billion in 2020 to USD 5.35 billion in 2025. Our forecast baseline projects continued growth through the 2026–2032 window at a compound annual growth rate (CAGR) of 5.18%, culminating in a market approaching USD 7.62 billion by 2032. These headline figures reflect resilient demand drivers — from residential backup and outdoor recreation to construction and rental fleets — even as the market navigates tightening emissions standards and raw material volatility.
Worldwide Portable Single Phase Generator Market
Market concentration is moderate: the top three global players account for a significant share of the market, and the top five consolidate a clear majority, underscoring both the importance of scale in distribution and the opportunity for well‑capitalized challengers to capture adjacencies. Specifically, PW Consulting calculates a CR3 of approximately 42.5% and a CR5 near 58.3%, signaling that competitive positioning and channel partnerships remain decisive.
Worldwide Portable Single Phase Generator Market
Why this report matters for 2026 strategy
- Pivotal planning horizon. 2026 is the first full post‑pandemic planning year in which several regulatory and supply‑chain adjustments crystallize. Our analysis translates macro forecasts into scenario roadmaps that inform inventory, product roadmap prioritization, and go‑to‑market timing.
- Revenue and margin leverage. The market’s steady CAGR masks divergent margin trajectories across product types (inverter vs. traditional), fuel platforms, and distribution channels. The report isolates profit pools and identifies where price discipline versus feature‑led premiumization will most effectively protect margins.
- Regulatory and procurement readiness. With states and regions accelerating low‑emission mandates and OEMs revising certification strategies, the report provides a regulatory playbook enabling procurement and product teams to minimize compliance lag and capitalize on temporary regulatory relief windows.
High‑level segmentation trends (detail withheld in this public summary)
Our full study models the market across region, fuel type, and end‑use application, with granular unit, revenue, and ASP trajectories through 2032. In this public synopsis we intentionally withhold the granular split values — the report is structured to balance confidentiality with utility, so readers must access the full dataset for exact subsegment numbers. That said, readers should note these directional dynamics:
- Fuel mix evolution. Gasoline‑powered units continue to command broad adoption in residential and recreational applications, but inverter and dual‑fuel options are gaining share as consumers and commercial buyers prioritize efficiency, lower noise, and cleaner electrical output.
- End‑use divergence. Residential backup demand remains the steady backbone of market volumes, while construction, rental fleets, and events represent high‑margin, serviceable markets that react more sharply to macro construction activity and event calendars.
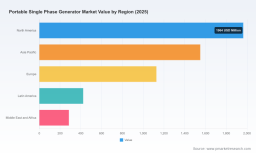
- Regional differentiation. Growth patterns vary by region based on electrification rates, grid reliability, and localized emissions policy. Supply‑chain cost pressures and distribution density are critical determinants of competitive advantage.
Competitive landscape — what leading suppliers are doing
We evaluated global manufacturers across capability, channel footprint, regulatory preparedness, and product breadth. Public and private players leading or reshaping the market include established engine and equipment OEMs as well as global rental and OEM exporters. Representative profiles and strategic moves include:
- Honda Motor Co., Ltd. — continues to leverage its engine technology and inverter expertise to emphasize fuel efficiency, low noise, and clean sine‑wave output for residential and leisure segments.
- Generac Holdings Inc. — expanded its 2025/2026 lineups with CA‑compliant inverter and EPA‑certified models, positioning to defend the U.S. residential market while focusing on emissions compliance and serviceability.
- Yamaha Motor Co., Ltd. and Briggs & Stratton. — maintain reputational strengths in reliability and engine supply, with product evolution toward quiet, efficient inverter models for both consumer and jobsite use.
- Cummins, Kohler, Atlas Copco, Wacker Neuson. — each leverages industrial and rental channels to supply diesel and gas solutions for construction and commercial applications where uptime and service support command premiums.
- Smaller OEMs and exporters. — a cohort of China‑based and European manufacturers supply competitively priced units for global wholesale and OEM channels; their growing certification activity (e.g., CE expansions) is notable for distribution partners seeking cost alternatives.
Across profiles, differentiation is increasingly defined by: inverter technology, noise and emissions performance, integrated telematics and power management features, and aftermarket service models. The winners in 2026 will be those who can combine product compliance with efficient distribution and a flexible parts/service network.
Regulatory and input‑cost dynamics to watch
- Emissions policy volatility. Regulatory developments — including temporary CARB relaxations in early 2025 and forward trajectories toward tighter small‑engine rules — create windows of demand and compliance risk. Executives should treat short‑term relief as transitory and prioritize longer‑term transition plans (e.g., electrified or zero‑emission alternatives) where market access is at stake.
- Non‑road diesel standards. Enforcement and guidance from regulators such as the U.S. EPA (including recent clarifications on DEF fault timing) affect diesel generator uptime and warranty exposure. Product engineering teams must validate derate logic and service diagnostics to avoid field failures that erode brand equity.
- Raw material pressures. The U.S. designation of copper as a critical mineral and ongoing price volatility directly impact alternator and wiring costs. Procurement strategies — including hedging, multi‑sourcing, and design efficiency (reducing copper intensity where possible) — will materially affect gross margins.
Recent market movements with strategic implications
- Product launches. Generac’s 2025 line refresh, which included California‑compliant inverter variants, highlights how incumbents use regulatory compliance as a product differentiator and shelf‑availability advantage.
- Certification expansion. Several export‑oriented OEMs are accelerating CE and other international certifications to broaden addressable markets; this trend matters for distributors vetting alternative suppliers.
- Regulatory relief windows. Temporary measures to ease emissions compliance in fire‑affected regions created near‑term surges; senior leaders must plan for such episodic demand spikes without overcommitting long‑term capacity.
What the full PW Consulting report delivers (practical, decision‑grade content)
PW Consulting’s full market study is designed as an operational toolkit for 2026. It blends forward‑looking quantitative models with qualitative playbooks and includes:
- Detailed revenue and unit forecasts by year (2026–2032) across regions, fuel types, and end‑use categories (note: granular splits are available in the full report).
- Segment‑level profitability and ASP analyses that identify short‑term margin expansion levers and long‑term cost risks.
- Scenarios that simulate regulatory shifts, raw‑material price shocks, and channel disruption, with tactical response options for each scenario.
- Competitive benchmarking and capability maps for the leading suppliers, with suggested strategic moves for market entrants, tier‑1 OEMs, and aftermarket service providers.
- Commercial playbooks: product roadmap prioritization templates, inventory and logistics stress tests, go‑to‑market timing calendars tied to certification cycles, and M&A target screening criteria.
Executive recommendations for 2026
- Adopt a two‑track product strategy. Protect core gasoline inverter offerings for residential channels while validating a lower‑emissions roadmap (dual‑fuel or electrified alternatives) for regulatory hot spots and premium commercial customers.
- Prioritize certification and supply resilience. Invest in regulatory engineering and multi‑tier supplier relationships for critical components (alternators, control electronics, copper procurement) to avoid market access and margin erosion.
- Monetize aftermarket services. Build service bundles and telematics‑enabled maintenance contracts to shift revenue toward recurring streams and reduce cyclicality tied to unit sales.
- Use temporary regulatory relief for competitive positioning — not complacency. Leverage any short‑term access windows to capture share, but maintain transition investments to meet likely stricter standards by the late 2020s.
- Consider bolt‑on acquisitions for channel depth. In markets with concentrated distribution, acquiring or partnering with regional rental players and aftermarket networks can accelerate market reach and margin capture.
Next steps and how to access the full intelligence
This briefing is intended to equip senior teams with a high‑confidence, actionable view of market direction and to illustrate the kinds of levers explored in depth in our proprietary model. For legal, product, commercial, and M&A teams seeking the exact subsegment figures, market shares by region and fuel type, and the complete set of scenario‑tested playbooks, the full PW Consulting report and accompanying data workbook are available through our distribution portal.
PW Consulting stands ready to brief executive teams and boards on tailored implications from the report, run interactive scenario workshops, or provide a customized market map focused on your product lines and geographies of interest. Contact our strategy desk to schedule a confidential consultation and obtain the complete dataset necessary for 2026 strategic planning.
For detailed analysis of this topic, please visit the official page: Worldwide Portable Single Phase Generator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com