

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Glass Substrates for LCD Market Poised to Reach USD 10,728.4 Million by 2032, Growing at a 3.65% CAGR (Forecast 2026–2032)

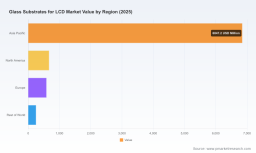
Worldwide Glass Substrates for LCD Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
PW Consulting’s new market study, base year 2025, delivers an evidence-based vantage point for executives shaping LCD strategies in 2026. The worldwide glass substrate market for LCD applications is projected to grow from an estimated USD 8,350.25 Million in 2025 to approximately USD 10,728.4 Million by 2032, reflecting a compound annual growth rate (CAGR) of 3.65% over the 2026–2032 forecast period. These headline numbers capture a market that is stable, capital-intensive and increasingly shaped by a small set of vertically integrated producers and policy-driven trade dynamics.
Worldwide Glass Substrates for LCD Market
Why this report matters for 2026 planning
-
Decision clarity in a concentrated market: The market concentration is high — the top three players account for roughly 88.5% of supply, rising to 96.2% for the top five — which means procurement, technology and investment strategies must be formulated against a supplier landscape that offers limited negotiating breadth.
Worldwide Glass Substrates for LCD Market -
Mid-single-digit CAGR with asymmetric supply risk: The modest 3.65% CAGR masks uneven upside across product formats and application windows. For buyers and investors this translates into predictable aggregate demand but pronounced supplier and material risks at the node (high-purity alkali-free glass for high-resolution panels).
Worldwide Glass Substrates for LCD Market -
Regulatory and geopolitical overlays: Since 2024–2025, regulatory frameworks and trade policy have become material drivers. Examples include stricter chemical content limits under EU rules and export-control implications for advanced substrate technologies — factors that can change supplier eligibility overnight.
Key dynamics shaping 2026 decision-making
-
Material cost structure and sourcing lead times: Alkali-free borosilicate feedstock represents a dominant share of substrate material cost due to high-purity silica requirements, and industry lead times for high-purity silica extended materially in 2025. Strategic buyers must incorporate extended procurement lead times (now measured in months) into inventory and investment models.
-
Regulatory compliance as a market access criterion: New substance limits and reporting requirements (e.g., limits on heavy metals under recent European chemical regulations) mean compliance is no longer a hygiene factor — it is a gating criterion for supply, particularly for panels destined to regulated end-markets such as medical or industrial displays.
-
Trade policy and localized capacity build-out: Export controls and tariff measures that emerged in 2025 have catalyzed both capacity reallocation and local content strategies. These policies have immediate implications for where producers choose to build Gen 10.5/Gen 11 facilities and for how global OEMs structure multi-sourced supply networks.
-
Capital intensity and technological barriers: Gen-size scaling (large-format glass), ultra-low defect rates, and thermal/expansion tolerances for high-resolution panels keep the technology bar high. New entrants face elevated capex and long qualification cycles, reinforcing incumbent advantages.
What PW Consulting’s report delivers — practical, operational intelligence
-
Actionable supplier scorecards: comparative diagnostics that go beyond public profiles to assess capacity by generation, quality performance, qualification timelines and contractual flexibility.
-
Procurement playbooks and contract language templates: model long-term offtake agreements, clauses for force majeure and regulatory change, and dynamic pricing triggers tied to raw material indices.
-
Capex and network optimization tools: scenario-based models for factory sizing, nearshoring vs. export-driven capacity, and sensitivity testing against tariffs and export-control scenarios.
-
Technology roadmaps and qualification checklists: milestone-based guidance for panel manufacturers evaluating next-generation alkali-free or low-expansion glass, including test protocols for thermal stability and defect characterization.
-
Risk heatmaps and mitigation playbooks: prioritization of supply constraints (e.g., silica feedstock lead times), regulatory blockers (chemical compliance) and geopolitical exposures, with mitigation portfolios ranked by cost and time-to-implement.
-
M&A and partnership guidance: valuation frameworks attuned to high concentration, integration risks and the value of strategic relationships with panel manufacturers and raw material suppliers.
Competitive landscape — who matters and why
The market is dominated by a small set of specialist glass manufacturers, each with distinctive capabilities and strategic positioning. Below is an executive reading of the major players that will shape supplier-dependent strategies in 2026.
-
Corning Incorporated (Corning, NY, USA) — A technology-leader in alkali-free glass innovation. Corning’s EAGLE XG family has been positioned for ultra-thin and large-format LCD panels, and the company’s recent qualification of a next-generation slim substrate in late 2025 signals continued premium innovation and focus on high-end TV and monitor segments.
-
AGC Inc. / Asahi Glass (Tokyo, Japan) — AGC supplies high-transmission AN-series sheets and has moved to increase large-format capacity, including new Gen 11 output ramping in 2025. AGC’s strength is scale and integrated process quality for low-defect, large-size panels.
-
Nippon Electric Glass (Otsu, Japan) — NEG’s emphasis on thermal stability and precision (noted by recent certifications) makes it a preferred supplier for high-resolution IT and specialized industrial displays.
-
Schott AG (Mainz, Germany) — A strategic supplier for specialty and low-expansion glass variants used in industrial and medical applications where dimensional stability and certification traceability are critical.
-
Tunghsu Group, AVIC Sanxin, IRICO (China) — Regional champions focused on mid-to-large generation supply chains. Recent long-term commercial agreements and upstream integration moves point to a Chinese supplier base strengthening its reliability and cost-competitiveness for domestic panel makers.
Recent industry moves that matter for 2026
-
New product qualifications and Gen upgrades by major suppliers accelerate the technology migration curve for OEMs that target ultra-thin and large-format displays.
-
Facility expansions in Japan and China, plus long-term supply deals between domestic glass producers and major panel makers, are reshaping the distribution of large-generation capacity — a critical dynamic for any company planning production ramps in 2026.
-
Updated process certifications and quality accreditations reduce qualification friction but increase compliance expectations from buyers — meaning procurement cycles will shorten for compliant suppliers and lengthen for others.
Strategic implications & recommended actions for 2026
-
For OEMs and panel manufacturers: institute dual-track sourcing that pairs a certified tier-1 incumbent with a qualified regional partner; include contingency inventory and index-linked pricing to cover extended silica lead times.
-
For glass manufacturers: prioritize certifiable compliance (chemical and process), accelerate Gen-scaling investments selectively, and lock strategic offtake with anchor panel customers to de-risk capex.
-
For investors and private equity: focus diligence on operational resilience (feedstock security, qualification timelines) and the strategic value of incumbents’ customer relationships rather than only on pure capacity metrics.
-
For policymakers and trade analysts: consider the systemic impact of export controls and tariffs on critical display supply chains; pragmatic exemptions or time-phased transitions can reduce near-term market dislocation.
Decision-maker playbook (teaser)
-
1) Map your exposure: quantify share of demand by glass generation and lead time sensitivity.
-
2) Engage anchor suppliers: negotiate phased capacity rights with quality and compliance SLAs.
-
3) Model scenarios: run tariff, export-control and feedstock delay scenarios through P&L/cash models.
-
4) Invest selectively: de-risk with modular capex or contract manufacturing vs. greenfield builds.
-
5) Build compliance roadmaps: prioritize certifications and substance reporting that enable access to regulated end-markets.
-
6) Prepare M&A playbooks: identify bolt-on targets that add feedstock security, regional presence or qualification speed.
PW Consulting’s full report includes templated tools, Excel-ready scenario models and supplier assessment matrices aligned to each playbook item — precisely the assets teams need to move from strategy to execution in 2026.
How to use this intelligence now
If you are prioritizing capital allocation, supplier negotiations or regulatory-compliance investments in 2026, treat this report as a tactical compass: it grades supplier resilience, lays out pragmatic sourcing options and provides the templates executives can use to operationalize contingency plans within weeks. The aggregated market path (USD 8,350.25 Million in 2025 → USD 10,728.4 Million by 2032 at 3.65% CAGR) should be a planning input, not a sole decision trigger — the differentiated value lies in granular supplier, technology and regulatory diagnostics contained in the full study.
Next steps
For full access to the report’s segmented analyses, supplier scorecards, scenario models and downloadable playbooks, visit the PW Consulting publications page. The detailed segmentation tables, contractual language templates and Excel scenario workbooks are available only in the full report — the precise materials procurement, strategy and legal teams will use to operationalize a 2026 plan.
For detailed analysis of this topic, please visit the official page: Worldwide Glass Substrates for LCD Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com