

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Aviation Refueling Hose Market Poised to Grow at a 5.22% CAGR Through 2032

PW Consulting Releases Strategic Brief: Worldwide Aviation Refueling Hose Market Outlook — A 2026 Decision-Ready Preview
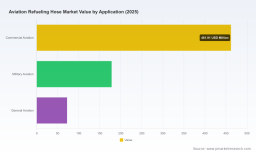
PW Consulting today publishes an executive preview of its forthcoming Worldwide Aviation Refueling Hose Market report. Built on a 2020–2025 historical foundation with 2025 as the base year, and forward-looking across a 2026–2032 forecast window, the study synthesizes industry structure, regulatory imperatives, supplier capability, and demand drivers into a decision-focused playbook. The global market — valued at roughly USD 712.5 Million in 2025 — is projected to expand at a compound annual growth rate (CAGR) of approximately 5.22% through the forecast horizon, reflecting both steady commercial aviation traffic recovery and accelerating military and specialty refuelling programs.
Worldwide Aviation Refueling Hose Market
Why this preview matters for 2026 corporate strategy
-
Timing and clarity: With procurement cycles, qualification lead-times and military contracting windows increasingly compressed, buyers and suppliers need concise, actionable intelligence now — not after lengthy bespoke studies. Our preview translates macro momentum into discrete strategic levers for 2026 planning.
Worldwide Aviation Refueling Hose Market -
Risk visibility: The market shows growing supplier concentration at the top tiers (CR3 ≈ 42.5%; CR5 ≈ 58.8%), implying both opportunity and single-source risk. Organizations must weigh supplier performance against resilience and regulatory traceability when setting sourcing priorities.
Worldwide Aviation Refueling Hose Market -
Technology and material inflection: Rapid adoption of sustainable aviation fuels (SAF) and advanced composite/reinforced hose constructions creates procurement and R&D choices that will deterministically shape total cost of ownership through the latter half of the decade.
Key data signals — what the numbers are telling buyers and investors
-
Market trajectory: After a mid-cycle dip in the early 2020s, total value expanded to the 2025 base. Our forecast scenarios model continued expansion, with the market approaching the billion-dollar threshold before the end of the forecast window under the central case. That trajectory is sufficient to justify targeted capacity investments for firms with clear differentiation on technology, certification and aftermarket support.
-
Consolidation pressure: The measured market concentration demonstrates that scale, certification footprint and channel reach materially influence win-rates on large public and military tenders. For challengers, the path to defensibility runs through niche specialization, speed of certification, and selective partnerships rather than broad replication of incumbent strengths.
-
Regulatory and test gating: Compliance with standards such as EI 1529 (latest edition), ISO 1825, API 1529 and NFPA 407 — combined with mandatory 100% hydrostatic testing and electrical continuity verification — means that performance claims without provenance are commercially ineffective. Traceability and testing records are becoming purchase requisites rather than purchase differentiators.
Competitive landscape — who matters and why
The supply base is a mix of large diversified industrial players, specialist hose manufacturers and regionally-focused producers. Several firms repeatedly surface in contract awards, platform approvals and global distribution: established names such as Hewitt (Husky Corporation), Continental (ContiTech), Parker Hannifin (Parker Industrial Hose), Eaton (Aeroquip) and ELAFLEX HIBY; defense-focused specialists such as Icon Aerospace and Aero-Hose Corp.; and capable low-cost producers from Asia such as Orientflex and Zebung Rubber Technology. Each cluster brings distinct strategic propositions:
-
Tier-1 industrials (e.g., Husky, Continental, Parker, Eaton): breadth of product lines, multi-standard certifications, and global service networks that favor large-scale airline groups, ground service providers and defense programmes.
-
Specialist OEMs (e.g., Icon Aerospace, Aero-Hose): bespoke engineering and defense pedigree that accelerate approvals for in-flight refuelling and mission-critical systems.
-
Regional manufacturers and suppliers: cost competitiveness and rapid local support, often attractive for secondary fleets, local fixed-base operators and emerging-market airports.
Recent industry developments underscore shifting dynamics: major materials and component acquisitions that expand thermoplastic and composite capabilities; defense fleet transactions and training contracts that spur demand for specialized hose assemblies; and exhibitions highlighting coupling technologies and permanent fittings. Together these moves emphasize three strategic vectors — materials innovation, aftermarket service, and certification velocity.
Regulatory, material and testing dynamics that shape the next procurement cycle
-
Standards as market gatekeepers: Buyers should expect procurement specifications to include full compliance evidence to EI 1529 (and relevant local/industry variants), ISO 1825, API 1529 and NFPA 407, along with serialised test certificates. This raises the bar for small suppliers that lack test-lab integration or certified supplier chains.
-
Materials shift: Nitrile-based elastomers remain predominant for fuel compatibility, but polyurethane blends, fluorosilicone and advanced composite reinforcements are gaining traction where abrasion resistance, weight reduction and SAF compatibility are critical. Sourcing strategies must therefore include material qualification roadmaps tied to product life-cycle modelling.
-
Quality and traceability: 100% hydrostatic testing regimes, electrical continuity verification and serialized documentation create opportunities for digital traceability solutions — from QR-linked test records to integrated ERP/LIMS reporting — which can become a competitive differentiator when embedded into sales contracts and long-term service agreements.
Practical deliverables in the full report — what decision-makers will get
Our full report provides operational assets designed for immediate use by procurement, product and corporate development teams. Highlights include:
-
Comprehensive market model (Excel) with scenario toggles for traffic growth, SAF adoption rates and defense fleet procurement timelines.
-
Supplier scorecards and a capability matrix benchmarking certification coverage, test-lab capacity, coupling technologies, and aftermarket footprint.
-
Procurement playbooks: RFP language templates, evaluation matrices prioritizing resilience and traceability, and recommended contract clauses for warranty and acceptance testing.
-
R&D and materials roadmap: comparative performance summaries for nitrile, polyurethane and specialty elastomers against SAF and high-aromatic fuel profiles, plus guidance on accelerated qualification pathways.
-
M&A / partnership watchlist: prioritized targets and collaboration archetypes for entrants seeking rapid capability build via bolt-ons or joint ventures.
-
Aftermarket economics: service network optimisation, refurbishment vs replace decision trees, and TCO models that align with fleet utilization patterns.
How to translate the preview into 2026 actions — prioritized recommendations
-
For OEMs and Tier-1 suppliers: accelerate certification processes for SAF-compatible materials; bundle test-traceability into product offerings; and selectively pursue add-on acquisitions that close capability gaps (materials, permanent coupling technologies, digital traceability).
-
For ground-handling and fuel service operators: renegotiate long-term supply agreements to include serialized testing records and SLAs for repair turnaround; evaluate multi-supplier sourcing to reduce single-supplier exposure given measured market concentration.
-
For defence contractors and integrators: prioritize suppliers with demonstrated in-flight refuelling heritage and bespoke design capability; build qualification contingencies into contract planning to prevent schedule slippage from testing bottlenecks.
-
For private equity and strategic investors: evaluate targets that combine differentiated material IP, regulatory-tested product lines and aftermarket service networks — these attributes materially compress downside risk in exit scenarios.
Strategic implications for capital allocation and partnerships
Capital deployed into this market should be governed by three lenses: certification velocity, aftermarket capture, and material differentiation. Investments that shorten time-to-certify or expand scope of test-capable manufacturing offer outsized returns by unlocking higher-margin defense and OEM contracts. Partnerships that link hose manufacturers with coupling specialists or digital traceability vendors can convert product specification stickiness into recurring service revenues.
Next steps — how to access the full intelligence
This release is a strategic preview designed to equip executive teams with the context and prioritization framework needed for 2026 planning. The full Worldwide Aviation Refueling Hose Market report includes the granular segment-level breakdowns, supplier mappings, pricing benchmarks and downloadable models that underpin transaction diligence and procurement execution. For access to the complete dataset, segmented forecasts, supplier scorecards and bespoke briefing workshops, please visit our report page or contact your PW Consulting industry lead.
PW Consulting’s aviation materials and supply-chain practice stands ready to translate the report’s findings into tailored procurement strategies, qualification roadmaps and M&A mandates. In a market where regulatory proof and operational resilience decide tender outcomes, the right intelligence — and the ability to operationalize it — will define winners in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Aviation Refueling Hose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com