

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Non-woven Sponge Market to Expand at a 4.82% CAGR, New Insights Report Reveals

Worldwide Non-woven Sponge Market: Strategic Preview for 2026 Decision-Makers
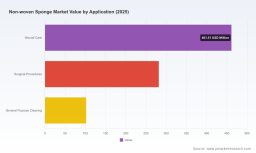
PW Consulting’s newest market study on the Worldwide Non-woven Sponge Market delivers a concise, decision-ready briefing for executives planning 2026 strategies. The sector has moved from niche medical consumables to a core component of modern wound care, surgical workflows, and general hygiene applications. Our analysis shows the market expanded from approximately USD 670 million in 2020 to roughly USD 845.5 million in 2025, and — at a compound annual growth rate (CAGR) of 4.82% — is projected to reach the neighborhood of USD 1.17 billion by 2032. This preview outlines the strategic implications of that trajectory without divulging the granular segmentation readers will find in the full report.
Worldwide Non-woven Sponge Market
Why this matters for 2026
- Mid-single-digit CAGR means incremental volume and margin opportunities, but also intensifying competition for mid‑market share and procurement advantage.
- Medical procurement cycles, regulatory updates, and raw material swings are converging in 2026 to create both short-term disruption risks and long-term repositioning opportunities.
- The market is moderately concentrated; leading incumbents retain a noticeable share, yet there is meaningful room for innovative entrants and regional champions to scale quickly with targeted investment.
Market Dynamics — what’s driving change
- Regulatory tightening: Since the EU Medical Device Regulation updates, non‑woven sponges used in medical contexts must meet stricter classification and packaging standards. Compliance is no longer a checkbox — it is a product development and commercial access determinant.
- Raw material volatility: Polypropylene price behavior continues to create cost headwinds for producers. Industry sources show elevated feedstock pricing in late 2024, and procurement teams should assume periodic price shocks when modelling 2026 scenarios.
- Trade and tariff pressure: Ongoing trade measures, including tariffs on certain imported non‑woven fabrics, materially affect sourcing strategies, reshoring economics, and landed cost calculations for firms reliant on cross‑border supply from Asia.
- Labor and manufacturing economics: Rising manufacturing labor costs in key markets are accelerating automation conversations. For 2026 capital planning, automation and lean-process investments increasingly dominate ROI models versus simple headcount substitution.
Competitive landscape — what the leaders are doing
Our report profiles the strategic postures of the industry’s core players and extracts playbook implications for market entrants and incumbents alike. Key observed patterns include product line refinement, compliance investments, distribution consolidation, and selective vertical integration.
Worldwide Non-woven Sponge Market
- Cardinal Health: Recent product expansion highlights a shift toward higher‑value, performance-differentiated surgical prep sponges. This signals a focus on premiumization in clinical channels.
- 3M Health Care: Ongoing catalog refreshes and new sterile SKUs indicate continued investment in breadth and clinician-driven formats — a defensive posture aimed at protecting hospital-facing relationships.
- Medline Industries: Certification renewals and quality-system investments reflect a longer-term bet on supply reliability and institutional contracts where certification pedigree matters.
- McKesson Corporation & Halyard / Owens & Minor: Distribution-dominant players emphasize cost-effective assortments and integrated supply solutions, reinforcing the importance of channel partnerships in procurement cycles.
- Berry Global & Freudenberg Medical: Materials and OEM-focused manufacturers are leaning into custom non‑woven formulations and co-development, making them preferred partners for device and hygiene OEMs.
- Pidegon Nonwovens (China): Export-oriented producers continue to compete on lead-time and cost, but trade barriers and quality assurance expectations are reshaping their addressable opportunity set.
Market concentration metrics show that the top three and top five firms hold non-trivial portions of the market — enough to influence pricing dynamics and access to large institutional contracts — yet leave space for targeted challengers to build scale through specialization, channel focus, or regional strength.
Worldwide Non-woven Sponge Market
Strategic implications for 2026 planning
- Dual-track sourcing strategy: For manufacturers and large buyers, adopt a “local capacity + global backup” model. Secure near-term continuity via diversified supplier panels while investing in regional capacity where tariff and regulatory exposure is highest.
- Differentiate through performance and certification: Clinical buyers are shifting toward performance-validated, low-lint, high-absorbency solutions with traceable compliance. Investment in clinical validation and certification should be prioritized over cost-only product launches.
- Use pricing models that absorb feedstock volatility: Introduce indexed pricing clauses, strategic polypropylene hedging, or multi-year supply agreements to stabilize margins in 2026 procurement cycles.
- Targeted M&A & partnerships: Acquisition of niche non‑woven innovators or partnerships with regional converters offers faster access to differentiated materials and new channel reach than greenfield expansion.
- Automation and process intensification: Given rising labor costs, 2026 CAPEX should prioritize automation projects that reduce variable cost per unit and improve consistency — key in sterile medical product lines.
- Channel-led commercialization: For suppliers, prioritize hospital system contracts and OEM co-development over mass retail push unless scale economics are secured. Distributors remain gatekeepers for large accounts; align commercial incentives accordingly.
What PW Consulting’s full report delivers (practical, actionable outputs)
Our full market study is structured to be immediately usable by strategy, commercial, procurement, and M&A teams. Highlights include:
- Market-sizing and trend decks with scenario modeling across 2026–2032 (base year 2025), allowing users to stress test price, volume, and regulatory outcomes.
- Competitive benchmarking scorecards with supplier strength-weakness matrices and suggested countermeasures for each major incumbent and challenger.
- Go-to-market playbooks for five commercialization archetypes — OEM supplier, contract manufacturer, value-brand distributor, premium clinical brand, and regional exporter — each with tailored KPIs and investment triggers.
- Supply-chain heatmaps and a supplier due-diligence playbook that fold in raw-material risk, tariff exposure, and production resilience metrics.
- Regulatory compliance checklist and audit roadmap for entering or expanding in regulated medical channels across major markets.
- Five-year procurement playbook for health system buyers and distributors, with contract templates and hedging approaches to manage feedstock price volatility.
- Primary research annex summarizing interviews with procurement officers, hospital clinicians, OEM product leads, and plant operations managers that validate commercial assumptions.
Use cases — how leading teams will apply these insights in 2026
- Corporate strategy teams: refine portfolio choices between sterile medical sponges and broader non‑medical hygiene lines, using our scenario models to quantify margin trade-offs.
- M&A teams: use the report’s target archetypes and valuation yardsticks to prioritize bolt-ons that accelerate access to sterile medical channels or proprietary non‑woven formulations.
- Procurement: implement PW’s supplier scoring and pricing-index templates to lock in multi-year supply at resilient landed costs.
- R&D and product teams: prioritize product features that clinical buyers increasingly value — absorbency tests, lint metrics, and sterile packaging integrity — validated through our clinical feedback loops.
Final word — positioning for the next wave
The non‑woven sponge market in 2026 rewards disciplined, evidence-led strategies. Growth is steady but not runaway; the real upside is captured by firms that convert regulatory compliance, supply-chain resilience, and product performance into differentiated commercial propositions. PW Consulting’s full report arms leaders with the market sizing, scenario tools, competitive intelligence, and practical templates necessary to make those decisions with confidence.
For executives who need the granular segmentation, regional maps, and SKU-level insight to operationalize these recommendations, consult the complete study and supporting data annex on our website. The preview above outlines the strategic landscape — the full report contains the field‑tested detail required to execute in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Non-woven Sponge Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com