

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Industrial & Electrical Fuses Market Set to Reach USD 7.75 Billion by 2032, Expanding at a 5.21% CAGR

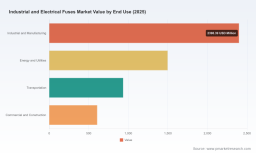
Worldwide Industrial and Electrical Fuses Market — Strategic Outlook for 2026 (PW Consulting)
PW Consulting today releases an executive briefing accompanying its new market study, "Worldwide Industrial and Electrical Fuses Market (Base year 2025)". The briefing synthesizes the study’s most consequential insights for executive teams planning budgets, product roadmaps, procurement strategies and M&A activity in 2026. Our independent analysis shows the global market expanding from roughly USD 4.2 billion in 2020 to about USD 5.44 billion in 2025, with a projected compound annual growth rate (CAGR) of 5.21% across the 2026–2032 forecast window — reaching an expected market size in the neighborhood of USD 7.75 billion by 2032. This briefing explains why those headline figures matter for decisions made this year, what to watch in the supply chain and regulatory landscape, and how incumbent and challenger suppliers should prioritize moves to capture value.
Worldwide Industrial and Electrical Fuses Market
What the report delivers — actionable intelligence, not just numbers
- Independent total-market sizing and a 7-year forecast model, with scenario variants that stress raw-material volatility, regulatory shifts and accelerated electrification.
- Segmented analyses by region, voltage class (low, medium, high) and end-use (industrial, energy/utilities, transportation, commercial). Note: this briefing intentionally highlights themes and implications; detailed segment tables and proprietary share data are available in the full report.
- Supply-chain and input-cost playbooks, including supplier concentration mapping, price-sensitivity matrices and inventory / hedging strategies designed for procurement teams.
- Vendor benchmarking and competitive scorecards covering product breadth, regulatory certifications, channel coverage and innovation capability.
- Strategic roadmaps for product development, margin protection, aftermarket services and M&A targets, with short-, medium- and long-term priority actions.
Macro dynamics shaping 2026 decisions
-
Structural demand drivers: Industrial electrification, grid modernization, distributed renewables and accelerated investment in transportation infrastructure are converging to sustain steady demand for circuit-protection devices. These demand trends underpin the mid-single-digit CAGR embedded in our base forecast and create mid-term demand certainty for suppliers with differentiated portfolios.
Worldwide Industrial and Electrical Fuses Market -
Raw-material exposure and procurement risk: Fuse manufacturing remains materially exposed to copper and related conductive components. Copper constitutes a significant share of element and terminal costs in low-voltage fuse designs; the metal experienced a sharp price spike in early 2026, and leading financial houses continue to forecast elevated, volatile price bands through the year. For procurement and product teams, this requires active hedging strategies, alternative materials evaluation and design-led material efficiency programs to preserve margins.
Worldwide Industrial and Electrical Fuses Market -
Regulatory and standards evolution: Two developments are reshaping product requirements. The latest EN IEC update tightens performance and breaking-capacity requirements for low-voltage fuse-links, while established UL 248 series standards continue to govern North American low-voltage product acceptance. These standards changes create a two-fold implication: (1) compliance is now a gating factor for industrial and utility projects, and (2) suppliers that certify faster and use standards-compliance as a marketing differentiator can command price premiums in safety-sensitive segments.
Competitive landscape — consolidation, specialisation and system integration
The market combines global industrial players with specialised regional manufacturers. PW Consulting’s vendor analysis highlights three strategic archetypes:
-
System integrators and industrial conglomerates (examples among leading names): They embed fuses into broader electrification and power distribution portfolios. Their advantage lies in end-to-end solutions, channel reach and the ability to cross-sell protection products into large infrastructure and industrial accounts.
-
Specialist fuse manufacturers: These firms focus on high-performance, semiconductor and medium-/high-voltage applications. They compete on technical differentiation, certification depth and reliability in demanding environments.
-
Regional OEMs and niche players: These companies often serve local utilities and manufacturing clusters, offering tailored logistics and aftermarket responsiveness.
Our competitive concentration metric shows a market with moderate consolidation: the top three and top five suppliers account for a meaningful share of global revenues, indicating scale advantages for incumbents while leaving room for targeted, high-value niche plays. Recent vendor activity — for example, product presentations and technology showcases by leading suppliers in early 2026 — signals an emphasis on demonstrating system-level protection solutions and aftermarket services as differentiators.
Strategic implications for executives in 2026
-
Procurement and supply chain: Move from reactive purchases to a structured sourcing playbook. Prioritize multi-sourcing for copper-intensive components, implement dynamic hedging where appropriate, and renegotiate OEM contracts with clauses that pass-through or share exceptional raw-material swings. Invest in supplier scorecards that include delivery resilience and technical change management capability.
-
Product and R&D strategy: Accelerate design-for-material-efficiency and consider substituting or alloying conductive elements where performance permits. Fast-track certification programs for updated international standards; compliance is now a gate for certain utility and industrial tenders.
-
Commercial and channel playbook: For system integrators, embed protection offerings into service contracts and lifecycle warranties to shift part of the economics from upfront hardware to recurring service revenue. Niche suppliers should pursue partnerships with global distributors to scale into new regional projects without material capex.
-
M&A and partnership focus: Target acquisitions that close capability gaps — e.g., in semiconductor fuses, high-voltage protection, or aftermarket diagnostics — and prioritize targets with established certification and utility relationships. Joint development agreements for materials and composites can be a faster route to margin protection than greenfield R&D.
How PW Consulting’s modeling supports tactical planning
The full study provides a modular forecasting engine that executives can use to run bespoke scenarios: stress tests for sustained copper price increases, accelerated demand in transportation infrastructure, and regulatory-tightening cases that raise compliance costs. Each scenario includes bottom-line impacts at the portfolio level, margin sensitivity outputs and a prioritized set of mitigation actions. Our vendor scorecards, which synthesize public filings, supplier collateral and primary interviews, rank suppliers on innovation, certification breadth, channel access and service capability — enabling faster shortlists for procurement and acquisition diligence.
What executives will find in the full report (and why you need it)
- Complete historical (2020–2025) and forecast (2026–2032) time series for the global market and all major segments (by geography, voltage class and end-use) — presented as interactive tables and downloadable datasets for financial modelling.
- Supply-chain maps and a raw-material sensitivity module tied to real-world price projections.
- Vendor profiles and scorecards for the leading manufacturers, with a focus on commercial strategy, product roadmaps, and recent development activity.
- Regulatory impact maps showing which product classes and geographies will be most affected by recent standards updates.
- Decision-ready playbooks for procurement, R&D prioritization, go-to-market shifts and M&A screening criteria — sequenced by ease of implementation and expected ROI.
Conclusion — why 2026 is a pivot year
For firms operating in or adjacent to the industrial and electrical fuses sector, 2026 is a decision point. The market’s steady expansion provides growth runway, but margin pressure from raw-material volatility and stronger standards compliance requirements will distinguish winners from laggards. Executives who combine disciplined procurement, focused product differentiation and targeted partnerships (or acquisitions) will not only protect margins but also capture incremental value as utilities, manufacturers and infrastructure projects increasingly demand higher-performance protection solutions.
To access the full dataset, scenario models and vendor scorecards that underpin this briefing, please refer to PW Consulting’s full "Worldwide Industrial and Electrical Fuses Market" report. The detailed segmentation tables and proprietary share estimates — essential for tactical planning and competitive diligence — are available in the full report package.
For enquiries, licensing of the dataset, or bespoke scenario runs tailored to your company’s portfolio, contact PW Consulting’s Industrial Electrification practice.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial and Electrical Fuses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com