

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Automatic Wafer Dicing Saw Market Poised to Reach USD 2.32 Billion by 2032, Growing at a 6.98% CAGR

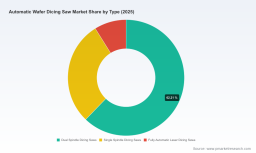
Worldwide Automatic Wafer Dicing Saw Market — Strategic Briefing for 2026 Decisions
PW Consulting’s latest market intelligence on the Worldwide Automatic Wafer Dicing Saw Market frames a pivotal inflection for semiconductor back-end equipment strategy. Between the structural acceleration of advanced packaging and emerging policy pressures on supply chains, corporate decision-makers face a narrow window in 2026 to lock in competitive advantage. This briefing summarizes the report’s strategic value, highlights actionable insights, and previews the types of operational and M&A decisions the full report informs. (Note: detailed regional and application-level splits are intentionally withheld from this release; the full dataset and segmentation tables are available in the complete report.)
Worldwide Automatic Wafer Dicing Saw Market
Headline market dynamics you must factor into 2026 planning
-
Market scale and trajectory: After growing from roughly USD 980.5 million in 2020 to about USD 1,445.5 million in our base year (2025), the global automatic wafer dicing saw market continues to expand. Our forecast period (2026–2032) projects a compound annual growth rate (CAGR) of 6.98%, bringing the market to an estimated USD 2,321.2 million by 2032. This represents both steady demand for traditional blade-based singulation and rising adoption of alternative singulation technologies.
Worldwide Automatic Wafer Dicing Saw Market -
Concentration and competitive dynamics: The market is highly consolidated at the top; our concentration metrics indicate a dominant leading group with strong control over technology roadmaps and supply chains. This structure creates both opportunity (for premium positioning and long-term service contracts) and risk (for suppliers dependent on a limited set of OEM customers).
Worldwide Automatic Wafer Dicing Saw Market -
Technology forces: Two parallel technology tracks are reshaping procurement and roadmap choices — incremental refinements to high-precision blade dicing (dual-spindle automation, AI-based process control, robotic handling) and singulation alternatives (laser-based systems such as Laser MicroJet and plasma singulation). Buyers must weigh throughput, yield, material compatibility (e.g., SiC, sapphire), and long-run consumables economics.
-
Regulatory and supply-chain pressure: Recent policy developments in the U.S. and allied markets are increasing the complexity of global procurement, customs, and supplier qualification. Proposed restrictions on certain procurements and national-security reviews of semiconductor equipment imports have material implications for sourcing strategies and localization investments.
What the full report delivers — practical, transaction-ready analysis
-
Quantitative forecast model: A month-by-month and year-by-year demand model across our forecast horizon (2026–2032), stress-tested under multiple scenarios (base, accelerated packaging adoption, and restrictive-trade). The model is provided in editable format to support your internal financial planning.
-
Commercial segmentation and TAM analysis: Market sizing by type, wafer size capability, and application with customer-level referencing (note: segmentation tables are reserved for the full report).
-
Competitive benchmarking: Detailed company profiles, product roadmaps, installed-base estimates, and margin/color maps for incumbent and challenger suppliers. Profiles include technical differentiation, service footprints, and potential white-space opportunities for new entrants.
-
Supply-chain & cost-to-serve diagnostics: Consumables economics, spare-parts lead-time matrices, and a supplier-risk heat map that identifies single-source dependencies and logistics chokepoints.
-
Regulatory impact playbook: Scenarios for policy shocks (procurement restrictions, export controls, national-security investigations) and playbooks to mitigate disruption — from nearshoring to dual-sourcing and contractual protections.
-
Go-to-market and partnerships guide: Prioritized partner lists, reseller economics, and alliance blueprints for OEMs and system integrators targeting advanced packaging customers.
-
M&A and investment screening: Deal-screen scorecards calibrated to the sector’s KPIs — technology adjacency, installed base synergies, consumables revenue potential, and regulatory exposure.
Competitive landscape — who’s shaping the market and why it matters
-
DISCO Corporation (Tokyo): A recognized leader with a broad portfolio of fully automatic blade dicing saws and high-precision dual-spindle systems. Recent product introductions emphasize AI-enabled process control and SEMI-compatible robotic handling, signaling a push toward higher automation and reduced operator intervention. For buyers, DISCO’s roadmap represents a benchmark for throughput, yield, and total-cost-of-ownership.
-
Tokyo Seimitsu / Accretech (Tokyo): Focused on 300mm-capable platforms and dual-spindle, step-cut capabilities, with strategic partnerships to secure consumable supplies (blades). Their product launches and industrial partnerships indicate a combined emphasis on platform robustness and consumable lifecycle management.
-
Advanced Dicing Technologies (ADT) / Kulicke & Soffa: ADT brings twin-spindle solutions optimized for a broad set of packages and board types; affiliation with larger packaging equipment suppliers gives it channel breadth and aftermarket scale. Watch for cross-sell opportunities within broader back-end portfolios.
-
Synova (Switzerland): A differentiated player with Laser MicroJet offerings that enable damage-free cutting for hard and brittle substrates (e.g., SiC, sapphire). Laser-based singulation is increasingly relevant for compound-semiconductor and optoelectronic manufacturing nodes that struggle with blade-induced damage.
-
Regional and niche vendors: A spectrum of suppliers from China, Europe, and North America provides alternatives on price, customization, and local support. These vendors are important partners for capacity expansion or as contingency suppliers amid trade restrictions.
Recent industry moves to incorporate into procurement and product strategies
-
Automation & AI: Market leaders have introduced AI-based kerf-width monitoring and enhanced robotics to reduce manual handling and improve yield consistency — features that will increasingly differentiate premium platforms in 2026 procurement cycles.
-
300mm and large-panel readiness: Several OEMs have released or announced platforms that natively support larger wafer sizes and panel singulation, aligning equipment roadmaps with the industry’s advanced packaging and fan-out wafer-level packaging (FOWLP) requirements.
-
Alternative singulation: Plasma and laser-based singulation solutions (including advanced plasma singulation systems) are emerging as complementary or substitute technologies in certain applications, especially where wafer thinning and material fragility constrain blade use.
-
Strategic partnerships: Joint ventures between machine manufacturers and consumable producers are becoming more common, reflecting the importance of blade supply, lifecycle services, and integrated warranty/consumables contracts.
Implications for corporate strategy in 2026 — what we recommend
-
Re-evaluate platform procurement vs. OPEX models: Given the market’s projected CAGR and equipment-led differentiation, companies should model both CAPEX purchases and equipment-as-a-service arrangements to balance throughput needs with balance-sheet discipline.
-
Prioritize automation and predictive maintenance: Spec platforms with AI-enabled process control and remote diagnostics to lower yield variability and reduce on-site service dependency — a key factor under constrained travel and localized support scenarios.
-
Hedge technology risk with mixed-technology roadmaps: For fabs processing diverse materials (Si, SiC, sapphire), adopt a hybrid singulation strategy (high-precision blade + laser/plasma pilots) to manage yield and R&D risk.
-
Mitigate regulatory exposure: Immediately map equipment and key suppliers against emerging procurement restrictions; where necessary, accelerate qualifying of alternate vendors or shift to nearshore suppliers to preserve procurement flexibility.
-
Capture aftermarket value: Given the sector’s consumables-dominated service economics, develop or secure long-term blade and parts agreements; integrated consumables programs can convert equipment sales into durable annuity streams.
-
Use M&A selectively to accelerate capability: Target acquisitions that deliver installed-base synergies, consumables scale, or differentiated technology (e.g., laser singulation) rather than only chasing incremental capacity.
Why PW Consulting’s report is decision-ready for 2026
Our research combines an audited historical topline (2020–2025), a granular, model-backed forecast (2026–2032), and a policy-risk overlay that reflects the latest trade and procurement developments. The report’s core value is not only in the headline market figures — which show a nearly 7% CAGR and a roughly 1.5x expansion from the 2025 base to the 2032 horizon — but in the work-ready tools: scenario financials, supplier-risk matrices, and deal-screen templates that procurement, product, and corporate development teams can drop into their 2026 planning cycles.
Next steps and how to obtain the full intelligence
This release deliberately abstracts the report’s granular regional and application splits to preserve the integrity of PW Consulting’s proprietary segmentation and to direct stakeholders to the full dataset. Clients and licensed subscribers receive the complete quantitative annex, editable forecast models, vendor playbooks, and our advisory time allocation to prioritize initiatives through 2026.
To request a briefing or obtain the full Worldwide Automatic Wafer Dicing Saw Market report and supporting deliverables, contact PW Consulting’s semiconductor equipment practice. Our team will provide a tailored walkthrough of scenario outcomes most relevant to your strategic options.
For detailed analysis of this topic, please visit the official page: Worldwide Automatic Wafer Dicing Saw Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com