

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Non‑GMO Textured Soybean Protein Market Reaches USD 1,580.4 Million in 2025, Poised to Grow at 8.24% CAGR Through 2032

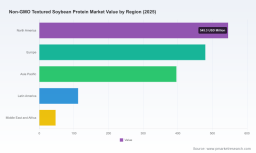
Worldwide Non-GMO Textured Soybean Protein Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
PW Consulting’s forthcoming market brief on the Worldwide Non-GMO Textured Soybean Protein market is designed as a decision-grade intelligence tool for executives preparing strategy, procurement, and product roadmaps in 2026. The market has moved from niche to mainstream in under a decade, with a measured compound annual growth rate (CAGR) of 8.24% projected across the 2026–2032 forecast window. On a macro basis, our model indicates the market stood at roughly USD 1.58 billion in 2025 and is forecast to exceed USD 2.7 billion by 2032. Those headline dynamics frame the choices that C-suite teams, category leads, and supply-chain planners must make this year.
Worldwide Non-GMO Textured Soybean Protein Market
Why this matters for 2026 strategy
Non-GMO textured soybean protein is no longer a “marketing-only” ingredient. It has become an operational lever for food manufacturers, ingredient houses, and branded product owners who seek to comply with evolving clean-label expectations while optimizing cost and performance attributes in plant-based formulations. That shift has three immediate implications for 2026 planning:
Worldwide Non-GMO Textured Soybean Protein Market
- Supply architecture: Sourcing non-GMO identity-preserved (IP) soy requires different contracting rhythms and supplier relationships than commodity soy — from forward acreage contracts to third-party certification alignment.
- Portfolio prioritization: R&D and NPD pipelines that rely on textured soy must reconcile protein functionality, sensory neutrality, and cost-to-serve in a market that is growing north of 8% per year.
- Competitive positioning: The supplier landscape is moderately concentrated; scale and access to IP supply confer tangible advantages for companies seeking to deliver consistent non-GMO credentials at industrial volumes.
Market trajectory and what the headline numbers mean
The headline CAGR of 8.24% is not an abstract metric: it reflects a confluence of demand-side adoption (meat and dairy alternative product scaling, clean-label consumer preferences) and supply-side investments (capacity expansions, identity-preserved sourcing programs, and new processing lines). Between 2020 and 2025 the market expanded materially, and our baseline shows continued expansion in 2026 and beyond — reinforcing that strategic moves taken in 2026 should anticipate multi-year commitments to sourcing, capacity, or contract design.
Worldwide Non-GMO Textured Soybean Protein Market
From a practical viewpoint, the growth profile means three planning realities for 2026:
- Contract tenors and renewal windows become strategic levers. Purchasing teams should redesign contracts to hedge price and availability risk without sacrificing IP integrity.
- Manufacturing and formulation investments should be sized to a multi-year growth path rather than a short-term spike, particularly in regions where alternative protein launches are concentrated.
- M&A and JV activity will increasingly be evaluated not just on margin expansion but on access to verified non-GMO supply chains and downstream co-manufacturing capabilities.
Dynamics shaping supply and costs
Three supply-side dynamics deserve explicit attention in 2026 planning:
- Identity preservation and certification. Non-GMO credentials are operationalized through IP programs and third-party certification. These mechanisms add traceability cost but deliver premium access to clean-label channels — an essential consideration for premium and private-label brands.
- Raw material availability and grower economics. Non-GMO soybean volumes for food use remain a fraction of total soybean production. That limited planted base underpins tighter supply elasticities in certain sourcing corridors and prompts buyers to consider multi-origin or long-term contracting strategies.
- Industrial capacity and technology investments. Recent greenfield and brownfield investments — including new integrated facilities commissioned in 2025 — materially increase the available capacity for non-GMO textured soy and reduce finished-product cost-to-serve when paired with IP supply chains.
Competitive landscape — who to watch
The market’s supplier set combines global agribusiness majors, ingredient specialists, and regional manufacturers. A top-three/top-five concentration shows that scale matters: a minority of large players control a significant share of the market, while a broader cohort of regional producers competes on certification, specialization, and service.
Profiles to consider for 2026 partnership and competitive analysis include:
- Global agribusiness incumbents that have expanded non-GMO capabilities via M&A and integrated facilities, offering broad product portfolios and multi-regional supply security.
- Ingredient and flavor firms that combine IP sourcing programs with premium positioning and specialty formulations designed for meat-analog and functional applications.
- Regional producers in Asia and Europe that provide local short‑circuit supply for customers focused on origin claims, organic certification pathways, and logistical proximity.
Recent corporate developments underline two strategic themes. First, capacity investment is accelerating with integrated processing lines coming online to feed textured soy concentrate demand. Second, identity-preserved programs and certification partnerships are being used as competitive differentiators rather than compliance artifacts — firms are leveraging traceability to enter higher-margin clean-label categories.
What our full report delivers for 2026 decision cycles
PW Consulting’s report is built as an operational playbook rather than an academic exercise. It supplies granular decision support across five use cases:
- Procurement optimization: decision trees, contract templates, and a supplier scorecard methodology to evaluate IP capability, capacity flexibility, and service resilience.
- Product development and formulation: functionality maps showing trade-offs among protein formats, processing parameters, and sensory outcomes — with recommended starting points for common meat-analog and dairy-alternative formulations.
- Supply-chain resilience planning: scenario-based stress tests (price shocks, supply shortfalls, certification disruption) with mitigation playbooks and inventory modeling.
- M&A and partnership diligence: a checklist for assessing strategic fit, including how IP sourcing, facility footprint, and channel relationships translate into enterprise value in a market with meaningful concentration.
- Regulatory and claims governance: an implementation guide to third-party certifications, labeling rules, and cross-border claim management to preserve non-GMO integrity while enabling market claims.
How to use the intelligence in 90–180 day plans
For executives with limited bandwidth, the report translates into discrete 90- and 180-day action plans:
- 90-day sprint: prioritize supplier audits against IP capability, pilot alternate suppliers for critical SKUs, and finalize contract language on traceability and contingency supply.
- 180-day program: lock in multi-year acreage contracts where appropriate, deploy formulation pilots that reduce cost-per-protein-point without sacrificing sensory profile, and initiate strategic conversations with potential co-manufacturing partners.
Risk matrix — practical early-warning indicators
We provide an operational risk matrix tailored for 2026 that flags three early-warning indicators buyers and product teams should monitor weekly or monthly:
- Certificate throughput and audit exceptions in key suppliers’ IP programs.
- Order fill-rate deviations at strategic suppliers and changes in lead time variance.
- Price spreads between identity-preserved non-GMO contracts and commodity supply — widening spreads can indicate tightening non-GMO availability.
Why PW Consulting’s approach adds value
Our analysis blends time-series market modeling with supplier-level due diligence and operational playbooks. We do not only estimate market size and growth: we provide executable frameworks to translate those estimates into procurement, R&D, and M&A moves. For 2026, that means the difference between tactical fixes and structural advantage.
Next steps — where to get the full intelligence
This article is a strategic preview. For the full market model, segmented forecasts, supplier scorecards, scenario-modeled supply-risk analytics, and the appendices with methodological detail, please consult the report landing page listed in PW Consulting’s release materials. The full report contains the granular tables, regional and application splits, and downloadable datasets required for transaction diligence and internal planning workshops.
In an industry where traceability, scale, and formulation performance intersect, 2026 will reward organizations that combine procurement foresight with product agility. PW Consulting’s Worldwide Non-GMO Textured Soybean Protein Market report equips leaders to make those trade-offs with clarity and confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Non-GMO Textured Soybean Protein Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com