

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Worldwide Photobiostimulation Devices Market Poised for 6.9% CAGR Through 2032

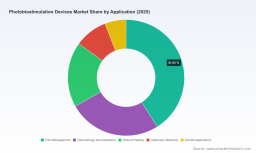
Worldwide Photobiostimulation Devices Market — Strategic Insights for 2026 Corporate Decision-Making
PW Consulting’s new market study on Worldwide Photobiostimulation Devices provides a purpose-built intelligence package for executive teams, investors, and innovation leaders who must make decisive 2026 bets in a fast-evolving field. Grounded in a historical base (2020–2025) and a forward-looking forecast window (2026–2032), the report quantifies the sector’s expansion trajectory — the market grew from a resilient base in 2020 to an estimated USD 353.9 Million in 2025 and is modeled to reach approximately USD 564.6 Million by 2032 at a compounded annual growth rate (CAGR) of 6.9% over the forecast period. Those headline figures understate richer structural shifts that will determine winners and losers in the near term; this briefing highlights the strategic implications for decisions you will make in 2026.
Worldwide Photobiostimulation Devices Market
Why 2026 Is an Inflection Year
-
Regulatory and reimbursement inflection points are aligning. The FDA’s increasing clarity on photobiomodulation submissions — including draft guidance issued in 2023 and the high-profile de novo authorization for ophthalmic PBM — has lowered regulatory ambiguity for certain clinical indications. Simultaneously, new billing codes and nascent reimbursement pathways (notably a Category III retina PBM code that came into effect in 2025) are creating the first routable commercial pathways for higher-value medical indications.
Worldwide Photobiostimulation Devices Market -
Product and channel bifurcation is accelerating. Clinical-grade, regulated therapies are converging with consumer and at-home LED wellness products. This dual trajectory is expanding addressable markets but also raising competitive complexity for developers, distributors, and payers.
Worldwide Photobiostimulation Devices Market -
Consolidation and strategic partnerships are underway. M&A activity among established device and ophthalmology platform players, and acquisitions of PBM innovators by larger healthcare companies, signal that corporate buyers are incorporating PBM as a strategic adjacency rather than a niche modality.
What PW Consulting’s Report Delivers — Practical, Transaction-Grade Workstreams
-
Proprietary demand model and revenue scenarios: top-down and bottom-up projections across 2026–2032, with sensitivity cases driven by regulatory outcomes, reimbursement adoption curves, and consumer channel penetration.
-
Clinical-evidence map and regulatory playbook: indication-by-indication evidence synthesis tied to regulatory pathway recommendations (510(k), de novo, CE, and selected international routes).
-
Reimbursement and payer engagement guide: pragmatic roadmaps for CPT code usage, Medicare positioning, payer dossiers, and outcome measures required to unlock commercial payments.
-
Competitive intelligence and benchmarking: company scorecards, technology archetypes (laser vs. LED, Class II/III/IV distinctions), and go-to-market archetypes for OEMs, service providers, and retail channels.
-
M&A and partnership playbooks: valuation drivers, integration risks, and diligence checklists tailored to acquirers and target management teams.
-
Commercial launch and channel optimization tools: pricing sensitivity matrices, clinic vs. at-home unit economics, and digital engagement tactics to accelerate adoption.
Data-Driven Signals: What the Numbers Mean for Strategy
-
Market momentum with differentiated growth pockets. The sector’s steady rise from 2020 through 2025, followed by continued expansion at a mid-single-digit CAGR, confirms a market that is neither hyper-saturated nor nascent. Investors should treat PBM as a growth sector with predictable upsides tied to specific clinical validations and reimbursement wins.
-
Moderate concentration creates strategic opportunity. Market concentration metrics indicate that the top three and top five firms control a meaningful share of industry revenues, but there is ample room for challengers with differentiated technology, stronger evidence packages, or innovative commercial models. In short: defensible niches still exist.
-
Regulatory and reimbursement milestones are multiplier events. The de novo authorization for an ophthalmic PBM device and the emergence of a retina-related CPT code are emblematic: clinical approvals that expand indications materially change unit economics and payer interest. Near-term winners will be those that translate clinical authorization into reproducible clinical pathways and payer evidence.
-
Channel bifurcation demands dual playbooks. Companies that can manage regulated clinical commercialization while simultaneously capturing high-margin at-home and wellness demand — without diluting medical claims or triggering regulatory pushback — will compound returns faster than single-channel incumbents.
Competitive Landscape — Strategic Profiles and Tactics
-
THOR Photomedicine Ltd: A specialist with strong medical-device credentials and multi-jurisdictional clearances. THOR’s strength is in clinical positioning and device certifications that support clinic-based adoption. Strategy: deepen specialty partnerships, expand indication dossiers, and translate full-body and targeted platforms into reimbursable services.
-
Erchonia Corporation: Market-savvy with a broad portfolio of non-thermal low-level lasers and multiple FDA clearances. Erchonia’s playbook centers on clinician adoption across pain, dental, and veterinary applications. Strategy: leverage existing regulatory footholds to enter new therapeutic bundles and franchised clinic models.
-
Vielight Inc.: Home-focused LED brain stimulation and wellness devices. Vielight exemplifies the consumer-driven edge of PBM; success here depends on compelling consumer evidence and direct-to-consumer channels. Strategy: prioritize long-term outcome studies and subscription-based services to lock in recurring revenue.
-
LightForce Therapy Lasers & LumaCare Lasers: Deep-tissue and portable clinical laser leaders focused on musculoskeletal care. Their competitive advantage is clinical performance and practitioner workflows. Strategy: integrate with digital outcome-tracking and physiotherapy bundles to enhance payer relevance.
-
Microlight, Avant, ARRC LED, LightMD, TheraLight, Bioflex: These firms represent a spectrum from legacy pioneers to emerging whole-body and clinical-grade systems. Tactics across this cohort include OEM partnerships, licensing of optical modules, and vertical integration of service offerings.
-
LumiThera / Alcon transaction: The pending acquisition and prior de novo authorization for an ophthalmic PBM device is the clearest signal that large medical-device incumbents view PBM as a strategic augmentation to their portfolios. Expect more targeted M&A and co-development deals.
Strategic Recommendations for 2026 Decision-Makers
-
Prioritize indication-specific evidence. Allocate development capital to create pivotal studies that align with clear regulatory pathways and payer value propositions; ophthalmology and certain pain indications currently offer the highest leverage.
-
Design dual commercialization strategies. Build separate but coordinated plans for clinical (regulated, evidence-driven) and consumer (wellness, subscription, retail) channels to avoid brand dilution or regulatory conflation.
-
Engage early with payers and professional societies. Use pilot programs, PRO measures, and health-economic modeling to accelerate coverage decisions and CPT-to-coverage translation.
-
Consider tuck-in acquisitions for capability gaps. Targets that deliver clinical trial expertise, distribution in key clinical channels, or differentiated optical modules can be high-ROI buys given moderate market concentration.
-
Invest in post-market data capture and real-world evidence. Registries and digital outcome platforms will materially improve contracting leverage and long-term adoption.
-
Hedge on component and manufacturing supply chains. As device complexity and scale increase, secure long-lead optical components and assembly capacity to avoid costly time-to-market delays.
How to Use This Report in 2026 Tactical Planning
-
Board-level scenario planning: use our upside / downside market scenarios to stress-test capital allocation and M&A thesis.
-
Portfolio prioritization: apply our indication-by-indication ROI dashboards to rank development projects and channel pilots.
-
Commercial realignment: adopt our go-to-market templates to align field teams, digital channels, and payer strategies for launch windows tied to regulatory milestones.
Next Steps — Where to Get the Full Intelligence
PW Consulting’s Worldwide Photobiostimulation Devices Market report was built to inform executable 2026 decisions: it pairs headline projections (historical performance through 2025, a forecast to 2032 at a 6.9% CAGR) with transaction-grade annexes — granular segmentation tables, company financial proxies, full regulatory and reimbursement matrices, and downloadable modeling files. To preserve the value of our proprietary analyses and to support confidential decision-making, detailed subsegment tables and company-level revenue breakdowns are published exclusively in the full report and on our secure client portal.
Contact PW Consulting for a brief walkthrough of the report’s executive deck and a customized briefing that maps the analysis directly to your strategic options for 2026. Our team will demonstrate how to convert the report’s scenarios into a prioritized action plan with milestones, KPIs, and a 12–24 month implementation roadmap.
For detailed analysis of this topic, please visit the official page: Worldwide Photobiostimulation Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com